In a nutshell:
Major US benchmarks mixed, with S&P 500 and Nasdaq's three-day winning streak ending after a tech sell-off led by Alphabet's 12.6% tumble, while defensive sectors and small caps outperformed in a broad rotation
Alphabet’s record one-day market value wipeout, driven by a search miss and negative free cash flow, revived doubts over AI spending returns ahead of Amazon’s result
Treasuries firmed and December Fed hike bets fell to 76% after in-line PCE inflation and stronger-than-expected Q3 GDP growth, as the ECB held rates and Lagarde set an early exit
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,720 | -0.30% |
Dow Jones | 52,343 | -0.25% |
NASDAQ Comp | 26,185 | -1.38% |
Russell 2000 | 2,859 | +1.01% |
Global Indices | ||
 S&P/TSX | 36,249 | -0.04% |
 Shanghai Composite | 3,651 | -0.82% |
 DAX | 26,040 | +1.31% |
 Hang Seng | 22,959 | -0.59% |
 Nifty 50 | 74,151 | +1.24% |
 Nikkei 225 | 64,659 | +1.10% |
 FTSE 100 | 10,722 | +0.26% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,021.33 | -1.14% |
 Copper | 6.56 | -1.25% |
 WTI Oil | 102.92 | +0.13% |
Currency | ||
 AUD/USD | 0.7028 | -0.36% |
Cryptocurrency | ||
 Bitcoin (USD) | 78,926 | -2.88% |
 Ethereum (AUD) | 3,212 | -4.27% |
Miscellaneous | ||
US 10 Yr T-bond | 4.989 | -1.11% |
VIX | 17.2 | +1.71% |
US Sectors
Sector | % Chg |
|---|---|
| Health Care | +2.50% |
| Real Estate | +2.25% |
| Consumer Staples | +1.64% |
| Utilities | +1.56% |
| Financials | +1.52% |
| Industrials | +1.00% |
Sector | % Chg |
|---|---|
| Materials | +0.89% |
| Energy | +0.42% |
| Consumer Discretionary | -0.63% |
| Information Technology | -0.88% |
| Communication Services | -6.60% |
S&P 500 Session Chart
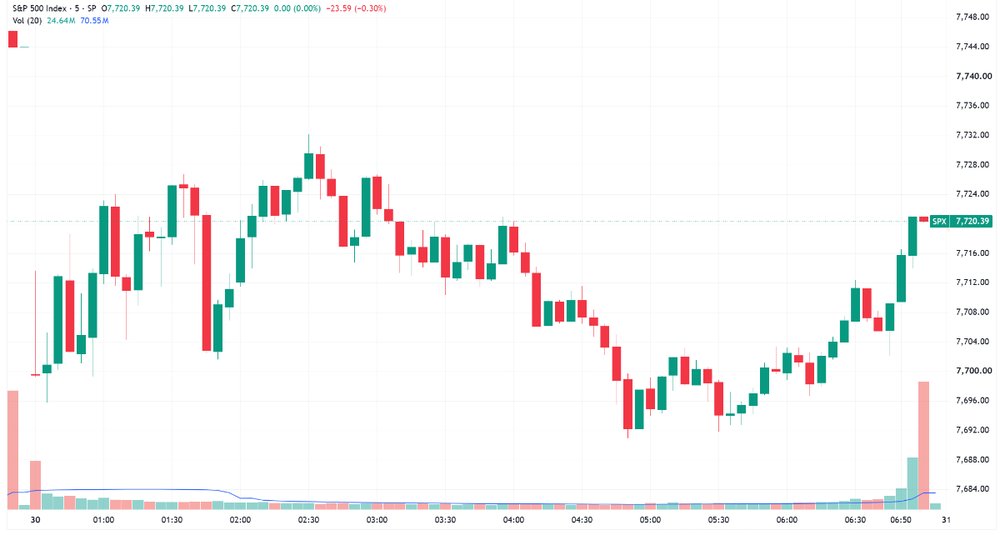
S&P 500 lower after a choppy and relatively rangebound session (Source: TradingView)
Overnight Markets
Major US benchmarks lower, finished off worst levels, as a record 12.6% plunge in Alphabet revived AI spending doubts, dragging the Nasdaq 100 down 1.4% while money rotated into the broader market
Software stocks broadly weaker as Fortinet and ServiceNow each dropped more than 20% after quarterly results
S&P 500 Equal Weight index rose 1.2% to outperform the cap-weighted index, with Healthcare, REITs and Financials leading gains across eight of the 11 sectors
US 10-year bond yield eased 6bps to 4.9%, its lowest level since 23 September the 2-year slipped 8bps to 4.6% as bonds caught a haven bid amid the tech selloff
Brent rose to around US$116 a barrel and WTI to about US$102 even after JD Vance reportedly reached out to Iran’s Rezaei to restart peace talks, though possible post-midterm US strikes kept supply risk alive (CNBC)
Microsoft drew blowout demand for a bond sale of at least $25bn, its first US investment-grade deal since 2017 and a key test of appetite for AI-linked debt (BBG)
Citi's Scott Chronert reiterated his 8,100 year-end S&P 500 target despite the AI selloff, though he flagged a December Fed hike as a complication (CNBC)
Pepperstone’s Chris Weston said markets are questioning how much to pay for Alphabet’s AI opportunity given the cash-flow cost, adding investors are increasingly unforgiving when spending, margins and cash generation disappoint (BBG)
Microsoft plans to raise about $25bn in its first US investment-grade bond sale in more than nine years, the latest hyperscaler to tap debt markets to fund its AI buildout (RT)
Stocks
Alphabet Q3: revenue up 25% to $127.6bn, adjusted EPS $2.67 missed ests by ~12%, search up 12% to about $63bn and short of ests again, free cash flow negative $9bn, shares slumped about 13% in a record one-day market value wipeout of roughly $500bn (CNBC)
Amazon Q3 revenue up 12% to $201.9bn, slightly below ests, AWS revenue $45.9bn, ahead of ests, EPS $1.89 missed ests by ~4%, Q4 sales guidance midpoint below ests, 2026 capex held at $220bn, shares down ~7% after hours (YF)
Eli Lilly Q3 revenue up 39% to $24.4bn, ~9% ahead of ests, Mounjaro up 65% to $10.7bn, adjusted EPS $7.48 beat ests by ~34%, FY26 revenue guidance raised to $91-92bn, shares up ~6% (YF)
Intel Q3 revenue up 21% to $16.5bn, in line with ests, adjusted EPS $0.52 beat ests by ~27%, but Q4 revenue guidance of $15-16bn trails $17bn ests on a PC slump and an Israel plant explosion, shares down ~20% after hours (YF)
Caterpillar Q3: adjusted EPS $7.20 and revenue $20.68bn only modestly beat ests, guidance for moderate Q4 sales growth disappointed investors betting on AI data-centre power demand despite a record $78bn backlog, shares fell as much as 12%, leaving the stock almost 40% below its June peak (YF)
Shell Q3: adjusted earnings almost doubled to $10.81bn, beating ests by ~5% and the highest since 2022, as Iran war disruption drove a record refining margin of $42 a barrel, quarterly buyback lifted to $5bn from $3bn (RT)
Marvell is in advanced talks to buy optical parts maker Lumentum in a deal that could be announced as soon as next week, sending Marvell shares down 11% and Lumentum up 5% (BBG)
Geopolitics
Iran’s Revolutionary Guards said three tankers struck mines and caught fire on an unauthorised route south of the Strait of Hormuz, a day after US forces said key routes had been cleared (RT)
Vance’s letter to Iran’s top security official Mohsen Rezaei said any talks to avert further US strikes would require discussions on the nuclear issue, with Trump enthusiastic about the outreach, a US official said (Axios)
Final results are likely to confirm Netanyahu’s bloc lost its parliamentary majority after Arab-led parties posted a record showing, with Netanyahu alleging those parties stole the election (AP)
Tariffs
Trump held off on tariffs for robotics, industrial machinery and components, instead directing officials to negotiate with trading partners after a Commerce probe found imports threaten US national security (BBG)
Central Banks
ECB held its deposit rate at 2.5% in a unanimous decision, though Lagarde said policymakers seriously debated a hike and signalled readiness to act if French bond turmoil impairs policy transmission (YF)
Lagarde will step down as ECB president on 7 February 2027, about eight months early, with euro area inflation at a three-year high of 3.8% and leaders now tasked with choosing a successor (YF)
Markets priced an 83% chance of a quarter-point Fed hike in December after the PCE and GDP data, with the 10-year Treasury yield hovering around 5% (CNBC)
Economy
US Q3 GDP grew at a 3.4% annualised rate, beating ests of 3.1% and accelerating from 2.2%, as business investment surged 12.7% on the AI build-out and consumer spending rose 3.8% (YF)
US September PCE inflation rose to 3.6% from 3.4%, in line with ests, while core PCE rose 0.3% month-on-month and 3.1% year-on-year, both matching ests (YF)
US initial jobless claims fell 1,000 to 194,000 in the week to 24 October, below ests of 199,000 and near 57-year lows, while continuing claims dropped to 1.701m (RT)
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Steel | 101.3 | -0.13% |
| Copper Miners | 75.9 | -1.21% |
| Uranium | 35.72 | -2.27% |
| Silver Miners | 75.46 | -2.67% |
| Lithium & Battery Tech | 60.94 | -2.79% |
| Strategic Metals | 52.69 | -3.05% |
| Gold Miners | 81.33 | -3.12% |
Industrials | ||
| Aerospace & Defense | 214.3 | +3.16% |
| Construction | 90.79 | +2.48% |
| Global Jets | 27.49 | +1.93% |
| Agriculture | 27.17 | +0.22% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 217.86 | +0.70% |
Renewables | ||
| Solar | 41.18 | +0.49% |
| Hydrogen | 36.34 | -2.94% |
Technology | ||
| FinTech | 24.25 | +0.54% |
| Data Center & Digital Infrastructure | 26.35 | -0.30% |
| Electric Vehicles | 30.3 | -1.46% |
| Semiconductor | 513.86 | -1.55% |
| Cybersecurity | 51.02 | -1.71% |
| Robotics & AI | 33.42 | -1.79% |
| Cloud Computing | 29.24 | -3.56% |
ASX Today
The last day of quarterly reporting season brings an avalanche of small caps. Here are the higher-profile announcements this morning, but there are hundreds of Sep-Q updates out there.
Capstone Copper posts record Q3 adjusted EBITDA of US$358.3m, its eighth straight record quarter, on revenue up 19% to US$712.0m and a realised copper price of US$6.61/lb. Produced 45,218t of copper at C1 costs of US$2.95/lb and completed the Mantoverde sulphide concentrator tie-in (CSC)
Civmec reports Q1 FY27 revenue of $324m, up around 70% on pcp, with NPAT up around 75% to $18.4m and EBITDA of $35.1m at a 10.8% margin. Order book sits at ~$1.4bn against $1.15bn a year ago, led by the Wagerup Gallium award (CVL)
Count acquires a 30% stake in Brisbane accounting and advice firm Apiary, its fourth deal this financial year, with completion due 1 December. Q1 FY27 revenue rose 23.2% to $52.1m and underlying EBITA jumped 66.6% to $12.7m, with FUM up 31.3% to $6.7bn (CUP)
Helia reports 3Q26 NPAT of $36.5m, with year-to-date GWP more than halving to $82.5m after the loss of the CBA contract, the expanded 5% Deposit Scheme and a slowing housing market. Claims turned positive at $5.1m as 90-day delinquencies rose to 0.83%. FY26 insurance revenue guidance unchanged at $330-360m (HLI)
Resmed lifts Q1 FY27 revenue 6% to US$1.4bn, or 7% on a core constant currency basis, with non-GAAP diluted EPS up 14% to US$2.91. Returned more than US$1.0bn to shareholders through buybacks and dividends and closed the MatrixCare divestiture (RMD)
What To Watch Today
Hi there! Kerry here (Joe’s written everything else). In a nutshell, soft megacap tech earnings have put the defensive pivot back in the spotlight. Let’s see if local names like Woolworths, Charter Hall and Telstra catch a bid. Miners struggled overnight, so our copper, iron ore, lithium and gold names could be on the back foot.
Flip the switch. Battered miners and tech have staged a bit of a recovery over the past few days, with the S&P/ASX 200 Materials and Tech indices up 5.0% and 2.6% respectively. That rotation has sparked a slight pullback in Staples and Telcos, though high-flying defensives like Real Estate and Banks have kept grinding higher. Overnight, Wall Street swung back to the recent defensive trade. Healthcare and Real Estate led the S&P 500 with gains of more than 2%, while Staples, Utilities and Financials all added 1.5%. Bonds were also helpful, with the US 10-year yield falling 6 bps to 4.93%, its lowest since 10-Sep. It looks like the market is starting to position for “the last hike”, which explains the strength in yield-sensitive sectors like REITs. Commodities mostly pulled back, with copper down 1.3% to US$6.65/lb and gold 1.0% lower to US$4,022/oz, dragging the resource ETFs on our overnight watchlist lower: Copper Miners (-1.2%), Uranium (-2.2%), Rare Earths/Strategic Metals (-3.0%), Gold Miners (-3.1%) and Nickel (-3.1%). The iShares Expanded Tech-Software ETF also fell 3.5%. Miners put in a low earlier this week and had started to turn, but this is the first real test of that bottoming process (or perhaps time for new lows, we shall see).
Key Events
Stocks trading ex-dividend:
Fri 30 Oct: MA Credit Income Trust (MA1) – $0.016, Metrics Income Opportunities Trust (MOT) – $0.011, Metrics Master Income Trust (MXT) – $0.015, Metrics Real Estate Multi-Strategy Fund (MRE) – $0.01, Stanmore Resources (SMR) – $0.031
Mon 2 Nov: Djerriwarrh Investments (DJW) – $0.037, La Trobe Private Credit Fund (LF1) – $0.013, N1 Holdings (N1H) – $0.004, Pengana Global Private Credit Trust (PCX) – $0.013
Tue 3 Nov: WAM Global (WGB) – $0.066
Wed 4 Nov: None
Thu 5 Nov: Future Generation Global (FGG) – $0.042
Other ASX corporate actions today:
Dividends paid: Acrow (ACF), Cedar Woods Properties (CWP), FFI Holdings (FFI), GenusPlus Group (GNP), Po Valley Energy (PVE), RAM Essential Services Property Fund (REP), Rivco Australia (RIV), Rural Funds Group (RFF), Star Combo Pharma (S66), Steamships Trading Co (SST), Tasmea (TEA)
IPOs: None
AGMs: CAR Group (CAR), Cobram Estate Olives (CBO), Endeavour Group (EDV), GWA Group (GWA), Korvest (KOV), Pinnacle Investment Management (PNI), PolyNovo (PNV), Reece (REH), Sandfire Resources (SFR), Tabcorp (TAH)
Economic calendar (AEDT):
11:30 am: Australia PPI
2:00 pm: Bank of Japan Interest Rate Decision