In a nutshell:
Major US benchmarks rallied, with the Nasdaq closing at a record for the first time since June and the S&P 500 posting its best session since early August
Semis drove the bulk of gains, with Meta’s new Muse AI agent sparking a scramble for server CPU exposure, sending AMD’s market cap above US$1tn for the first time
Brent is on a four-day skid, now trading back at US$100 a barrel on hopes of US-Iran diplomacy at this week's UN General Assembly
The ASX Live Blog won't run today, with the Market Index team at Livewire Live
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,765 | +1.49% |
Dow Jones | 52,049 | +0.71% |
NASDAQ Comp | 27,122 | +2.26% |
Russell 2000 | 2,875 | +0.52% |
Global Indices | ||
 S&P/TSX | 36,009 | +0.57% |
 Shanghai Composite | 3,950 | +0.97% |
 DAX | 25,575 | +1.07% |
 Hang Seng | 25,043 | +1.18% |
 Nifty 50 | 74,859 | +0.76% |
 Nikkei 225 | 65,019 | +1.38% |
 FTSE 100 | 10,739 | +0.75% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,343.02 | -0.92% |
 Copper | 6.71 | +1.51% |
 WTI Oil | 95.49 | -4.80% |
Currency | ||
 AUD/USD | 0.7121 | +0.04% |
Cryptocurrency | ||
 Bitcoin (USD) | 86,643 | +6.71% |
 Ethereum (AUD) | 3,891 | +5.22% |
Miscellaneous | ||
US 10 Yr T-bond | 4.963 | -0.70% |
VIX | 14.87 | +0.41% |
US Sectors
Sector | % Chg |
|---|---|
| Communication Services | +3.86% |
| Information Technology | +2.46% |
| Consumer Discretionary | +1.49% |
| Real Estate | +1.06% |
| Health Care | +0.67% |
| Industrials | +0.36% |
Sector | % Chg |
|---|---|
| Financials | +0.30% |
| Materials | -0.19% |
| Consumer Staples | -0.36% |
| Utilities | -0.43% |
| Energy | -2.57% |
S&P 500 Session Chart
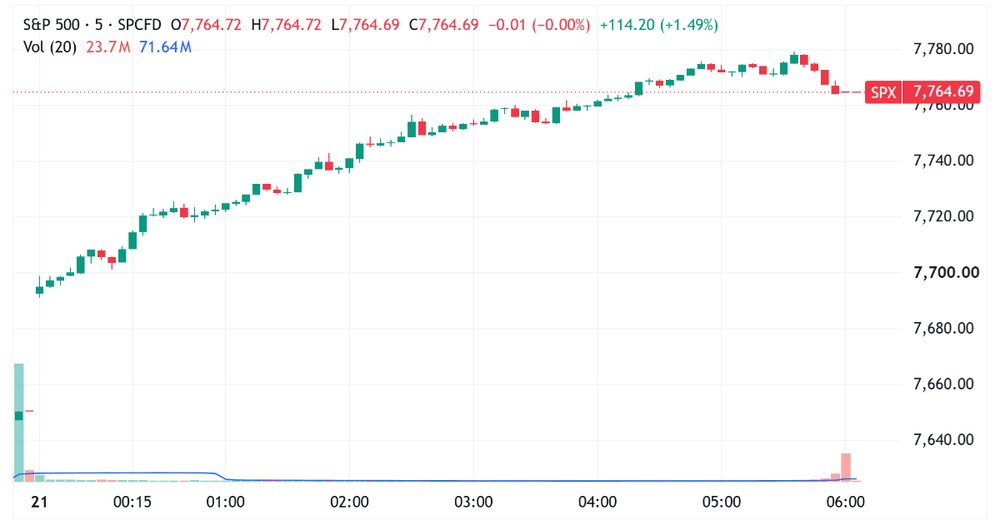
S&P 500 trended higher to close near best levels (Source: TradingView)
Overnight Markets
Major US benchmarks closed sharply higher and near best levels
Semis and AI-related stocks drove the bulk of the move, with the Philadelphia Semiconductor Index up 4.2%
Breadth was actually quite poor, with four sectors lower and the Equal-weight S&P 500 underperforming the cap-weighted index by 111 bps
Treasury 10-year yields fell back below 5% as traders trimmed bets on further Federal Reserve rate hikes, with global borrowing costs easing after last week's run of central bank decisions (CNBC)
SoftBank launched a bond sale of more than $11bn, splitting $10bn of dollar notes across three tenors and €1bn across two, in one of the largest junk bond deals on record (BBG)
Emerging market equities gained 1.1% on the MSCI developing-nation gauge, the highest in more than a week, led by Samsung Electronics, TSMC and MediaTek after the US-China talks (BBG)
Smart ring maker Oura filed to raise up to $2.2bn, offering 50 million shares at $40 to $44 for a valuation of up to $14.1bn, listing under the ticker OURA (YF)
Bloomberg's desk view was that clarity beats dovishness, arguing the Fed restored credibility last week but oil and AI risks are stopping investors committing fully (BBG)
Stocks
Advanced Micro Devices closed above a $1trn market value for the first time, hitting an intraday record of $613.92 as investors piled into server CPU suppliers on the Meta Muse demand read-through (BBG)
Meta Platforms rose almost 12% in afternoon trade, its best session in more than a year, as early traction for its Muse AI agent drew upgrades ahead of Wednesday's Connect event (CNBC)
Qualcomm added more than 9% and Arm Holdings also rallied, both caught in the same rotation into processor names levered to agentic AI workloads (CNBC)
Rare earth miners ripped higher after Trump's US-Denmark-Greenland security deal, with Critical Metals up 37%, USA Rare Earth up about 10% and MP Materials up roughly 6% (CNBC)
HP fell more than 3% after declining to detail its fiscal 2027 outlook, telling the SEC it assumes industry-wide PC unit volumes fall by mid-single digits in percentage terms next calendar year (CNBC)
The Roundhill Magnificent Seven ETF hit an intraday record of $71.74, a second straight session at an all-time high and the first such back-to-back run since the fund launched in April 2023 (CNBC)
Iran & Energy
Trump said he would "probably be open" to meeting Iranian President Masoud Pezeshkian at the UN General Assembly, while warning that "very big things" could happen in the conflict (CNBC)
Iran's military warned of "painful" retaliation across the Middle East against any new large-scale strike, saying regional countries backing such action would be treated as parties to the conflict (CNBC)
Pezeshkian leads Iran's delegation to the UNGA, addressing the assembly Wednesday after Trump speaks Tuesday, with the State Department confining the Iranian party to a six-block radius of UN headquarters (CNBC)
Trump decided against striking Iran-allied Houthis for now despite requests from Saudi Arabia, administration officials told the New York Times, another de-escalation signal traders seized on (CNBC)
Saudi Arabia issued air-raid alerts for Riyadh over the weekend, the first in the capital since the height of the war in March and April, plus warnings for Red Sea hubs including Yanbu (BBG)
CENTCOM chief Admiral Brad Cooper said oil and LNG shipments through the Strait of Hormuz over the past fortnight reached their highest level in six months (TE)
Reuters analysis found the global diesel shortage is unlikely to ease before next year, with wars in Iran and Ukraine stranding millions of barrels a day and draining inventories to historic lows (BBG)
Tariffs & Trade
Scott Bessent called his New York talks with Chinese Vice Premier He Lifeng "very successful", confirming both sides agreed to establish a bilateral US-China dialogue on AI risk (CNBC)
The US proposed an AI incident notification mechanism covering events that rise to a national security level, framed by Bessent as moving the two leading AI powers from opacity toward transparency (YF)
USTR Jamieson Greer said the two countries have "operationalised" the US-China Board of Trade, a standing channel intended to smooth negotiations ahead of Thursday's leaders' summit (CNBC)
The tariff truce expires on 10 November. It caps US tariffs on Chinese goods near 20% and carries Chinese commitments on rare-earth exports and US agricultural purchases (CNBC)
Washington has been rebuilding tariff authority post-Supreme Court, restoring a 12.5% levy on Chinese goods over forced labour and finalising a separate Section 301 probe into industrial overcapacity (CNBC)
Chicago wheat futures jumped as much as 2%, the biggest intraday gain in almost two weeks, with corn also higher as traders read the weekend talks as improving odds of renewed Chinese buying (BBG)
Central Banks
Traders pared Fed tightening bets as oil fell, after last week's unanimous 12-0 vote lifted the funds target range 25bp to 3.75% to 4.00%, the first hike since July 2023 (BBG)
Economy
The EIA forecasts US distillate inventories below 100 million barrels in September, staying under the five-year low through the end of 2026 and most of 2027 (BBG)
Japan was closed for a public holiday and remains shut Tuesday and Wednesday, thinning Asian liquidity in the first half of the week after Friday's Bank of Japan hike (IC)
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Uranium | 42.98 | +3.19% |
| Strategic Metals | 70.27 | +1.75% |
| Lithium & Battery Tech | 70.83 | +0.47% |
| Copper Miners | 87.49 | +0.24% |
| Steel | 106.08 | -0.01% |
| Gold Miners | 94.43 | -1.10% |
| Silver Miners | 93.76 | -1.51% |
Industrials | ||
| Global Jets | 29.01 | +2.80% |
| Agriculture | 28.68 | +1.88% |
| Construction | 92.6158 | +1.17% |
| Aerospace & Defense | 216.14 | +1.08% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 207.16 | +1.27% |
Renewables | ||
| Solar | 46.71 | +2.30% |
| Hydrogen | 45.03 | -0.24% |
Technology | ||
| Semiconductor | 559.34 | +4.93% |
| Cloud Computing | 28.93 | +3.99% |
| Cybersecurity | 45.97 | +3.68% |
| Data Center & Digital Infrastructure | 28.69 | +2.32% |
| Electric Vehicles | 34.2419 | +2.22% |
| Robotics & AI | 35.82 | +2.02% |
| FinTech | 25.9924 | +0.96% |
ASX Today
It's crickets out there!
What To Watch Today
Can we catch some upside too? Another very strong overnight session, though not much of it is ours to capture, with the rally again concentrated in AI hardware and semis. The Dow (+0.71%) finished a little higher and the equal-weight S&P 500 (+0.18%) was barely positive. The better news is the all-important oil price, finally heading our way. Brent is down almost 8% across the last four sessions to US$100 a barrel, taking the US 10-year yield with it, now 4.95%.
Airlines and software up, miners lag: Strong gains for the US Jets ETF (+2.8%) and iShares Expanded Tech-Software ETF (+2.6%). Software is looking constructive and not far off year-to-date highs, but don't confuse that with strength in local tech, which has gone the other way, down ~18% since 25 August. Copper advanced another 1.1% and is now up 6.2% over five sessions, though the Global X Copper ETF managed just 0.2%. Most other resource-related ETFs finished rather soft, the exception being uranium (+3.1%).
Key Events
Stocks trading ex-dividend:
Tue 22 Sep: Fleetwood (FWD) – $0.095, Latitude Group Holdings (LFS) – $0.055, Southern Cross Electrical Engineering (SXE) – $0.075
Wed 23 Sep: Genesis Energy (GNE) – $0.063, IPD Group (IPG) – $0.079, St Barbara (SBM) – $0.05
Thu 24 Sep: Bisalloy Steel Group (BIS) – $0.13, Briscoe Group Australasia (BGP) – $0.081, PRL Global (PRG) – $0.03, Salter Brothers Emerging Companies (SB2) – $0.02, Wiseway Group (WWG) – $0.006
Fri 25 Sep: Teaminvest Private Group (TIP) – $0.015
Other ASX corporate actions today:
Dividends paid: Ashley Services Group (ASH), Beam Communications Holdings (BCC), Cogstate (CGS), Coles Group (COL), Deterra Royalties (DRR), GWR Group (GWR), HiTech Group Australia (HIT), IPH (IPH), Meridian Energy (MEZ), Michael Hill International (MHJ), MyState (MYS), Peet (PPC), Redox (RDX), Sigma Healthcare (SIG), Suncorp Group (SUN), Tabcorp Holdings (TAH)
Earnings: None
IPOs: Innovaero Technologies (INN) and Parbo Resources (PRB)
Economic calendar (AEST):
No major economic announcements.