In a nutshell:
Wall Street staged a broad relief rally as dip buyers returned to chipmakers after last week’s AI rout sent the Nasdaq into correction territory, even as Nvidia fell on a board probe into its CEO
Oil extended its slide on hopes of diplomatic progress in the US-Iran war as Trump hosted Qatar’s prime minister at the White House
Inflation is back in focus ahead of Tuesday’s US CPI print, with Fed’s Goolsbee calling for action and China’s factory-gate prices running at a four-year high
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,550 | +2.35% |
Dow Jones | 52,390 | +2.15% |
NASDAQ Comp | 25,253 | +2.74% |
Russell 2000 | 2,843 | +3.22% |
Global Indices | ||
 S&P/TSX | 36,446 | +1.84% |
 Shanghai Composite | 3,661 | +0.32% |
 DAX | 26,267 | +1.73% |
 Hang Seng | 24,449 | -0.13% |
 Nifty 50 | 81,107 | +0.13% |
 Nikkei 225 | 58,776 | +2.33% |
 FTSE 100 | 10,783 | +1.02% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,142.38 | +1.77% |
 Copper | 6.36 | +2.27% |
 WTI Oil | 87.05 | -4.16% |
Currency | ||
 AUD/USD | 0.6928 | +0.90% |
Cryptocurrency | ||
 Bitcoin (USD) | 74,864 | +1.11% |
 Ethereum (AUD) | 3,072 | -4.26% |
Miscellaneous | ||
US 10 Yr T-bond | 4.864 | +0.10% |
VIX | 19.99 | -22.04% |
US Sectors
Sector | % Chg |
|---|---|
| Industrials | +3.78% |
| Consumer Discretionary | +3.05% |
| Information Technology | +2.87% |
| Materials | +2.15% |
| Communication Services | +2.12% |
| Health Care | +1.94% |
Sector | % Chg |
|---|---|
| Real Estate | +1.60% |
| Utilities | +1.54% |
| Financials | +1.42% |
| Consumer Staples | +0.64% |
| Energy | +0.41% |
S&P 500 Session Chart
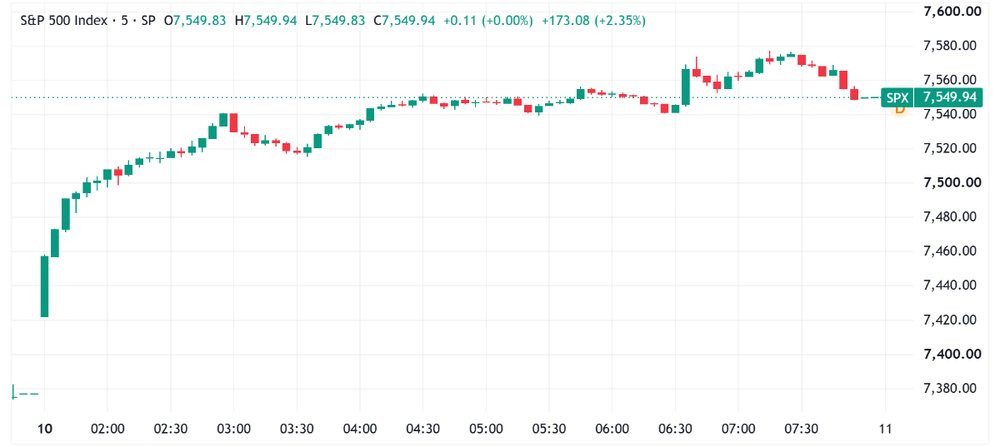
S&P 500 gaps up, trends higher and closes near best levels (Source: TradingView)
Overnight Markets
Major US benchmarks higher, opened firmly and extended gains through the session as dip buyers returned after last week’s AI-led selloff, with the Nasdaq recording its best day since April
Market breadth was strong, with more than three stocks gaining for every one that fell and consumer staples the only S&P 500 sector to slip
Copper rose to US$6.30/lb, bouncing from a 17-week low hit during last week’s tech-led selloff
Chip stocks led the rebound, with the iShares Semiconductor ETF up more than 7% after dropping around 13% last week, while Broadcom rose 9% (CNBC)
Citi cut US equities and global tech to neutral from overweight and upgraded European stocks ex-UK to overweight, warning Nasdaq positioning could reset into net-short territory, says Citi’s Manthey (YF)
Goldman sees the 10-year yield settling into a 4.75-5.0% range if risk-asset volatility eases and energy price relief holds, says Goldman’s Marshall (CNBC)
Gulf M&A slumped to about US$5bn in the third quarter, the lowest since 2022 and down from US$69bn a year earlier, as the Iran war stalls Middle East dealmaking (BBG)
Stocks
Nvidia fell 4.2% but well-off session lows of (8.7%) after its board launched an independent investigation into CEO Jensen Huang over reports he was targeted by a foreign intelligence effort, with the board saying it has no reason to believe national security or company secrets were compromised (CNBC)
AMD jumped 13% after Oppenheimer’s Rick Schafer upgraded the chipmaker to Outperform from Perform with a US$600 price target, forecasting data centre revenue growth of 135% in 2027 (YF)
Tesla climbed 5.5% as Magnificent Seven names outside Nvidia joined the tech rebound, with Amazon up 3% and Alphabet up ~1% (CNBC)
Geopolitics
Brent crude down ~5% to trade below US$93 a barrel on hopes of a diplomatic breakthrough to end the US war in Iran following the Democratic midterm sweep (BBG)
Trump hosted Qatar’s prime minister at the White House to discuss a new ceasefire and resuming nuclear talks with Iran, with Doha pushing for more time for diplomacy (AX)
Congressional Democrats weigh using the 11 December shutdown deadline to pressure Trump to end the Iran war, which could trigger the fourth shutdown of his second term (BBG)
Rubio plays down chances of an Iran breakthrough, saying Tehran’s demands are unacceptable and unrealistic, ahead of Trump’s White House talks with Qatar’s prime minister (BBG)
Tariffs & Trade
US populism is turning against tariffs after the midterms, with a new breed of Democratic economic populists focused on cost of living rather than protectionism, says Bloomberg’s Donnan (BBG)
Central Banks
Fed’s Goolsbee says policymakers must come to terms with the inflation failure in the Fed’s mandate, flagging the risk of overheating from the AI buildout (BBG)
Economy
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Uranium | 34.34 | +6.18% |
| Copper Miners | 75.255 | +5.62% |
| Silver Miners | 83.47 | +5.18% |
| Gold Miners | 91.39 | +4.33% |
| Strategic Metals | 53.52 | +4.12% |
| Steel | 99.6 | +3.43% |
| Lithium & Battery Tech | 61.22 | +0.51% |
Industrials | ||
| Construction | 90.22 | +5.14% |
| Global Jets | 30.195 | +5.14% |
| Aerospace & Defense | 71.67 | +3.90% |
| Agriculture | 26.09 | -0.08% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 219.57 | +2.78% |
Renewables | ||
| Hydrogen | 34.3497 | +4.47% |
| Solar | 45.17 | -0.90% |
Technology | ||
| Semiconductor | 146.76 | +7.49% |
| Cybersecurity | 45.56 | +4.59% |
| Electric Vehicles | 29.4488 | +3.33% |
| Robotics & AI | 31.88 | +2.67% |
| Data Center & Digital Infrastructure | 25.44 | +2.29% |
| FinTech | 24.54 | +1.32% |
| Cloud Computing | 26.15 | +1.16% |
ASX Today
Life360 delivers Q3 revenue of US$174.1m, up 40%, and adj EBITDA up 41% to US$34.6m, with a third-quarter record 188,000 net new Paying Circles. Lifts and narrows FY26 revenue guidance to US$665-681m from US$650-685m, adj EBITDA to US$132-138m (360)
Monadelphous guides 1H27 revenue of approximately $1.7bn and NPAT of $80-85m, helped by $830m of new contracts since 1 July and a full six months of Kerman. Flags moderating activity in 2H27 as work currently under way completes (MND)
OFX Group posts 1H27 revenue down 15.5% to $92.2m and underlying EBITDA down 72.4% to $4.0m. A late-half cost-out program worth around $10m in 2H27 underpins a targeted return to underlying profit, while non-exclusive talks with Equals continue (OFX)
Superloop guides FY27 underlying EBITDA of $148-156m, up 21-27% on FY26’s $122.7m and including around $11m from Lynham. Added 18.5k customers to 954k in the four months to 31 October, with Consumer growth holding through the Q1 price rise (SLC)
Virgin Australia reaffirms its outlook in a market update, with 1H27 underlying EBIT still expected to be broadly in line with the pcp. Points to strong customer demand, particularly event-related travel, plus disciplined capacity management and Transformation Program benefits (VGN)
Vulcan Energy mobilises a second in-house drill rig to Trappelberg, the fourth well site at its Lionheart project in Germany, accelerating the 28-well program. Has spent around €51m ($82m) on the two rigs to keep control of timelines, with first production targeted in 2H28 (VUL)
What To Watch Today
Risk on? The overnight session looked a lot like our Monday, though participation was far broader and defensives lagged by a wider margin. A ~5% dip in oil, a 0.5% pullback in the US Dollar Index and an oversold Nasdaq drove a strong bid for industrials, retailers, tech, miners, biotech and financials, while the high-flying defensives like real estate, utilities, telcos and staples lagged. Commodities caught the same bid, with copper up 1.9% to US$6.45/lb and gold up 1.6% to US$4,136/oz. Our overnight ETF watchlist was all growth and cyclicals: Uranium, Copper Miners, Silver Miners, Airlines and Nickel all up 5-6%, Gold Miners and Rare Earths/Strategic Metals up ~4.5%, Homebuilders up 3.4% and Biotech up 3.0%. But most resource-related sectors are only just making the turn after a 20-30% selloff since late August, and we’ve had plenty of decent one-day rallies along the way, each one met with more downside. The good thing is the rally is broadening, with airlines, homebuilders, retailers and REITs all performing well in recent weeks. The miners still need to show more of the good stuff (accumulation, a push through key overhead areas, higher highs and higher lows).
Key Events
Stocks trading ex-dividend:
Tue 10 Nov: None
Wed 11 Nov: None
Thu 12 Nov: Dominion Income Trust 1 (DN1) – $0.687
Fri 13 Nov: None
Other ASX corporate actions today:
Economic calendar (AEDT):
10:30 am: Australia Consumer Confidence
11:30 am: Australia Business Confidence
2:00 pm: China Balance of Trade
12:30 am: US Inflation