In a nutshell:
Major US benchmarks finished lower but off worst levels, as an early advance unwound during Fed Chair Kevin Warsh's press conference
The Fed raised rates 25bp in a unanimous vote, its first increase since 2023, with most members penciling in another quarter point before year end
US 2-year yield surged 6 bps to 4.73%, now up just shy of 40 bps in the last two weeks, while the 30-year finished flattish
Brent slipped to US$105 a barrel on a surprise industry inventory build and signs Saudi Arabia's East-West pipeline could restart within days
Let's dive in.
Overnight Summary
Name | Value | % Chg |
|---|---|---|
Major Indices | ||
 S&P 500 | 7,552 | -0.45% |
Dow Jones | 51,462 | -1.21% |
NASDAQ Comp | 25,978 | -0.01% |
Russell 2000 | 2,859 | -0.40% |
Global Indices | ||
 S&P/TSX | 35,491 | -0.26% |
 Shanghai Composite | 3,892 | +0.71% |
 DAX | 25,538 | +0.53% |
 Hang Seng | 24,714 | +0.19% |
 Nifty 50 | 74,336 | +0.45% |
 Nikkei 225 | 63,923 | +0.69% |
 FTSE 100 | 10,688 | +0.28% |
Name | Value | % Chg |
|---|---|---|
Commodities (USD) | ||
 Gold | 4,264.21 | -0.65% |
 Copper | 6.36 | -0.09% |
 WTI Oil | 102.43 | -3.21% |
Currency | ||
 AUD/USD | 0.7086 | -0.03% |
Cryptocurrency | ||
 Bitcoin (USD) | 75,666 | +0.07% |
 Ethereum (AUD) | 3,375 | -0.03% |
Miscellaneous | ||
US 10 Yr T-bond | 5.006 | +0.20% |
VIX | 17.71 | +2.97% |
US Sectors
Sector | % Chg |
|---|---|
| Information Technology | +0.10% |
| Health Care | +0.04% |
| Utilities | +0.01% |
| Industrials | -0.12% |
| Consumer Staples | -0.53% |
| Communication Services | -0.62% |
Sector | % Chg |
|---|---|
| Real Estate | -0.67% |
| Consumer Discretionary | -0.68% |
| Materials | -0.73% |
| Financials | -1.62% |
| Energy | -2.97% |
S&P 500 Session Chart
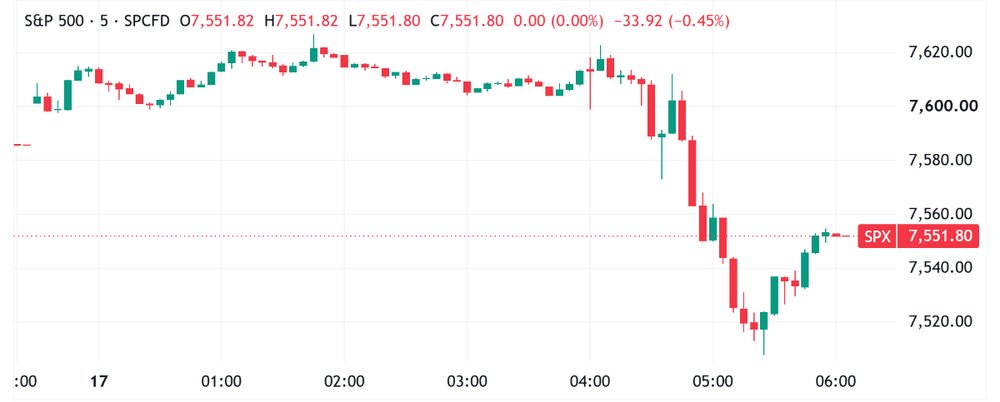
S&P 500 traded rangebound after small early gains before falling during Fed press conference (Source: Trading View)
Overnight Markets
Major US benchmarks finished lower and slightly off worst levels, extending a three-day losing streak
US 10-year yield held the 5.0% mark while the 2-year rose 6 bps to 4.73% as markets price in a more hawkish near-term rate outlook
The US Dollar Index climbed as much as 0.7% to its highest since late July, a third day of gains for the greenback, after policymakers signalled a further increase this year
Money markets moved to price roughly a 50% chance of a follow-up Fed hike in October
Bond traders had built heavily bearish positions into the meeting, betting the selloff that lifted the 10-year to its highest since 2007 on Tuesday would extend (BBG)
Wall Street drove equities toward their lowest since July on bets the Fed keeps tightening, with every major S&P 500 group falling, short-dated Treasuries underperforming and the dollar climbing (BBG)
Yardeni Research cut its year-end S&P 500 target to 7,900 from 8,400, pointing to higher Treasury yields driven by rising energy prices and a greater risk of a downturn (CNBC)
Bitcoin slid below $76,000 after the Senate blocked the Clarity Act from advancing in a 49 to 50 cloture vote, dragging Coinbase and Robinhood lower (YF)
The Kobeissi Letter found the S&P 500 has fallen an average 4.0% in the six weeks after the first hike of a cycle across seven episodes since 1988, then recovered, averaging a 9.0% gain after 12 months (YF)
Macro Risk Advisors argued this week that a tightening cycle could trigger a 10% S&P 500 correction as higher costs compress corporate margins (BBG)
The Fed Hike
The FOMC voted unanimously to lift the federal funds target range by 25 basis points to 3.75% to 4%, the first policy move of Warsh's chairmanship and a reversal of the cut delivered last December (AX)
The dot plot showed 12 of the 18 members who submitted projections put appropriate 2026 policy at an average 4.125%, four pencilled in a further 50 basis points and only two judged the new range adequate (YF)
Warsh told reporters the summer inflation readings did not show underlying trends had meaningfully improved, and that the committee's standard for confidence on inflation had not been satisfied (Axios)
Warsh again declined to submit his own rate projection, consistent with his long-standing objection to forward guidance (YF)
Investors had priced better than 90% odds of a quarter point move by Tuesday and were already carrying another hike by year end, in a decision Bloomberg framed as defiance of Trump (BBG)
Trump posted on Truth Social on 4 September demanding lower rates and threatening to halt trade with countries running surpluses against the US (YF)
Stocks
J.B. Hunt Transport Services tumbled about 13% after a rare intra-quarter warning that third quarter earnings could fall 5% to 10% against the June quarter, blamed on internal adjustments for rising purchase transportation rates (CNBC)
Intel climbed on reports it is in talks with SK Hynix to produce memory silicon wafers in the US, with the Korean group saying it is weighing options and has finalised nothing (YF)
SpaceX advanced 5% after setting 22 September for Starship Flight 14, which the company says will be the first attempt to put the vehicle into orbit around Earth (YF)
AI infrastructure names rebounded after several losing sessions, with CoreWeave up more than 4%, Nebius nearly 3%, Lumentum 9.5%, Coherent 7% and Dell 3.6% (CNBC)
Energy producers fell after a report showed US inventories rose last week, with Diamondback Energy down 8%, Occidental Petroleum off 5%, Devon Energy down 4% and ExxonMobil nearly 3% lower (CNBC)
Geopolitics
Saudi warplanes struck targets across Yemen on Wednesday as Houthi fighters consolidated a rapid advance that has extended Tehran's reach and further disrupted global oil supply (RT)
Riyadh said its air defences downed a Houthi drone south of Mecca before it entered restricted airspace, calling the holy city a red line, a claim the Houthis rejected (RT)
Regional officials expect the 1,200km pipeline to stay largely shut for weeks while it is repaired, taking several million barrels a day off the market (ABC)
Crown Prince Mohammed bin Salman met Egyptian President in Cairo, with both affirming a commitment to freedom and security of navigation in the Red Sea and Bab el-Mandeb (ABC)
Iran has said it will not reopen Hormuz until Washington meets its conditions, and an Iran and Gulf states meeting in Salalah was postponed after the pipeline attack (CNBC)
Central Banks
All 65 economists in a Reuters poll expect the Bank of England to leave Bank Rate at 3.75% on Thursday, with a sharp rise in global bond yields already tightening financial conditions (RT)
The UAE, Saudi and Qatari central banks all raised rates 25 basis points shortly after the Fed decision, tracking the US move because their currencies are pegged to the dollar (RT)
The Bank of Japan is expected to raise rates a quarter point on Friday, its first move in three months, which would take the policy rate to a 31-year high (YF)
The RBA expected to hold at 4.35% into its 29 September decision, with NAB forecasting a 25bp rise to 4.6% this month and ANZ, CBA and Westpac all expecting a move by November (Aussie)
Economy
US retail sales rose 1.2% month-on-month in August to $773.9bn against ests of 0.9%, with sales excluding autos, auto parts and petrol also up 1.2% and nearly all categories higher (YF)
US inflation held at 3.4% year-on-year in August, with petrol up 3.9% for the month and the broader energy index up 2.1%, while core prices rose 2.4% year-on-year (RT)
Median US household income rose to a record even as Americans continued to report an affordability squeeze (YF)
The University of Michigan's preliminary September consumer sentiment reading deteriorated for a second consecutive month on inflation worries and high petrol prices (YF)
Industry ETFs
Name | Value | % Chg |
|---|---|---|
Commodities | ||
| Lithium & Battery Tech | 69.85 | -0.24% |
| Steel | 106.188 | -0.37% |
| Copper Miners | 84.19 | -0.47% |
| Uranium | 41.37 | -0.96% |
| Strategic Metals | 67.61 | -1.01% |
| Gold Miners | 92.8 | -1.41% |
| Silver Miners | 90.93 | -1.92% |
Industrials | ||
| Aerospace & Defense | 215.27 | +0.59% |
| Agriculture | 28.82 | -0.21% |
| Global Jets | 27.8 | -0.29% |
| Construction | 91.69 | -0.32% |
Name | Value | % Chg |
|---|---|---|
Healthcare | ||
| Biotechnology | 202.4 | +0.20% |
Renewables | ||
| Hydrogen | 43.863 | +0.81% |
| Solar | 44.62 | -1.04% |
Technology | ||
| Semiconductor | 502.06 | +0.64% |
| Data Center & Digital Infrastructure | 27.28 | +0.52% |
| Robotics & AI | 34.72 | +0.26% |
| Electric Vehicles | 33.035 | -0.57% |
| Cloud Computing | 28.02 | -0.60% |
| Cybersecurity | 44.95 | -0.77% |
| FinTech | 25.15 | -2.06% |
ASX Today
New Zealand King Salmon upgrades FY26 guidance to pro-forma EBITDA of $36-39 million from $30-34 million, with harvest volume unchanged at 5,950-6,050Mt. CEO Carrington attributed the upgrade to fish performance, with mortality below expectations. Feed price and wellboat cost pressures emerging in FY26 are expected to land in FY27, with FY27 guidance due at the November results (NZK)
Contact Energy's August operating report shows mass market electricity and gas sales of 550GWh, up from 454GWh a year earlier, with netback steady at $148.57/MWh. Unit generation cost fell to $40.90/MWh from $57.52/MWh on higher hydro output and minimal thermal running (CEN)
What To Watch Today
Rates up, stocks down: The Fed decision, forecasts and press conference drove another sizeable lift in short-term rate expectations, pushing the US 2-year further up its vertical ascent to 4.73%, the highest since July 2024. A bounce in AI names buoyed the S&P 500 tech sector and classic defensives like healthcare and utilities scraped above breakeven, but rate-sensitive sectors like real estate, discretionary and financials traded lower. Resources tanked. Copper faded a 1.0% gain to finish the overnight session 0.2% lower at US$6.45/lb, while gold surrendered a 1.7% intraday rise to close 0.7% down. It was much the same fade across our overnight ETF watchlist, where most names gained 1-2% in early trade before finishing lower.
Key Events
Stocks trading ex-dividend:
Thu 17 Sep: a2 Milk Company (A2M) – $0.067, EDU Holdings (EDU) – $0.03, Embelton (EMB) – $0.20, Flight Centre Travel Group (FLT) – $0.30, Lycopodium (LYL) – $0.37, SKS Technologies Group (SKS) – $0.065, Solaris Australian Equity Income Plus (SET) – $0.005, South32 (S32) – $0.075, Supply Network (SNL) – $0.44, Tourism Holdings Rentals (THL) – $0.063, WAM Income Maximiser (WMX) – $0.007, West African Resources (WAF) – $0.20
Fri 18 Sep: Adrad (AHL) – $0.026, Centrepoint Alliance (CAF) – $0.018, Macmahon (MAH) – $0.013, Vita Life Sciences (VLS) – $0.05
Mon 21 Sep: Cochlear (COH) – $1.30, New Hope Corporation (NHC) – $0.30
Tue 22 Sep: Fleetwood (FWD) – $0.095, Latitude Group Holdings (LFS) – $0.055, Southern Cross Electrical Engineering (SXE) – $0.075
Wed 23 Sep: Genesis Energy (GNE) – $0.063, IPD Group (IPG) – $0.079, St Barbara (SBM) – $0.05
Other ASX corporate actions today:
Dividends paid: Ansell (ANN), Challenger (CGF), Dalrymple Bay Infrastructure (DBI), Ingenia Communities Group (INA), Jumbo Interactive (JIN), Maxiparts (MXI), Mayfield Group Holdings (MYG), Mitchell Services (MSV), oOh media (OML), Shaver Shop Group (SSG), Sonic Healthcare (SHL)
Earnings: Bannerman Energy (BMN), NuEnergy Gas (NGY), Orion Minerals (ORN), Sheffield Resources (SFX), Tungsten Mining (TGN), Wildcat Resources (WC8)
IPOs: None
AGMs: None
Economic calendar (AEST):
9:00 pm: Bank of England rate decision