ASX data centre stocks crack as Firmus and AirTrunk listings stall
Firmus pulled its float, AirTrunk hit pause and ASX data centre contractors cracked. Is this a pullback worth watching?
Source: Gemini
Mentioned
KEY POINTS
- The basket slid after Firmus cancelled its IPO and AirTrunk delayed its REIT listing to early 2027, before a 3 pm sell-off sent SKS down 20.5% on Tuesday.
- Earnings have surged on the data centre buildout but valuations ran harder. SKS’ trailing P/E climbed from about 25x at the start of 2026 to roughly 40x at its peak.
- FY27 guidance still points to strong growth, with GenusPlus guiding to EBITDA roughly doubling and Tasmea flagging 76% underlying NPATA growth at the midpoint.
Engineering and electrical contractors have spent the past 12–24 months riding Australia’s data centre buildout, but two stalled IPOs in the space of a week have shown how little room the sector had left for disappointment.
A basket of names, including SKS Technologies and Southern Cross Electrical Engineering, have been hit by extreme volatility over the past week, culminating in an unprecedented move in the last hour of trade on Tuesday.
Ticker | Company | % Chg (13-Oct) | Price | 1 Month | YTD |
|---|---|---|---|---|---|
SKS | SKS Technologies Group | -20.5% | $6.89 | -13.5% | 71.8% |
SXE | Southern Cross Electrical Engineering | -8.8% | $4.55 | 4.8% | 81.2% |
MGH | MAAS Group Holdings | -6.6% | $3.67 | -37.8% | -32.4% |
TEA | Tasmea | -5.7% | $10.33 | 5.5% | 144.7% |
NWH | NRW Holdings | -4.7% | $7.29 | -5.0% | 45.8% |
SRG | SRG Global | -4.1% | $3.74 | -1.8% | 25.5% |
SYL | Symal Group | -3.7% | $2.60 | -1.8% | -25.7% |
GNP | GenusPlus Group | -2.9% | $9.02 | 7.5% | 42.0% |
GNG | GR Engineering Services | -2.8% | $7.72 | 15.4% | 73.8% |
Data as at close, Tuesday 13 October 2026
Below, we take a look at the sequence of events and where to from here.
The backdrop
The data centre buildout has driven some extraordinary earnings growth for these ‘pick-and-shovel’ plays, with most names up north of 50% year-to-date (at least prior to last week).
A name like SKS went all-in on what was then a nascent data centre industry back in 2021–22, and since FY22 its revenue and NPAT have grown at a CAGR of 50.8% and 73.1% respectively. A more established name like Southern Cross Electrical Engineering has had its revenue mix reshaped by the same work. Infrastructure now makes up 50% of FY26 revenue ($360m of $719m), up from just 18.8% in FY22 ($104m of $553m).
While earnings have grown massively, valuations have re-rated even more. SKS traded on a trailing price-to-earnings ratio of about 25x at the start of the year and peaked at roughly 40x a week ago.
So what you’re left with is a strongly trending sector trading at elevated multiples, but one that’s exposed to anything that tempers growth expectations (this probably sounds very familiar).
The Firmus IPO
With most names sitting around record territory, the first major catalyst for a sharp pullback was arguably the failed Firmus IPO. Here’s a brief sequence of events:
On Monday 5 October, joint lead managers JPMorgan, Bank of America and Morgan Stanley told fund managers that early interest was “well in excess” of the $7.9bn raise at $11 a share
By Wednesday 7 October, major US institutions and key cornerstone backers, including San Francisco’s Coatue Management, had cut or pulled their orders
On the morning of Thursday 8 October, the book closed well short of its target, with bankers cutting the price to $9, then $8.25, before floating a $5.50 option at half the original price
That afternoon, Firmus removed its prospectus and investor documents from the data room and withdrew from a federal parliamentary inquiry into AI
On Friday 9 October, the board formally cancelled the IPO, citing market volatility
The basket started to slip on Monday and Tuesday, and the slashing of the offer price on Thursday drove a broad selloff, with SKS down 10.1%, Southern Cross down 6.8%, NRW down 4.0% and GenusPlus down 3.0%. Most names extended their losses on Friday.
AirTrunk pushes listing back to 2027
On Tuesday, AirTrunk reportedly pushed its Singapore REIT listing back to early 2027, citing:
A sell-off in chipmaker shares and AI-linked tech stocks dragged on Asian equities and cut investors’ appetite for risk
Rising bond yields and uncertainty over US Federal Reserve rate hikes left investors demanding higher returns. AirTrunk considered lifting the REIT’s projected dividend yield to 6% from 5.5% before opting to pause
A tougher market for large AI and data centre equity raisings, with Firmus scrapping its proposed IPO and Philippine telco PLDT deferring its own data centre REIT listing
So now we've got Firmus out, AirTrunk delayed and to make matters worse, South Korea’s KOSPI tumbled 5.5% on Tuesday after Broadcom CEO Hock Tan compared current market sentiment to a casino, and on reports that China’s ChangXin Memory Technologies (CXMT) had made technical advances that could increasingly challenge global memory leaders.
At around 3 pm AEDT, the engineering basket (along with a few tech/AI-related names like Megaport, Data#3 and Codan) started to sell off aggressively. It was as if a fund had just told its algos to dump positions at whatever the price. SKS went from trading around 3% lower to closing down 20.5%. Southern Cross flipped from a 2% gain to a 10% decline. It really felt like a flash crash across this sub-sector.
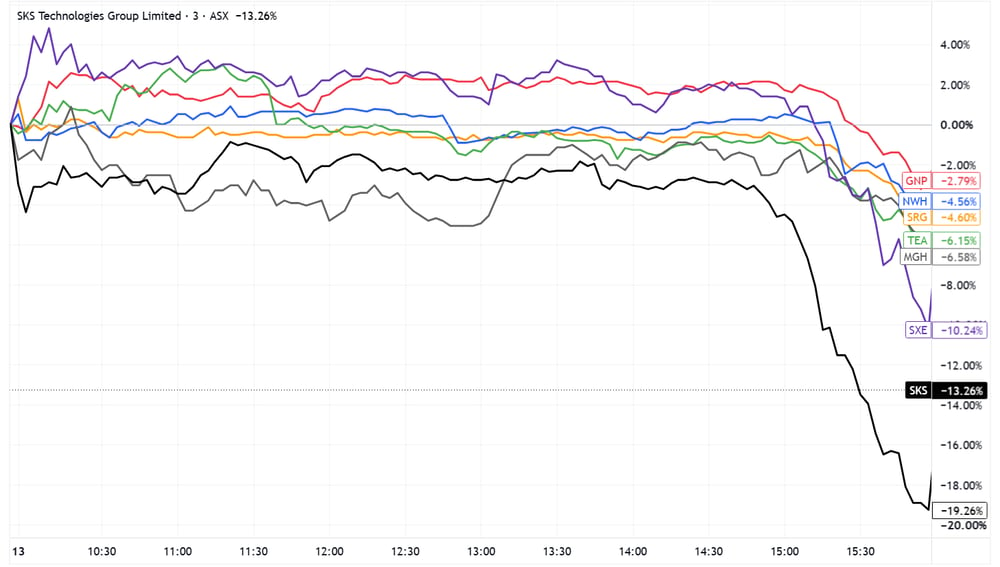
ASX-listed engineering basket, intraday chart as at Tuesday 13 October 2026 (Source: TradingView)
Where are we now?
The most battered names like SKS and Southern Cross are enjoying a sizeable bounce on Wednesday but remain down for the week. It’s worth noting that SKS’ declines were compounded by its founding Jinks family offloading 10 million shares (~30% of their holdings) at $10.60 a share last Wednesday, which sent the stock down 12.2%.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
SKS | SKS Technologies | 11.6% | $7.69 | -27.5% | 91.8% |
SXE | Southern Cross Electrical Engineering | 6.9% | $4.87 | -6.4% | 93.8% |
TEA | Tasmea | 3.6% | $10.70 | -7.0% | 153.6% |
GNP | Genusplus Group | 1.3% | $9.14 | -8.0% | 43.9% |
NWH | NRW | 0.9% | $7.36 | -9.0% | 47.1% |
SYL | Symal Group | 0.8% | $2.62 | -10.3% | -25.1% |
MGH | Maas Group | 0.5% | $3.69 | -45.3% | -32.0% |
GNG | GR Engineering Services | 0.1% | $7.73 | 3.1% | 74.1% |
SRG | SRG Global | -0.9% | $3.71 | -6.9% | 24.3% |
Data as at 1:15 pm AEDT, Wednesday 14 October 2026
There haven’t been any announcements addressing the recent volatility, aside from SKS’ response to an ASX price query this morning. The company said its work in hand and pipeline remain consistent with its 7 October announcement, adding that it “continues to maintain a strong pipeline of opportunities and remains actively engaged in converting those opportunities into secured work”.
The bottom line is that these stocks have had a euphoric run over the past 12–24 months, leaving them trading at historically expensive levels and due for a pullback. Bearish news piling up from Firmus, AirTrunk and the broader market finally took some heat out of the sector, first through a 3–4 day slide last week, then an aggressive, likely institutional selloff at 3 pm on Tuesday.
Valuations are expensive relative to history, but growth has also been supercharged by the data centre buildout. Recent developments have clearly hurt sentiment, but will they hit earnings too?
We’ll find out soon enough.
For now, most of these names have guided to strong growth in FY27, some of it organic and some bolstered by recent M&A.
Code | Guided metric | FY26 actual (A$m) | FY27 guidance range (A$m) | Implied growth on midpoint % |
|---|---|---|---|---|
GNG | Revenue | 493.2 | 825-850 | 69.8 |
NWH | Underlying EBITA | 288.6 | 320-330 | 12.6 |
SXE | Underlying EBITDA | 77 | at least 100 | 29.9 |
SRG | EBITDA | 170.1 | 195-205 | 17.6 |
TEA | Underlying NPATA | 73.7 | 128-132 | 76.4 |
GNP | EBITDA | 100.8 | 200-205 | 100.9 |
SKS | PBT | 39.35 | circa 60 | 52.5 |
Source: FY26 company results
So if you think nothing’s changed in either the near or medium term, perhaps this is a pullback worth watching.