ASX 200 Live Today - Wednesday, 24th June
The S&P/ASX 200 is flat as gains for tech, healthcare and defensives are offset by softness among miners and banks.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Wednesday, June 24. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
ASX 200 flattish, commodities tank, US futures slightly higher
[2:15 pm] That's all for today. The ASX 200 is currently up just 0.1%, after briefly rallying 0.4% after the CPI print.
Tech bounced after tumbling ~8% in the prior two sessions, while defensive pockets of the market like Healthcare, Staples and Utilities catch a bid. While only two sectors are trading lower, breadth is still pretty weak, with only 106 constituents (53%) trading higher.
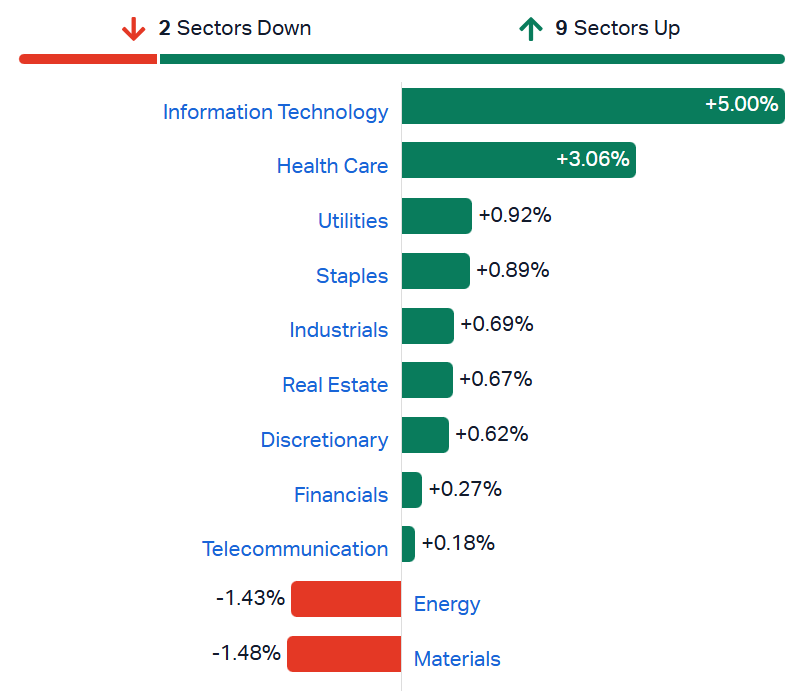
ASX 200 sectors (Source: Market Index)
Markets continue to walk a volatile path, where the prospect of higher rates is weighing on risk assets, while a rising US dollar compounds the hit to commodity markets.
Today's CPI print was relatively mixed, with the annual headline rate easing to 4.0% vs. 4.2% in April and well-below market expectations of 4.4%. Meanwhile, the RBA's preferred trimmed mean hit 3.6%, up from 3.4% a month ago and slightly above 3.5% consensus. Regardless, inflation is still too high. RBA rate expectations were mostly unchanged following the print, with ~8 bps of hikes priced for August and ~15 bps by year-end. We have ABS unemployment data and household spending data tomorrow, which will drive further rate volatility. Last month, the unemployment rate unexpectedly jumped to 4.5% (from 4.3%). A repeat could very well drive out rate hikes this year (or vice versa).
US dollar extends gains, commodities broadly lower
[1:18 pm] A rough day for commodities, with gold trading near fresh year-to-date lows and copper retreating to a six-week low.
Symbol | Chg% | Last (US$) |
|---|---|---|
Gold | -1.33% | 4,057.00 |
Brent | -1.21% | 76.06 |
Platinum | -1.17% | 1,632.70 |
Silver | -0.74% | 61.1452 |
Aluminum | -0.51% | 3,228.80 |
Copper | -0.35% | 6.16 |
Palladium | -0.15% | 1,225.68 |
US Dollar Index | 0.11% | 101.49 |
Tech stocks bounce
[12:23 pm] The ASX 200 Tech Index is up 4.5% after falling 8% in the prior two sessions. Heavyweights Wisetech and Xero are both sharply higher, bouncing off multi-year lows. From the below list, the average tech stock is flat for the week and down 7.6% year-to-date.
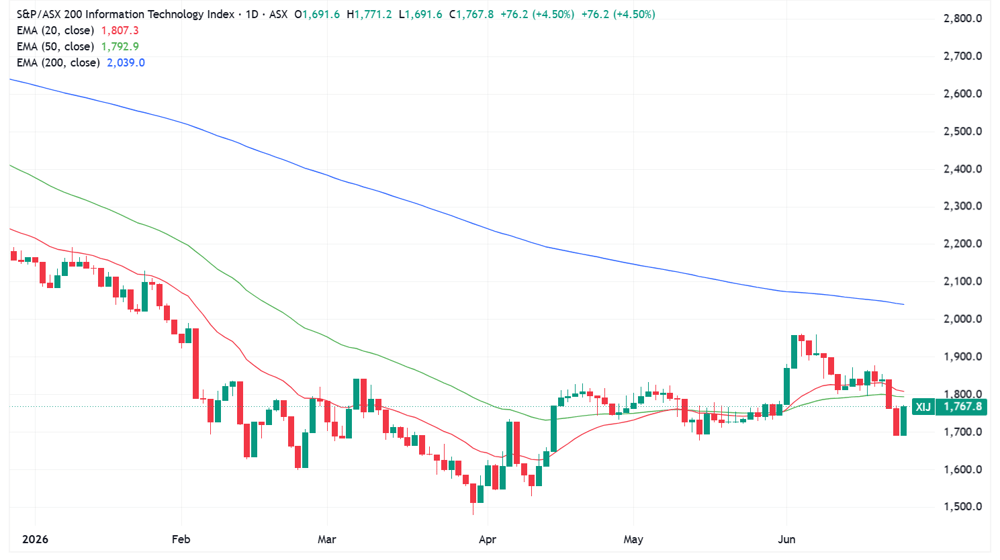
S&P/ASX 200 Tech Index daily chart (Source: TradingView)
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
WTC | Wisetech Global | 14.0% | $32.78 | -11.0% | -52.1% |
XRO | Xero | 8.1% | $70.29 | -1.8% | -38.3% |
PME | Pro Medicus | 3.2% | $178.39 | 9.4% | -19.2% |
NXT | NextDC | 2.5% | $14.90 | 0.8% | 21.0% |
HSN | Hansen Technologies | 2.4% | $4.29 | -3.4% | -18.8% |
CDA | Codan | 2.3% | $43.10 | 1.1% | 51.7% |
360 | Life360 | 1.9% | $22.76 | 1.1% | -29.4% |
NXL | Nuix | 1.7% | $1.19 | -11.9% | -34.5% |
OCL | Objective Corporation | 1.4% | $10.27 | -1.4% | -38.0% |
TNE | Technology One | 1.1% | $28.03 | -8.7% | 1.7% |
BVS | Bravura Solutions | 0.7% | $2.06 | 0.2% | -20.0% |
MP1 | Megaport | 0.6% | $20.39 | 6.8% | 79.7% |
MAQ | Macquarie Technology Group | 0.6% | $73.17 | -3.4% | 9.2% |
IRE | Iress | 0.6% | $6.04 | -2.8% | -28.0% |
DTL | Data#3 | 0.6% | $9.74 | -2.2% | 8.5% |
CAT | Catapult Sports | -0.4% | $2.76 | -8.9% | -33.7% |
DDR | Dicker Data | -0.5% | $12.17 | 2.7% | 18.2% |
SDR | Siteminder | -0.7% | $3.77 | -2.5% | -38.6% |
WBT | Weebit Nano | -0.7% | $8.34 | 14.2% | 66.8% |
DGT | Digico Infrastructure Reit | -2.7% | $2.31 | -7.8% | -17.4% |
PPS | Praemium | -3.6% | $0.66 | -8.3% | -17.0% |
AD8 | Audinate Group | -5.9% | $2.40 | 31.1% | -40.9% |
Baby Bunting tumbles 11% on earnings downgrade
[12:07 pm] Shares in Baby Bunting are down 10.9% after the company downgraded its FY26 guidance this morning.
Total sales of $553-555m vs. $571.2m ests (~3% miss)
Comparable store sales growth of around 3.5%, roughly half the prior guidance of 5-7%
Pro forma NPAT now seen at $16.0-17.0m, down ~11% on prior guidance of $17.5-19.5m and below $17m ests (3% miss at the midpoint)
CEO Mark Teperson said: “While trading softened through the fourth quarter, delivering pro forma NPAT growth of 32-40% for the full year and further gross margin expansion is a strong result in a difficult consumer environment. The three RBA cash rate rises in the second half, together with higher fuel prices, weighed on consumer spending and added to our distribution costs."
Xero rallies on UK price increases
[11:53 am] Xero shares are trading sharply higher after lifting prices across its mid to upper tier UK plans, with the entry-level Simple plan left unchanged.
Shares up 7.8% to $70.02, though it closed at the lowest since January 2023 on Tuesday
Plans like Ignite up £2 to £18/mo and Grow up £2 to £39/mo.
Comprehensive up £5 to £55/mo and Ultimate up £5 to £70/mo.
Simple plan unchanged at £7/mo.
Weighted average price increase broadly in line with last year.
Making Tax Digital Phase 3 expected to dilute blended ARPU via a Simple tier mix shift, with revenue impact from September and the full period effect in H2.
Company page: Xero (XRO)
Australian inflation eases to 4.0% in May but tops trimmed mean ests
[11:31 am] Headline CPI slowed in the year to May, though the closely watched underlying measure ticked higher and came in above expectations.
Headline inflation down 0.7% month-on-month vs. ests for a 0.3% fall
Headline inflation rose 4.0% year-on-year in May vs 4.4% ests and down from 4.2% in April.
Trimmed mean inflation rose 3.6% vs 3.5% ests and up from 3.4% in April.
Housing was the largest contributor at 6.5%, driven by electricity costs running 21.1% higher year-on-year as government rebates rolled off.
Food and non-alcoholic beverages inflation accelerated to 3.3% from 2.8% in April, led by a 4.0% rise in meals out and takeaway.
Transport inflation eased to 3.3% from 6.6% in April, with automotive fuel prices down 11.9% in the month on the fuel excise halving and lower world oil prices.
Source: ABS
Analysts' take on Centuria Capital
[11:29 am] Centuria Capital launched a fully underwritten equity raise on Tuesday, alongside an acceleration of its neocloud venture, ResetData, with management citing growth across both ResetData and the broader real estate funds management platform, though several brokers noted the timing capitalised on a sharp recent share price run driven by AI enthusiasm.
Macquarie downgraded to Underperform from Outperform, raised target from $1.78 to $1.88: flags stretched valuation, ResetData capital requirements likely exceeding the current raise, losses until at least the latter part of the decade, and a difficult core fundraising environment.
Bell Potter retained Hold, lowered target from $2.15 to $2.00: notes the specific use of proceeds remains unclear, trims earnings estimates across the forecast period, and flags extended AI factory deployment timelines alongside ongoing real estate redemption and credit risks.
Analysts' take on Viva Energy
[10:52 am] Viva Energy confirmed the restart of the Geelong Refinery's Residue Catalytic Cracking Unit on Tuesday, with production expected to return above 90% of normal capacity by week's end, though the Alkylation unit will remain offline throughout next calendar year as the company weighs repair versus replacement following a piping failure.
Analysts trimmed price targets on softer April and May refining margins and the structural drag from the Alkylation outage, while broadly maintaining ratings and citing business interruption insurance and the Fuel Security Services Payment mechanism as partial earnings support. The stock closed down 2.4% on the day.
JPMorgan retained Neutral, lowered target from $2.60 to $2.40: cites a material miss on April and May refining margins and an Alkylation outage persisting through next year, but views the structural improvement in the business as underestimated by the market, assuming around 80% insurance recovery.
Morgan Stanley retained Equal-weight, lowered target from $2.56 to $2.39: reflects lower margins and a valuation roll forward, with retail acquisitions adding scale but carrying execution, consumer sentiment, and social licence risks in the convenience segment.
RBC Capital Markets retained Outperform, lowered target from $2.70 to $2.60: notes the RCCU restart returns the refinery to the majority of normal capacity, a $5 per barrel cut to FY refining margin forecasts, and a need for alkylate imports next year, with regional crack spreads still elevated versus pre conflict levels.
ASX 200 edges higher
[10:23 am] ASX 200 trading fractionally higher after a four-day losing skid. The Tech index is looking deceptively strong as heavyweight Wisetech bounces ~8% after falling 22% in the previous two sessions. Despite nine sectors trading in positive territory, the index is struggling amid mixed moves for large caps. Notable laggards include Rio Tinto (-1.7%), Newmont (-1.4%), BHP (-0.6%), ANZ (-0.6%) and Westpac (-0.10%).
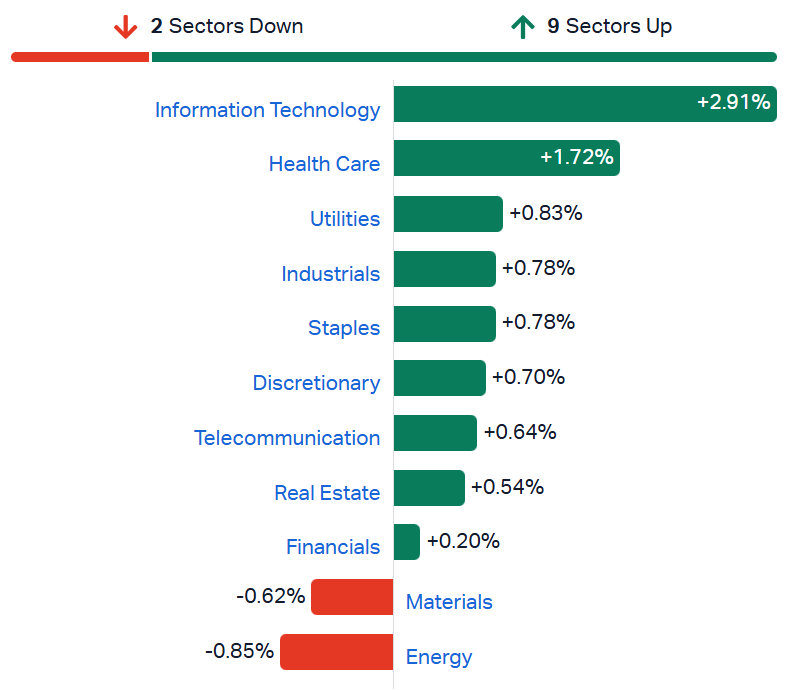
S&P/ASX 200 sectors (Source: Market Index)
China throttles rare earth and tungsten exports to Japan in targeted squeeze
[10:19 am] China has near-halted shipments of some tungsten and heavy rare earths to Japan, pressuring Tokyo for a diplomatic off-ramp without escalating enough to draw US pushback.
Exports of key intermediate tungsten forms, used in precision tools for car plants, fell to zero in January and have stayed there, hitting an auto sector worth around 10% of Japan's GDP.
Dysprosium and terbium shipments, used in high-performance EV magnets, have been at zero all year, with the last exports in October 2025 ahead of PM Takaichi's Taiwan remarks.
Yttrium exports, used in LED screens and semiconductor equipment, are running at just 1.13% of last year's volume.
Japanese processors including Sumitomo Electric and Mitsubishi Materials are offsetting curbs with scrap feedstock, with Mitsubishi now at about 70% recycled material and targeting 100% by 2030.
Diplomatic contact has stalled, with Japan's ambassador repeatedly denied meetings and Takaichi reluctant to meet Xi at the November APEC summit in Shenzhen.
Source: Bloomberg
Pimco backs emerging-market bonds as China's export glut caps inflation
[10:19 am] Pimco argues China's flood of cheap exports is helping contain inflation across developing economies, giving their central banks room to cut rates and supporting the case for emerging-market local debt.
China's surplus capacity acts as a structural source of global disinflation, with Beijing expected to keep expanding production faster than domestic demand as the US and Europe redirect Chinese goods toward emerging markets.
Pimco favours emerging-market local currency debt on contained inflation, relatively high real yields and orthodox central banks with room to cut, preferring Latin America, particularly Brazil, Colombia and Peru.
The firm is overweight duration, expecting real yields to fall further.
Chinese government bonds are seen as a stable, low-rate funding tool offering diversification, given China's cycle often diverges from the US and other major economies.
China's 10-year yields have fallen since around 2023 on deflationary pressure, contrasting with rising yields in the US and Australia.
Source: Bloomberg
Top All Ords gainers and movers
[10:15 am] Here are the top S&P/ASX All Ords movers in early trade.
Ticker | Company | % Chg | Price |
|---|---|---|---|
TVN | Tivan | 11.32% | $0.30 |
BNZ | Benz Mining Corp | 9.91% | $2.33 |
WTC | Wisetech Global | 4.54% | $30.07 |
XRO | Xero | 4.29% | $67.79 |
RWC | Reliance Worldwide | 4.21% | $3.71 |
4DX | 4DMedical | 4.02% | $4.92 |
BCI | BCI Minerals | 4.00% | $0.39 |
IGL | IVE Group | 3.72% | $2.79 |
MTM | Metallium | 3.61% | $0.43 |
BMC | BMC Minerals | 3.57% | $2.90 |
Ticker | Company | % Chg | Price |
|---|---|---|---|
CEL | Challenger Gold | -6.40% | $0.12 |
EIQ | Echoiq | -6.12% | $1.15 |
TBN | Tamboran Resources | -6.12% | $0.23 |
AIH | Advanced Innergy | -5.00% | $0.67 |
NMG | New Murchison Gold | -4.44% | $0.04 |
ALK | Alkane Resources | -4.24% | $1.54 |
ASM | Australian Strategic Materials | -4.17% | $1.27 |
ARU | Arafura Rare Earths | -3.85% | $0.25 |
PLA | Pacific Lime And Cement | -3.85% | $0.38 |
TBR | Tribune Resources | -3.82% | $5.03 |
Top ASX 200 gainers and losers
[10:10 am] Tech, industrials and rare earths stocks top the leaderboard, while gold, copper and lithium miners extend losses after commodity prices copped a beating overnight.
Ticker | Company | % Chg | Price |
|---|---|---|---|
WTC | Wisetech Global | 5.29% | $30.28 |
XRO | Xero | 4.29% | $67.79 |
ILU | Iluka Resources | 3.31% | $7.49 |
4DX | 4DMedical | 3.17% | $4.88 |
MEZ | Meridian Energy | 3.16% | $4.90 |
RWC | Reliance Worldwide | 3.09% | $3.67 |
LYC | Lynas Rare Earths | 3.01% | $19.15 |
TEA | Tasmea | 2.99% | $9.30 |
CBO | Cobram Estate Olives | 2.87% | $3.94 |
360 | Life360 | 2.86% | $22.98 |
Ticker | Company | % Chg | Price |
|---|---|---|---|
ALK | Alkane Resources | -3.43% | $1.55 |
SFR | Sandfire Resources | -3.34% | $19.27 |
BPT | Beach Energy | -2.66% | $0.92 |
GMD | Genesis Minerals | -2.41% | $5.68 |
CMM | Capricorn Metals | -2.18% | $13.01 |
EVN | Evolution Mining | -2.18% | $12.37 |
RSG | Resolute Mining | -2.13% | $1.06 |
LTR | Liontown | -2.13% | $1.84 |
LOV | Lovisa | -2.01% | $22.37 |
VEA | Viva Energy Group | -1.92% | $2.04 |
Nickel Industries to invest US$169m for 17.5% of TMI HPAL project
[9:36 am] Nickel Industries will invest US$169 million for a 17.5% stake in the PT Teluk Metal Industry HPAL project in Indonesia, deepening its push into the EV battery supply chain.
TMI is an expansion of the existing ENC project at the Indonesia Morowali Industrial Park, producing mixed hydroxide precipitate, with the acquisition payment due 26 November 2026
The 17.5% stake sits alongside a 72.5% interest held by a Korean-Japanese consortium including LS MnM and Hanwa, and a 10% holding by Sumber International Investment
A construction guarantee caps the total acquisition cost at US$169m and underwrites delivery of nameplate production by September 2027
TMI's nameplate capacity of 38,640 Ni tonnes a year delivers around 6,775 Ni tonnes a year of attributable MHP production to Nickel Industries
The Sampala Project has been named TMI's exclusive ore supplier, aligning the company as both equity investor and upstream supplier
To be funded from cash reserves and existing operations, with largest shareholder Shanghai Decent on hand to provide debt funding if needed
One of the last large-scale HPAL opportunities following the Indonesian government's moratorium on new projects, with the proven HNC HPAL delivering adjusted EBITDA margins of US$9,996/t Ni in Q1 2026
Company page: Nickel Industries (NIC)
Baby Bunting cuts FY26 guidance as fourth-quarter trade softens
[9:26 am] Baby Bunting has downgraded its FY26 profit guidance after softer-than-expected fourth-quarter trading, with prams and car safety dragging on sales.
Pro forma NPAT now seen at $16.0-17.0m, down ~11% on prior guidance of $17.5-19.5m
Below $17m ests (3% miss at the midpoint)
Though still up 32-40% on FY25
Total sales of $553-555m vs. $571.2m ests (~3% miss)
Comparable store sales growth of around 3.5%, roughly half the prior guidance of 5-7%
Gross margin above 41% vs. 40.2% a year ago
Store of the Future sales growth of around 18% for the year, with online up around 16%
CEO Mark Teperson flagged three RBA rate rises in the second half and higher fuel prices as weighing on consumer spending and distribution costs
Net debt expected to finish at around $20m, with FY26 results due 14 August 2026
Company page: Baby Bunting Group (BBN)
Tasmea to acquire energy services group JPS
[9:23 am] Tasmea has agreed to acquire integrated energy services provider JPS Group for total consideration of up to $75 million, diversifying into LNG and gas infrastructure markets.
Upfront consideration of $50m, comprising $24.5m cash and $25.6m in scrip (3,011,750 new shares at $8.50)
Earn-out of up to $25m in cash across FY27 to FY30, tied to JPS hitting a maintainable EBIT target of at least $12m a year
Struck at an upfront EV/EBIT multiple of ~5x JPS FY26e underlying EBIT of about $10m
Forecast to deliver ~5% pro forma EPS accretion in FY26e, incremental to the Maxim Group deal
Settlement targeted around 1 August, subject to ACCC approval, with earnings to contribute from FY27
JPS serves a Tier-1 client base including Chevron, Woodside, Shell and Santos under more than 10 long-term MSAs
On guidance:
FY26 pro forma underlying EBIT of $185m, up from $175m including Maxim
FY26 pro forma underlying NPAT of $113m, up from $107m including Maxim
FY26 standalone underlying EBIT of $117m reconfirmed, up 26% on FY25's $93.2m pro forma
FY26 standalone underlying NPAT of $72.5m reconfirmed, up 16% on FY25's $62.5m pro forma
Company page: Tasmea (TEA)
Atlas Arteria takeover extended after IFM crosses 50%
[9:15 am] IFM's Diamond Infraco has extended its off-market takeover offer for Atlas Arteria after its voting power passed 50% in the final week of the offer period.
Voting power in Atlas Arteria crossed above 50% within the last seven days of the offer period, triggering an automatic extension
The offer is now open for acceptance until 7:00 pm AEST on 7 July 2026, unless withdrawn or further extended
The bid, lodged via IFM Global Infrastructure Fund subsidiary Diamond Infraco, targets all shares it does not already own
Company page: Atlas Arteria (ALX)
3P Learning block trade
[9:15 am] A 16.2m-share block in 3P Learning crossed on Wednesday at 32.97 cents a share, representing 5.9% of the company.
Company page: 3P Learning (3PL)
US growth picks up in June but factory job cuts hit post-2009 high
[9:05 am] US business activity grew at its fastest pace in five months in June, though employment fell and price pressures stayed elevated.
The composite PMI rose to a five-month high of 52.2 from 51.5, pointing to growth of just over a 1% annualised rate in Q2
Manufacturing output hit a 59-month high as new orders surged, though the lift was again driven by precautionary stockpiling amid supply fears
Services activity edged up to a four-month high of 51.3, held back by high prices, elevated rates and weak consumer confidence
Employment fell for a second straight month, with factory job cuts at their fastest since 2009 outside the pandemic
Input cost inflation cooled on lower energy prices but stayed among the highest in four years, keeping selling-price inflation elevated
S&P Global's Chris Williamson said brighter Middle East news has restored some confidence, though growth remains sluggish versus pre-conflict levels
Source: S&P Global
UK output shrinks for second month as services hit 41-month low
[9:04 am] UK private sector activity contracted again in June as a sharp services slowdown outweighed a temporary boost to manufacturing.
The composite PMI eased to 49.4 from 49.7, a 14-month low and a second straight month below 50
Services activity fell to a 41-month low of 48.7, with firms blaming the Middle East war and domestic political uncertainty
Manufacturing output jumped to a 21-month high of 53.6, though the lift is fading as stockpiling-driven demand eases
Input price inflation moderated for a second month on lower energy prices but stayed elevated, allowing a softer rise in selling prices
Firms cut headcounts for a 21st straight month as new business fell at the fastest rate in 14 months
Source: S&P Global
Eurozone downturn eases in June as price pressures soften
[9:02 am] The Eurozone private sector contracted at its slowest pace in three months in June, with inflationary pressures showing early signs of peaking.
The composite PMI rose to 49.5 from 48.5, a three-month high but a third straight month below the 50 mark separating growth from contraction
Services activity improved to 48.9 from 47.7, while manufacturing output eased to a five-month low of 51.2
Germany posted its fastest contraction in 18 months, while France's downturn eased and the rest of the bloc grew modestly
Input cost inflation slowed to its weakest since February, helped by lower energy prices, with output price inflation also easing
Most responses were collected before the 17 June US-Iran cessation of hostilities, with tourism and leisure demand recovering
Source: S&P Global
Hormuz traffic recovers as more tankers signal crossings openly
[8:54 am] Tanker traffic through the Strait of Hormuz is picking up with vessels broadcasting their locations again, signalling growing shipowner confidence after the Iran-US peace deal.
Seven tankers, including two fully-laden non-Iranian supertankers, were in or had crossed the strait on Tuesday, all broadcasting their positions
Iran said the strait is fully open with large volumes transiting, after weekend reports it had been closed
Some ships still go dark mid-crossing, including a Taiwan-bound VLCC carrying Saudi and UAE crude that switched off its transponder before reappearing in the Gulf of Oman
Source: Bloomberg
SpaceX's US$25bn bond debut meets cautious credit investors
[8:52 am] SpaceX's first bond sale drew a more sceptical reception than its record IPO, with investors demanding a premium over comparably rated debt on cash-flow concerns.
The 2036 bonds priced at 1.4 percentage points over Treasuries, around 0.4 point wider than the average BBB-tier spread
Orders peaked near $90bn before falling to $73bn at pricing, leaving the book at under three times the deal size vs. a roughly four-times average for high-grade deals this year
Demand skewed to the shortest-dated, least risky tranche, reflecting concerns over a cash burn S&P expects to persist through 2030 and rise sharply next year
SpaceX held more than $100bn of cash as of 19 June and can cut investment or raise equity to defend its high-grade ratings
Moody's rated the deal Baa1 and S&P one notch lower at BBB, with S&P seeing borrowings climbing to $132bn in 2028 from near zero now
Shares rose 0.9% overnight after a three-day selloff erased more than $600bn in value, leaving them about 15% above the IPO price
Source: Bloomberg
Evercore stays bullish on megacap tech, says earnings will drive recovery
[8:51 am] Evercore ISI's Julian Emanuel expects megacap tech to return to favour after the selloff, arguing earnings will be the catalyst once volatility settles.
Emanuel says strong earnings will be the "proof of the pudding" and drive a rally, as they did during the April and May surge
He expects more churn, volatility and negativity in the near term before a refreshed attitude towards the Mag 7 develops
Alphabet, Amazon and Microsoft have fallen more than 13%, over 15% and almost 20% respectively from recent peaks, with the Nasdaq 100 erasing June gains
Micron is a bright spot ahead of Thursday's results, up more than 300% this year, with Bloomberg Intelligence seeing fiscal Q3 revenue beating guidance by 18% on higher chip prices
Source: Bloomberg
Barclays and Stifel lift S&P 500 target to 7,800 on earnings strength
[8:50 am] Barclays and Stifel raised their year-end S&P 500 targets to 7,800, around 4.4% above the last close, on the back of resilient corporate earnings.
Both cited strong earnings as the primary driver, with Barclays noting the bull case stays intact but earnings and AI capex visibility must do more of the work as Fed support fades
Barclays lifted its 2026 EPS forecast to $337 from $321 and set a 2027 index target of 8,800
Stifel's Thomas Carroll sees stock concentration at 40-year highs signalling a rotation out of megacaps into equal-weight indices
Carroll favours cyclicals such as energy, industrials, materials and select semiconductors with the economy running hot
Source: Reuters
KOSPI crashes 10% as memory rout triggers circuit breaker
[8:46 am] South Korea's KOSPI fell 9.99% on Tuesday as a media report on SK Hynix slowing AI memory expansion sparked a chip selloff that rippled globally.
The KOSPI closed down 9.99%, or 910.71 points, at 8,203.84, its steepest fall since March
Samsung Electronics and SK Hynix each shed more than 12%, triggering an automatic 20-minute market-wide trading halt
The catalyst was a Chosun Biz report that SK Hynix is slowing HBM4 expansion and shifting to higher-margin general-purpose DRAM, with the report citing weaker production forecasts for Nvidia's next-generation Rubin chip
The two chipmakers now make up more than half the index's value, having pushed the KOSPI past 9,100 for the first time on Monday
The index is still up 94.67% year-to-date despite the plunge, with CLSA flagging that record margin debt and newly approved leveraged single-stock ETFs have amplified retail-driven volatility
Fed holds and rate-cut expectations get priced out
[8:45 am] The probability of a Fed rate cut by year-end now sits at zero, with a 25 bp hike now the base case and increasing likelihood of two or more quarter-point hikes.
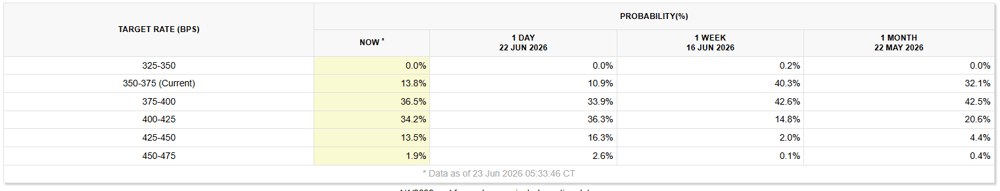
Source: CME Fedwatch Tool
BofA flips to three rate hikes in 2026, scrapping cut calls
[8:43 am] Bank of America has reversed its easing forecast and now expects the Fed to tighten through year-end as labour and inflation data hold firm.
BofA now sees three quarter-point hikes in 2026, pencilled in for September, October and December, a sharp break from its earlier rate-cut view
The shift follows May payrolls of 172,000, unemployment steady at 4.3% and wage growth still running at 3.4%, undercutting the case for easing
Inflation remains above the Fed's 2% target, with energy risks and firmer demand seen muddying the path lower
The Fed held at 3.5% to 3.75% on 17 June but turned more hawkish, with nearly half of policymakers flagging possible hikes ahead
BofA argues the market may be underpricing the risk that the next Fed surprise is tighter, not easier, policy
Source: Yahoo Finance
US equities dip as momentum unwind hits memory and semis
[8:38 am] US stocks closed lower on overnight, with a momentum unwind in memory and semiconductors driving the move rather than any shift in fundamentals.
Dow (0.09%), S&P 500 (1.44%), Nasdaq (2.21%) and Russell 2000 (0.96%) all finished lower
Equal-weight S&P 500 (-0.34%) outperformed the cap-weighted index by 110bps, with breadth slightly positive
Memory and semis bore the brunt amid AI scrutiny spanning open-source competition, capex ROI and speculation around 2027 memory price weakness
Nvidia (-4.1%) and Tesla (-5.7%) were the worst of the mostly lower Big Tech names, while quantum computing, airlines and regional banks outperformed
June flash manufacturing PMI beat to hit a 49-month high and services PMI came in slightly ahead, though employment fell for a second straight month
Micron earnings (after tonight's close) and Thursday's PCE inflation print are the next focus
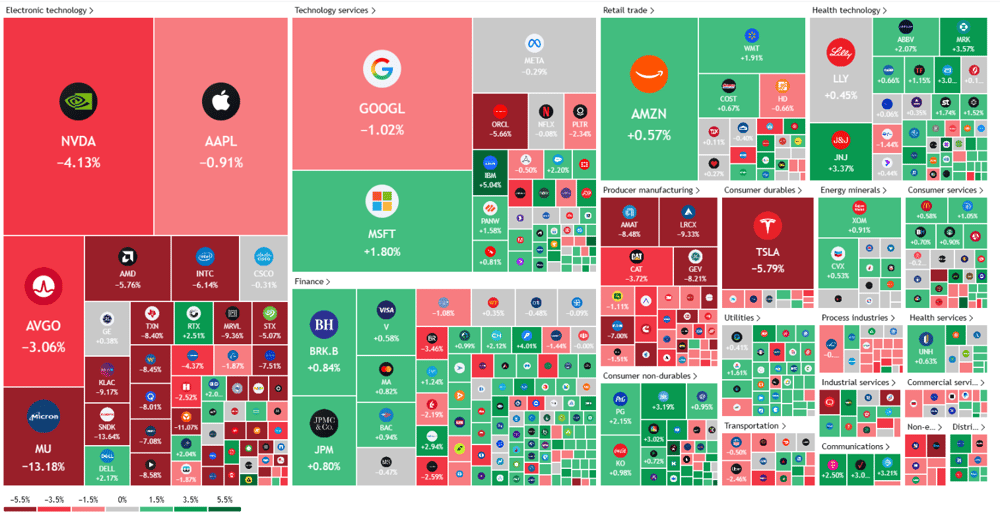
S&P 500 heatmap (Source: TradingView)
Good morning!
[8:29 am] ASX 200 futures are up 21 pts (+0.23%)
The overnight session in a nutshell:
Major US benchmarks lower amid a tech and resources-led selloff, which started in Asian markets (KOSPI tumbled 10%) and flowed through to Europe/Wall Street
A Bank of America note called for three Fed hikes in 2026, with markets now pricing out cuts entirely
Commodity prices were mostly down around 1-2% when the ASX closed on Tuesday, but selling accelerated overnight, with sharp declines for copper (-3.7%), aluminium (-3.0%), gold (-1.9%) and more