ASX 200 Live Today - Wednesday, 23rd September
The S&P/ASX 200 faded a positive open as sharp declines from Utilities, Telcos, Banks and Energy stocks offset gains from miners.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Wednesday, September 23. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
ASX 200 flat as miners gain, banks slightly off lows
[1:54 pm] That's a wrap! The ASX 200 is trading 1 point higher (+0.01%) after a choppy session, briefly rallying 0.39% in early trade before quickly flipping to a 0.17% decline. Miners did the bulk of the heavy lifting, with the All Ords Gold Index up 2.9% and the ASX 200 Resources Index up 1.4%. That strength was offset by relatively broad weakness elsewhere, with energy, telcos and utilities among the notable decliners. Financials have also clawed back from session lows of -1.3%, helping drag the index back to breakeven.
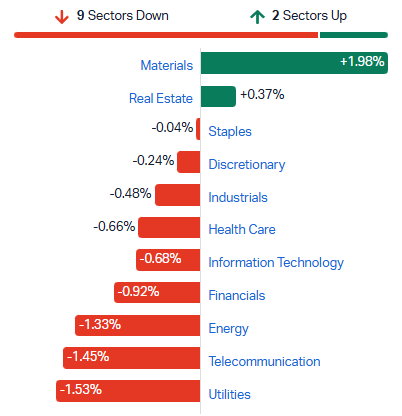
S&P/ASX 200 sectors (Source: Market Index)
Overall, not much to see here. Oil, yields and rate expectations look to be peaking and starting to move in the right direction. But the market remains choppy as it works through a seasonally weak September, and breadth has been persistently poor outside of healthcare, energy and a recent resurgence in miners.
China's coking coal squeeze set to linger into 2027
[1:34 pm] Bloomberg Intelligence expects the supply shock from May's fatal Shanxi mine accident to persist, keeping import demand strong even as prices retreat.
Chinese coking coal imports eased 4% from July's peak to 13.1mt in August, though still 29% higher year-on-year and not far off the record set in December 2025
Rising shipments from Mongolia, Australia and Russia are helping offset the shortfall but are unlikely to fully bridge the gap, with BI analysts including Ortis Fan seeing a steady Q4 recovery in Shanxi supply and full normalisation delayed until 1H27
Mine restarts have been gradual, with a 16 September Mysteel survey finding 75 coking coal mines still shuttered across Shanxi, representing nearly 73mt of annual capacity
Dalian coking coal futures have fallen 12% to 1,523.50 yuan a ton from 1,729 yuan on 31 August, which had been the highest in over two years, as improving output prospects and weak mill margins weigh
Wood Mackenzie's Simon Wu said barely 7% of steel mills were operating profitably in September and their capacity to absorb persistently high coking coal prices has reached breaking point
The NDRC has called for accelerated resumption of mines suspended after the Shanxi accident, including allowing lower-risk operations to restart, while Singapore iron ore last traded at $96.55 a ton
Source: Bloomberg
RBA says ASX still falling short in several key areas
[1:30 pm] The central bank's annual assessment found ASX's clearing and settlement facilities only partly observed standards across a number of critical areas.
One or more facilities only "partly observed" standards on governance, comprehensive risk management, credit risk and operational risk
Assistant Governor Brad Jones said that despite progress during the year, ASX is still not meeting the RBA's expectations in several important areas
The challenge now is delivering the transformation program without compromising the safe and reliable operation of critical infrastructure, Jones said
The RBA did lift its operational risk assessment of ASX Clear and ASX Settlement to "partly observed" from "not observed" following work on Chess after the December 2024 outage
CEO Anthony Attia said the report makes clear there is more to do, with focus on delivering committed technology and transformation improvements and rebuilding trust through consistent execution
ASX has been ramping up its Accelerate transformation agenda since an inquiry into the bourse concluded in April, having also faced a $14.5m fine over a misleading Chess statement
Source: Bloomberg
Copper to aluminium ratio hits a record as UBS flags reversion risk
[1:16 pm] UBS says the copper-to-aluminium price ratio is stretched to a record and the likely path back towards its historical range runs through copper weakness rather than an aluminium rally.
The Cu:Al ratio has risen roughly 25% since early May to a record 4.51x from 3.60x, against a five-year average of 3.70x and now around 2.6 standard deviations above that mean
The divergence reflects genuine fundamentals, with copper's structural deficit outlook underpinned by electrification and the energy transition set against an increasingly bearish aluminium supply pipeline as Indonesian, Middle East and Chinese tonnes layer in
A high ratio strengthens the incentive for copper-to-aluminium substitution, though UBS notes the behavioural shift moves slowly through supply chains from both a manufacturer and customer-preference perspective
US Section 232 tariff policy is the key variable, having pulled refined copper onshore and concentrated visible inventory in the US while ex-US stocks sit critically low, tightening the accessible market and propping up the price
A no-tariff outcome risks more than 10% sustained copper downside as trapped metal is released, which UBS views as the clearest downside catalyst for both copper and the ratio
On spot prices, earnings and fair value momentum, UBS sees MIN and BHP as offering the greatest positive fair value leverage across its diversified mining coverage
Macquarie upgrades AMP to Outperform on Chinese pension JV
[12:24 pm] Macquarie has lifted AMP to Outperform from Neutral with a $2.92 target price, up from $2.28, arguing the market is undervaluing the company's Chinese partnership.
China contributed $56m of AMP's $174m 1H26 underlying NPAT, up around 100% and roughly a third of group profit, with Chinese Partnership revenue equal to about 29% of group EBIT
The CLPC joint venture is China's largest enterprise-annuity trustee, with AUM of around RMB2.4t equivalent to roughly 30% of the RMB8.0t Pillar 2 asset pool at December 2025 on Macquarie's calculations
AMP carries its CLPC stake at $589m, while priced minority deals at Ageas/Taiping (2.8x book) and Jianxin (3.1x) imply $1.06–1.21bn or $0.44–0.50 a share, roughly double the carrying value
Macquarie has marked its own valuation of the stake down 30% for regulatory and policy uncertainty, minority ownership and limited disclosure, but concedes that could be too conservative given the capital light model and 18% NPAT CAGR over 2019 to 2025
The 2023 crackdown is described as regulatory rather than structural, with the wind-down of short-dated products sold through bank apps and Alipay now fully in comparative periods and no notable impact expected from the latest five-year plan to 2030
Earnings estimates rise 7% in FY26, 15% in FY27 and 24–31% thereafter, with the 3Q26 flows update on 15 October flagged as the next catalyst, though Chinese partnership data is not disclosed quarterly
AMP shares are up 2.9% at the time of writing to $2.62. The stock is up 48.4% year-to-date.
Company page: AMP (AMP)
Lithium stocks broadly higher
[12:21 pm] Lithium stocks are trading broadly higher, with the bellwether PLS Group up 2.1% and edging into positive year-to-date territory.
Chinese lithium carbonate futures opened 1.2% higher this morning, but now down 1.9% to 130,600 yuan a tonne. So it'll be interesting to see if these names will hold up throughout the day.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
CXO | Core Lithium | 9.3% | $0.41 | 15.5% | 49.1% |
AGY | Argosy Minerals | 6.3% | $0.03 | 6.3% | -71.7% |
DLI | Delta Lithium | 4.4% | $0.17 | 1.2% | -24.1% |
INR | Ioneer | 4.3% | $0.12 | 9.1% | -35.1% |
GL1 | Global Lithium Resources | 3.5% | $1.03 | 60.9% | 63.5% |
IGO | IGO | 2.6% | $6.97 | -2.7% | -15.0% |
LTR | Liontown | 2.2% | $1.04 | 0.2% | -33.6% |
PLS | PLS Group | 2.1% | $4.22 | 0.1% | 0.4% |
MIN | Mineral Resources | 1.7% | $55.03 | 0.7% | 1.2% |
PMT | PMET Resources | 1.5% | $0.47 | 9.9% | -21.5% |
VUL | Vulcan Energy Resources | 0.2% | $2.17 | -3.3% | -50.9% |
PAT | Patriot Resources | 0.0% | $0.05 | -3.8% | -5.6% |
EUR | European Lithium | -6.6% | $0.40 | 16.8% | 156.1% |
ASX 200 slips as telcos and bank stocks tank
[11:20 am] The ASX 200 is currently down 11 pts (-0.13%), down from session highs of (+0.39%). Financials (-1.1%) are on the cusp of a three-month low, with CBA closing at the lowest since 4-Feb. While most other sectors are trading lower, with notable weakness for oil-linked sectors like Utilities (-1.4%) and Energy (-1.0%). Despite Brent falling below US$100 overnight, consumer-facing sectors like Discretionary and Staples are edging lower. Continued gainers for Materials (+1.8%) has failed to offset everything else.
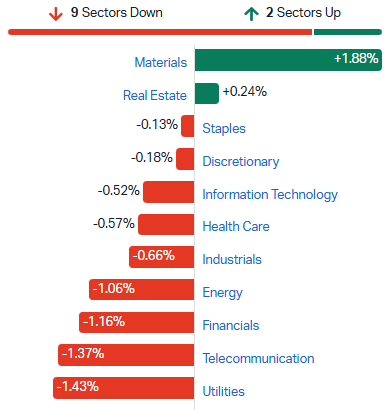
S&P/ASX 200 sectors (Source: Market Index)
ADB warns Asian inflation will stay elevated into 2027
[11:15 am] The Asian Development Bank says wars in Europe and the Middle East plus a severe El Niño are keeping price pressures high across the region and central banks on guard.
Inflation for developing Asia-Pacific forecast at 4.2% this year and 3.5% in 2027, both well above the 3% recorded in 2025
Growth expected to slow to 5% in 2026 from 5.5%, with oil price forecasts raised to $90 a barrel this year and $78 next
Supply shocks are broad-based, with renewed fighting in Iran and the spread of conflict to Yemen choking crude and refined product supply, Russia's war disrupting grain shipments, and El Niño threatening harvests from India to Thailand while cutting hydropower and restricting Panama Canal traffic
Broad subsidies have cushioned consumers so far but persistently high energy prices are now passing through, with the effect strongest where food carries a heavy weight in the consumption basket such as South Asia
Bangladesh, India, Indonesia, Pakistan, the Philippines and Vietnam are flagged as having scope for further tightening this year, with rate cuts only likely to come into view in 2027
Chief economist Albert Park said risks remain tilted to the downside, with further conflict escalation or worse than expected El Niño impacts capable of denting growth and pushing inflation higher
Source: Bloomberg
Tuas gaps and tumbles
[10:54 am] Tuas opened 6.8% higher ($2.49) this morning but experienced a V-shaped move lower, back at breakeven within the first two minutes of trade and down 15.5 ($1.96) by 10:09 am AEST.
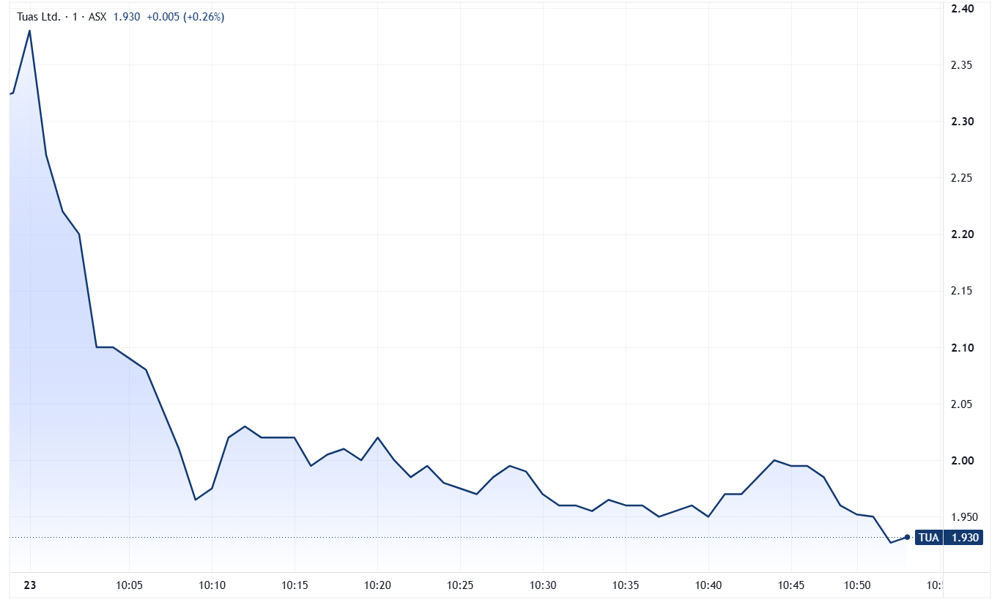
Tuas intraday chart (Source: TradingView)
The below ests are from Morgan Stanley, not consensus.
Revenue up 24% to S$187.6m vs S$185.7m ests (1% beat), driven by a growing subscriber base
Underlying EBITDA up 22% to S$83.7m vs S$83.0m ests (1% beat), with the underlying margin steady at 45%, while statutory EBITDA of S$80.1m includes pre-acquisition costs
Underlying NPAT of S$29.6m vs S$22.7m ests (30% beat), up from S$6.9m in FY25, with statutory NPAT of S$26.0m against ests of S$17.5m
Mobile subscribers up 16% to 1.458m vs 1.505m ests (3% miss), implying net adds of around 204k against the 251k modelled, with gross mobile ARPU of S$9.42
The M1 acquisition lapsed after the sale and purchase agreement hit its 21 May long-stop date without IMDA clearance, the regulator having suspended its review on 17 May pending an investigation into intermittent use of spectrum SIMBA had previously been authorised to use for specific purposes
The stock experienced a similar move on 26 March 2025, where a relatively clean set of numbers for 1H26 resulted in a brief 6-7% rally in early trade followed by a vertical move lower. The stock finished that session 8.2% lower (but dipped as much as 22.3% intraday).
Australian private sector growth slows to a crawl as jobs fall
[10:44 am] The September flash PMI showed the weakest expansion of the third quarter, with manufacturing contracting and employment falling for the first time since May.
Composite output index down to 50.8 from 52.7, the weakest reading across Q3, with services activity at 51.4 from 53.2 and manufacturing output at 46.4 from 49.6
Manufacturing PMI fell to 49.3 from 52.0, its first negative reading since March, with the drop in manufacturing output the steepest in 21 months amid a renewed contraction in order books
Private sector employment fell for the first time in four months, and while the reduction was modest it was the strongest since October 2020 and broad-based across sectors
New export orders declined for the fifth time in six months, again driven by manufacturing weakness, while overall new business grew at the slowest pace in three months
Input price inflation picked up to a three-month high and output charges rose more strongly than in August, with panellists frequently citing the Middle East conflict and its effect on energy and fuel costs, though both rates remain well below Q2 levels
S&P Global's Eleanor Dennison said businesses lost some confidence in their growth prospects in September, with sentiment at a three-month low and below the series average on concerns around cost pressures, demand and customer retention
Source: S&P Global
Top ASX 200 gainers
[10:30 am] Gold and lithium stocks top the leaderboard have a strong overnight session for most commodity prices.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
PNR | Pantoro Gold | 7.7% | $3.07 | 19.9% | -37.3% |
ELV | Elevra Lithium | 7.3% | $6.61 | -1.6% | -17.7% |
CYL | Catalyst Metals | 6.1% | $6.14 | -4.1% | -16.9% |
NST | Northern Star Resources | 4.5% | $22.91 | 4.1% | -6.7% |
CMM | Capricorn Metals | 4.3% | $16.15 | 12.7% | 15.3% |
NEM | Newmont | 4.2% | $179.13 | 3.4% | 19.3% |
MI6 | Minerals 260 | 4.1% | $0.93 | 3.6% | 121.9% |
GGP | Greatland Resources | 4.1% | $11.25 | 7.6% | 7.2% |
LTR | Liontown | 3.9% | $1.06 | 1.9% | -32.5% |
GMD | Genesis Minerals | 3.8% | $7.84 | 7.3% | 9.5% |
Top ASX 200 losers
[10:30 am] Tuas opened the session 6.8% higher but traded (vertically) lower from there, elsewhere defence, industrials and insurers are on the backfoot in early trade.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
TUA | Tuas | -14.6% | $1.99 | -6.1% | -71.8% |
EOS | Electro Optic Systems | -6.9% | $10.54 | 13.3% | 11.7% |
ALX | Atlas Arteria | -4.7% | $4.24 | -3.2% | -13.8% |
TLX | Telix Pharmaceuticals | -4.5% | $16.03 | -8.7% | 42.5% |
ALL | Aristocrat Leisure | -4.4% | $59.18 | -3.5% | 2.5% |
TAH | Tabcorp | -3.0% | $0.92 | -1.9% | -5.9% |
KAR | Karoon Energy | -2.5% | $1.76 | -6.6% | 14.3% |
IAG | Insurance Australia Group | -2.4% | $7.88 | -3.9% | -0.9% |
AUB | Aub Group | -2.3% | $28.43 | -2.2% | -7.0% |
SLC | Superloop | -2.0% | $2.65 | -0.9% | 1.3% |
Tuas beats on earnings as M1 deal lapses and subscriber growth undershoots
[9:57 am] Comparisons below are to Morgan Stanley ests as of 14 September only, not consensus. The stock has been trading largely sideways since the ~63% one-day selloff on 18 May, when the company terminated its agreed A$1.59bn acquisition of Singaporean digital network operator M1 Limited.
Revenue up 24% to S$187.6m vs S$185.7m ests (1% beat), driven by a growing subscriber base
Underlying EBITDA up 22% to S$83.7m vs S$83.0m ests (1% beat), with the underlying margin steady at 45%, while statutory EBITDA of S$80.1m includes pre-acquisition costs
Underlying NPAT of S$29.6m vs S$22.7m ests (30% beat), up from S$6.9m in FY25, with statutory NPAT of S$26.0m against ests of S$17.5m
Mobile subscribers up 16% to 1.458m vs 1.505m ests (3% miss), implying net adds of around 204k against the 251k modelled, with gross mobile ARPU of S$9.42
The M1 acquisition lapsed after the sale and purchase agreement hit its 21 May long-stop date without IMDA clearance, the regulator having suspended its review on 17 May pending an investigation into intermittent use of spectrum SIMBA had previously been authorised to use for specific purposes
FY27 mobile and broadband capex guided to S$50–55m, with an additional S$15–30m of capex and opex expected to meet cybersecurity requirements
Morgan Stanley is Overweight and a buyer on weakness, arguing even an unfavourable regulatory outcome could unlock value given the subscriber base and undemanding valuation, with the stock on around 4x FY27 EV/EBITDA against a historical average nearer 34x
Company page: Tuas (TUA)
Patriot Battery Metals completes Phase 2 caesium testwork with Koch
[9:54 am] Patriot has finished a second bench-scale testwork program with Koch Technology Solutions aimed at producing high-purity caesium chemicals from its Shaakichiuwaanaan pollucite concentrate.
Patriot is a lithium developer advancing the Shaakichiuwaanaan project in Quebec, where caesium and tantalum are anticipated co-products alongside lithium
The Phase 2 program demonstrated a pathway to produce multiple caesium products, with KTS's proprietary technology potentially simplifying the flowsheet and lowering costs versus conventional processing
A follow-up program is now being designed and is expected to expand to a complete bench-scale proof-of-concept including production of marketable samples
Pollucite concentrate from the ongoing BerryPick Program will feed the next phase of testwork with KTS
A Preliminary Economic Assessment targeted for Q4 CY26 will provide the first economic evaluation of the caesium credit, with co-product revenue potentially offsetting the cost of lithium production
Discussions continue with strategic downstream caesium players, including deepening the existing relationship with KTS
TSX-listed PMET shares rallied 5.8% overnight to C$4.69.
Company page: Patriot Battery Metals (PMT)
Strike Energy flags reserves upgrade and West Erregulla pathway in FY26 annual report
[9:52 am] Strike Energy has released its FY26 annual report, pointing to a larger reserve base at West Erregulla and a processing solution for the project, though earnings fell sharply.
Sales revenue down 14% to $62.8m from $72.7m, with underlying EBITDA down 58% to $17.6m and operating cashflow down 85% to $6.4m
Cash and equivalents up 13% to $46.3m at 30 June, with a further $30m of committed Macquarie Bank financing capacity becoming available post year end
Net 2P reserves at West Erregulla up approximately 20% to 251PJ following an independently audited reserves and resources review
Hancock Energy's Belisama Gas Processing Facility selected as the preferred processing solution for West Erregulla post year end, targeting 43.5TJ/d of capacity net to Strike and establishing a pathway towards FID
Strike and Hancock agreed in-principle to up to $30m of pre-FID funding support via loan to cover Strike's share of West Erregulla development activities through to FID
The 85MW South Erregulla Peaking Power Project advanced substantially during FY26, with commercial operations targeted in Q4 CY26, while Shelley Robertson became MD and CEO from 1 June and Nev Power took the chair from 1 July
Company page: Strike Energy (STX)
Nufarm guides to 25% underlying EBITDA growth and lower leverage
[9:36 am] Nufarm has updated the market on FY26 performance ahead of its result, flagging stronger earnings, positive free cashflow and a materially deleveraged balance sheet.
FY26 underlying EBITDA expected at $370–380m, representing around 25% growth on FY25 at the midpoint
Leverage expected to fall to approximately 2.0 times at 30 September 2026 from 2.7 times a year earlier, reflecting improved earnings, positive free cashflow generation and disciplined working capital management
Seed Technologies is expected to deliver strong underlying EBITDA growth on the prior corresponding period, driven by Hybrid Seeds and Omega-3
On track for $50m of run-rate cost savings by the end of FY27, with the strategy refresh including closure of the Alsip manufacturing facility in the US, the previously announced Kwinana closure and accelerated SKU rationalisation
The latest Bell Potter note (2-Sep) has FY26 EBITDA growth at 23.9% (from $302.2m to $374.7m est). The stock has rallied 13.6% on the day of its 1H26 result (27-May), and has been grinding higher ever since.
Company page: Nufarm (NUF)
Ventia extends WA court security and custodial contract
[9:29 am] Ventia has secured an extension with the Western Australian government to keep delivering Court Security and Custodial Services.
The extension runs from March 2027 to June 2028 and is expected to generate approximately $110m in revenue over the period
Ventia has held the contract since 2017, working with the Department of Justice as operational requirements and demand across the state's justice system have evolved
Services covered include court security, court custody, transport, medical movements and support services across metropolitan and regional Western Australia
CEO Mark Ralston said the experienced workforce is well positioned to continue supporting the safe and effective operation of the justice system
Company page: Ventia Services Group (VNT)
Myer statutory loss on impairment as underlying NPAT beats
[9:28 am] Myer delivered a better-than-expected FY26 underlying net profit, but no final dividend, leaving the full-year payout short of market expectations. Comparisons below are to Ord Minnett ests only, not consensus.
Total sales up 11.3% to $4.09bn on an actual basis, up 0.7% comparable and 0.3% pro forma, with Myer Retail growth in Women's Fashion, Home, Kids, Concessions and Marketplace offset by Beauty
Operating gross profit up 14.0% to $1,603.2m with OGP margin of 39.2% versus 38.3% on an actual basis, though down 1.6% pro forma on higher than planned promotional activity to stimulate demand
Cost of doing business of $1,189.7m, with CODB as a percentage of sales in line with the FY26 target of around 29%, supported by integration synergies and the Value Creation program
Underlying EBIT down 7.0% to $139.4m on an actual basis and down 23.5% pro forma, reflecting opex investment for strategic initiatives
Underlying NPAT down 2.9% to $42.5m vs $39m ests (9% beat), though down 32.1% on a pro forma basis
Statutory NPAT loss of $276.5m, driven by a one-off non-cash post-tax impairment of $279.6m across goodwill, brand intangibles and store assets
No final dividend declared, leaving FY26 dividends at the 1.5cps fully franked interim paid in May for a 60.0% payout ratio, below ests of 2cps
First eight weeks of 1H27 show Myer Group comparable sales flat at +0.2%, with Myer Retail up 1.8% comparable but Myer Apparel Brands down 5.9%, and FY27 CODB again targeted at around 29% of sales
Company page: Myer Holdings (MYR)
Capricorn completes Karlawinda expansion on schedule at 6.5Mtpa
[9:24 am] Capricorn Metals has finished construction of the Karlawinda Expansion Project and started continuous ore processing through the new circuits.
Construction and installation were completed on schedule in 12 months, with commissioning done over the past two weeks and all components of the new parallel crushing, milling and CIL circuits now operational
Targeted steady state throughput of 6.5Mtpa has been achieved, with further optimisation of product size from the KEP crushing circuit ongoing and commissioning of the CIL areas and TSF 2 pipework complete
The plant is currently running low grade ore and will transition to run of mine grade over the coming week as it moves to steady state, with ROM stocks continuing to build on ROM Pad 2
The expanded operation is expected to produce around 150,000oz of gold a year, underpinned by a mine life of more than 10 years on existing reserves
Executive Chairman Mark Clark called it a significant milestone and said the company now looks forward to Karlawinda transitioning into a long life operation
Company page: Capricorn Metals (CMM)
KMD Brands returns to underlying EBITDA growth as impairment drives statutory loss
[9:10 am] The Kathmandu and Rip Curl owner lifted sales and more than doubled underlying EBITDA in FY26, though a $462.7m intangible write-down pushed the statutory result deep into the red. No broker estimates were available for comparison.
Sales up 6.5% to NZ$1,053.0m, up 1.7% on a constant currency basis, with growth across both direct-to-consumer and wholesale channels
Gross profit up 8.6% to NZ$607.2m, with gross margin expanding 1.2ppt to 57.7% on improved sourcing, less promotional trading and favourable input-cost FX including $8m of tariff refunds
Underlying EBITDA up 137.7% to NZ$42.0m, lifting EBITDA margin to 4.0% from 1.8%, with underlying operating expenses up 4.4% but down 0.2% in constant currency
Underlying NPAT loss of NZ$9.0m, narrowed 68.4% from a NZ$28.3m loss, while the statutory loss of NZ$414.4m includes the NZ$462.7m intangible asset impairment
Trading update for the first seven weeks to 13 September shows Kathmandu DTC same store sales up 7.4% and Rip Curl up 1.0%, with Rip Curl brand stores up 4.0% offset by Ozmosis down 12.1% on product assortment issues
FY27 guidance points to further gross margin expansion from existing FX hedging and strategic price rises, a further $10m of annualised cost savings, five Ozmosis store closures, reduced capex and depreciation of NZ$40–41m
NZX-listed KMD shares are flat at the time of writing, but rallied 7.1% on Tuesday.
Company page: KMD Brands (KMD)
Copper hits all-time highs
[9:00 am] Copper rallied 1.6% overnight to a record US$6.92/lb, now up 7.9% in the last six sessions. Prices have pushed 0.8% above where they traded before US refined copper tariff headlines sparked a sharp ~5% pullback on 10 September.
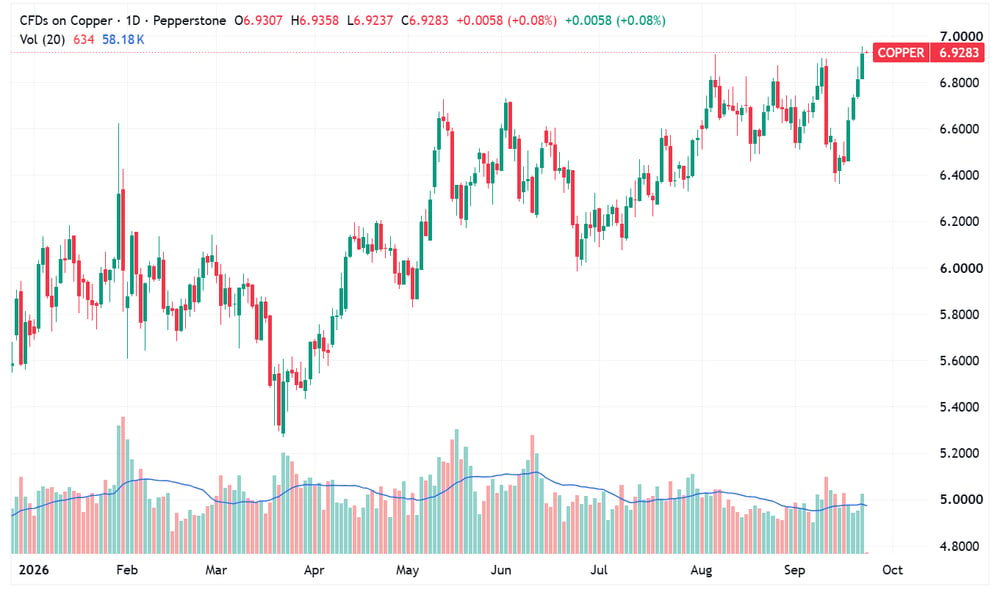
Copper daily price chart (Source: TradingView)
Despite copper prices trading back at record highs, a copper equities barometer like the Global X Copper Miners ETF rose 2.8% overnight but still 5.8% away from those 9 September levels. We've seen these episodes before, between June and July, when copper equities lagged copper prices by 8-10%. The gap eventually closed by mid-August as copper prices continued to trade around record levels.
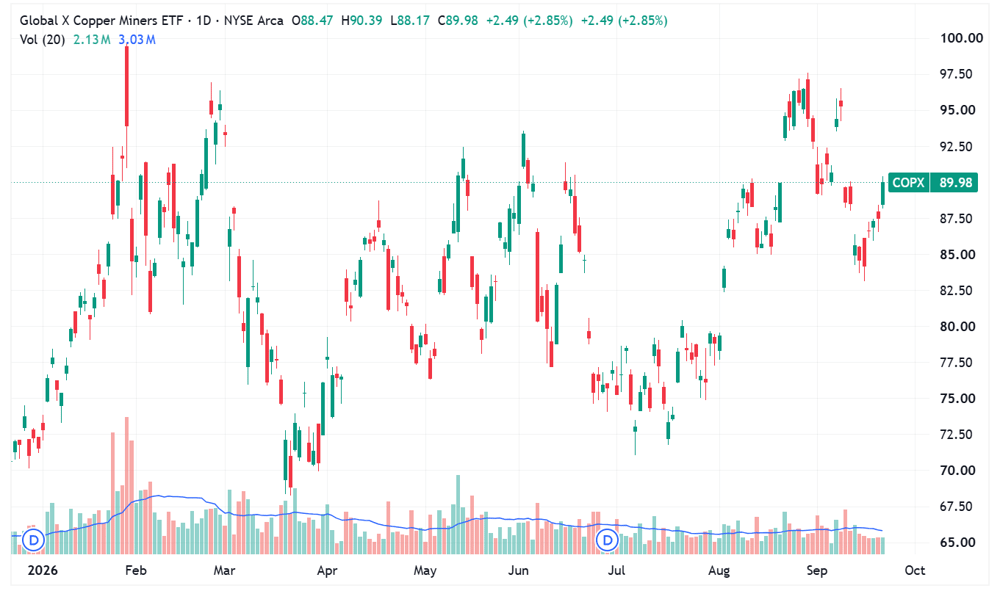
Global X Copper Miners ETF (Source: TradingView)
Barkin warns supply shocks aren't fading, leaves door open to more hikes
[8:40 am] The Richmond Fed president said stubborn inflation driven by oil and tariffs forced last week's rate rise, and further tightening remains on the table.
Barkin pushed back on the view that inflation would return to target without Fed help, saying the supposedly passing shocks are not proving short-lived or one-off
He pointed to ongoing tariff imposition, the continuing Middle East conflict and the AI build-out as sources of persistent supply chain stress that he expects will take time to fade
Inflation has run above the 2% target for more than five years, and while oil has driven this year's rise, more than 60% of the PCE basket is now increasing faster than 3% year-on-year
Richmond Fed survey data showed prices received have grown 3.5% on average since late 2023, close to double the pre-pandemic two-year average, while the CFO Survey has firms planning 4.1% price rises next year, more than twice the 2019 average
On the growth side he described the economy and labour market as on solid footing, with spending skewed to the well-off but lower-income households still finding ways to keep spending, and businesses moving ahead despite uncertainty
Asked whether more hikes are needed, Barkin said the committee is committed to returning inflation sustainably to 2% and that last week's move will help, but on the number of further increases, "we'll see"
Iran dangles Hormuz reopening as Trump pushes deal past midterms
[8:39 am] Oil slipped on signs of improving Middle East crude flows, though Trump's comment that a peace deal would only come after the November midterms pared the early losses.
Brent fell 1.5% to US$98.54, now down 9.1% in the last five sessions, with the retracement coming once Trump said a deal would not land until after the US midterms in early November
A senior Iranian official told Reuters Tehran could reopen the Strait of Hormuz within seven days if Washington eases military pressure and lifts its blockade of Iranian ports, with the delegation in New York said to have full authority to revive diplomacy
Saudi Arabia has restarted its East-West pipeline and could resume Yanbu exports, with Phil Flynn of Price Futures Group noting Aramco loaded roughly 14 million barrels onto seven VLCCs inside the Gulf and Saudi crude through Hormuz has averaged about 2.9 million barrels a day over the past six days, up from around 700,000 in August
Trump said he has pushed advisers to approve a US diesel export ban with the national average pump price at a record $6.52 a gallon, up 77% year-on-year, though GasBuddy's Patrick De Haan argues US diesel prices are set by a global balance and cannot be fenced off by executive order
Nasdaq 100 notches first record since June as oil slides
[8:36 am] A renewed chip rally and hopes for a Middle East ceasefire pushed the tech-heavy index to a fresh high, though the broader market stayed flat.
The Nasdaq 100 rose 0.8% to its first record close since June, while the S&P 500 was little changed and the Dow fell 0.4%
A closely watched semiconductor gauge including Micron and Nvidia climbed for a sixth straight session, with the industry advance offsetting a selloff in bank shares
Fed speakers struck a cautious tone, with Richmond's Tom Barkin warning inflationary shocks could take time to wane and Boston's Susan Collins backing last week's decision to raise rates
The 10-year Treasury yield was little changed at 4.96%
Bloomberg's Michael Ball says leadership has rotated decisively back to semiconductors and hyperscalers, enough to keep the indices grinding higher, but a more convincing rally needs broader participation
Source: Bloomberg
Good morning!
[8:27 am] ASX 200 futures are up 18 pts (+0.20%). Here's what happened overnight:
Tech carried Wall Street as chipmakers rallied for a sixth straight session, offsetting a selloff in bank shares
Philadelphia Semiconductor Index (+2.0%)
S&P 500 flat, Equal-weight S&P 500 (+0.06%)
Nasdaq (+0.45%), Dow (-0.36%) and Russell 2000 (+0.51%)
Brent fell 1.5% to US$98.49, a two-week low on signs Iran could reopen Hormuz within a week and Saudi Arabia could resume Yanbu exports
US and Iranian officials met for three hours on the UN sidelines in talks Trump called very productive