ASX 200 Live Today - Wednesday, 16th September
The ASX 200 is trading around breakeven as REITs, Tech and miners weigh. Here are today's top stories.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Wednesday, September 16. Coverage has concluded for the day. Let us know how we can make it even better.
Morgan Stanley reiterates Overweight on James Hardie after New York investor day
[1:35 pm] The broker says the event supported its medium-term thesis of self-help driving above-market growth, even as the stock tumbles 5.0% today.
FY27 guidance reaffirmed on an ex-Europe basis, with sales of US$4.99-5.13bn and adjusted EBITDA of US$1.45-1.53bn, while FY27 free cash flow guidance was lifted to US$600m+ from US$500m+
The absence of a further EBITDA upgrade may have disappointed some, with Morgan Stanley noting the US housing backdrop has weakened as mortgage rates approach 7% and freight and diesel costs stay elevated
The new North American growth algorithm targets 4-7ppt organic sales growth above market with 35%+ EBITDA flow-through, driven by material conversion, commercial synergies and net price
Morgan Stanley sees the framework supporting medium and high-case FY29 EBITDA of US$2.4-2.7bn, implying roughly 19-35% upside to Visible Alpha consensus
Cost synergies of US$125m now expected by FY27, a year ahead of plan and under budget, with management lifting conviction on commercial synergies to "at least US$500m"
The US$980m Europe divestment adds around 150bp to group EBITDA margin after closing, with US$600m to debt reduction, a US$250m buyback authorised and net leverage targeted below 2.0x by 2QFY28
Company page: James Hardie (JHX)
Macquarie finds no structural issue behind Lottery Corp's jackpot drought
[1:11 pm] The broker ran 100,000 Monte Carlo simulations to test whether the run of small Powerball and Oz Lotto jackpots reflects anything beyond bad luck.
FY26 jackpot activity was a 1-in-46 year event across the industry, or 1-in-45 for The Lottery Corporation specifically
Oz Lotto was a 1-in-4 year event with no jackpots reaching A$50m, while Powerball was a 1-in-7 year event with none reaching A$100m
No evidence of jackpot fatigue, with similar volume distributions across equivalent jackpots, modest linear growth at lower levels and exponential acceleration above A$80m for Powerball and A$50m for Oz Lotto
Spot coverage sits around 16% for Powerball at jackpots under A$20m and approaches 40% at A$60m, with Oz Lotto around 18% at low levels and approaching 40% at A$30m
Price rises in Powerball in November 2025 and Oz Lotto in May 2022 had minimal volume impact, confirming favourable demand inelasticity
Target price of A$5.9
Note: the analysis supports mean reversion in jackpot activity over time, but Macquarie states it cannot determine when that will occur.
Company page: The Lottery Corporation (TLC)
Barrenjoey sees positive takeaways from South32's Hermosa site visit
[1:10 pm] The broker attended South32's investor visit to the Hermosa zinc project in Arizona.
The project remains on revised budget and timeline, with 80% of growth capital already invested, contracted or subject to final pricing, and US$230m of contingency still available
Complete spend of the revised US$3.3bn capex budget lands mid-CY28, with the last work packages covering plant and underground development, both expected to be priced before end-CY26
Management doesn't see capex as a top three risk, instead flagging underground infrastructure productivity, decline productivity and labour availability, with Barrenjoey viewing labour as the greatest given the low socio-economic setting
November 2027 remains the target for break-through to the Taylor orebody despite the decline slowing recently on expected water ingress
Hermosa is now fully permitted after last week's federal Notice to Proceed, enabling the final 11km of high-voltage power line, a new primary access road, a second tailings facility covering the 33-year mine life and additional drill sites
Objections have been lodged by the Centre for Biological Diversity and Patagonia Resource Alliance against the federal government rather than South32, with no impact on works unless an injunction is granted, which is not seen as likely
Expansion to 5Mtpa from 4.3Mtpa nameplate is viewed as the lowest-cost option at tens of millions with only state-level permit changes, mostly around particle and lead emissions, while going beyond 5Mtpa would require more capital and technical work
Company page: South32 (S32)
Energy stocks hit five-month highs
[12:17 pm] The S&P/ASX 200 Energy Index is up 2.6% and less than 2.5% away from taking out the 7 April high.
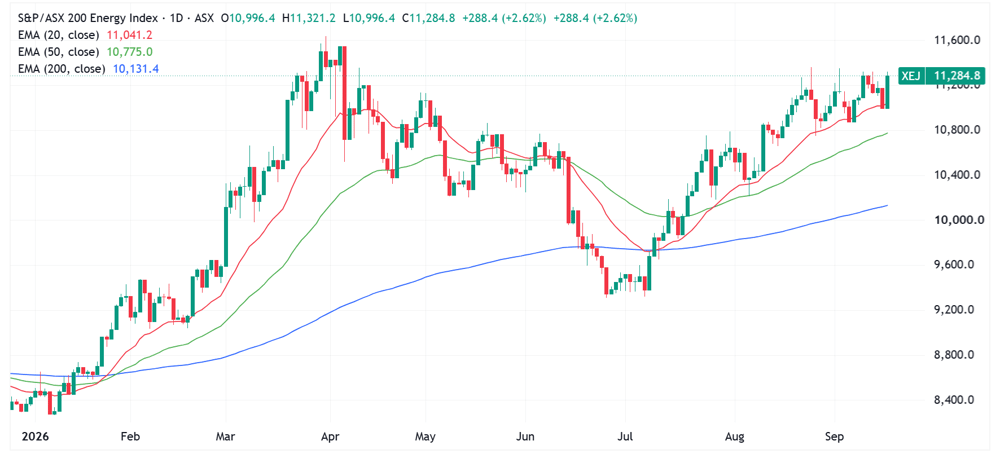
S&P/ASX 200 Energy Index daily chart (Source: TradingView)
Refiners, oil and gas names are trading broadly higher, while most coal names hover around breakeven.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
STX | Strike Energy | 4.5% | $0.12 | 0.0% | 9.5% |
WDS | Woodside Energy Group | 3.4% | $33.47 | 1.8% | 41.0% |
VEA | Viva Energy Group | 3.4% | $3.16 | 5.9% | 52.4% |
KAR | Karoon Energy | 3.0% | $1.91 | 4.1% | 24.0% |
BPT | Beach Energy | 2.9% | $0.90 | 1.1% | -23.5% |
ALD | Ampol | 2.6% | $43.32 | 6.3% | 35.7% |
STO | Santos | 2.3% | $8.75 | 2.9% | 41.6% |
WHC | Whitehaven Coal | 0.4% | $8.36 | -6.6% | 7.6% |
YAL | Yancoal Australia | 0.0% | $6.16 | -3.8% | 23.7% |
NHC | New Hope Corporation | -0.4% | $6.45 | 0.4% | 60.7% |
SMR | Stanmore Resources | -2.3% | $2.79 | -12.1% | 19.5% |
US and China discuss tariff cuts ahead of Trump-Xi summit
[12:08 pm] Both sides are weighing reciprocal reductions on energy, agriculture and manufacturing inputs, firming up prospects for an extension to the one-year trade truce.
Treasury Secretary Scott Bessent meets Chinese Vice Premier He Lifeng this weekend, reportedly in New York on Sunday, ahead of the Trump-Xi summit set for 24 September in Washington
Talks cover tariff cuts on American energy and agricultural goods, with next week's meetings also likely to yield an agreement to cut duties on Chinese inputs for manufacturers
The moves would run under an earlier plan for reciprocal cuts across roughly $30bn in trade, with most-favoured-nation rates applied to some items from China
A truce extension would remove one stumbling block for a world economy already dealing with wars in Iran and Ukraine, elevated oil prices and rising borrowing costs
AI competition remains a key friction point, after three US national security agencies accused Chinese firms including DeepSeek and Moonshot AI of extracting proprietary knowledge from American companies
Cofco representatives may join Xi's delegation, with more than a dozen firms under consideration for a CEO contingent, mirroring the Nvidia and Tesla executives Trump took to China in May
Source: Bloomberg
El Niño threatens to squeeze New Zealand dairy margins
[12:07 pm] DairyNZ has lifted its breakeven milk price forecast on expectations of a very strong El Niño, leaving farmers with a thin buffer over Fonterra's projected payout.
The breakeven milk price for 2026-27 is forecast at NZ$9.07 per kilogram of milksolids under a very strong El Niño, against Fonterra's currently projected payment of NZ$9.25
The national breakeven sits at NZ$8.62 before any unusual weather, rising to NZ$8.90 under a merely strong El Niño scenario
DairyNZ head of economics Mark Storey said the focus three months ago was the Strait of Hormuz and its impact on fuel, fertiliser and feed costs, with El Niño now a second challenge for pasture growth and feed supply
Drier conditions are expected in northern and eastern areas, slowing pasture growth in dairy-rich regions like Waikato and Taranaki and likely lifting feed costs while reducing milk production
Farmers enter the season well positioned after a profitable 2025-26 that delivered record production and strong global dairy prices, plus a one-off Fonterra payment from the Mainland Group sale that let many cut debt
Source: Bloomberg
Lithium stocks tumble, PLS nears year-to-date low
[12:02 pm] Chinese lithium carbonate futures are down 3.5% to 124,900 yuan a tonne, now down 12% in the past week and 40% off the 209,800 yuan high in early May.
The bellwether PLS Group has tanked 25% since 1 September, and just 3% away from making a fresh year-to-date low.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
PMT | Pmet Resources | -4.7% | $0.41 | -9.9% | -31.1% |
LTR | Liontown | -3.2% | $1.01 | -17.5% | -35.9% |
PLS | PLS Group | -2.8% | $4.14 | -17.5% | -1.4% |
VUL | Vulcan Energy Resources | -2.2% | $2.19 | -15.8% | -50.3% |
PAT | Patriot Resources | -2.0% | $0.05 | -3.8% | -7.4% |
IGO | IGO | -1.7% | $7.03 | -15.3% | -14.2% |
MIN | Mineral Resources | -1.6% | $53.45 | -16.0% | -1.8% |
EUR | European Lithium | -0.9% | $0.34 | -6.4% | 117.4% |
GL1 | Global Lithium Resources | -0.8% | $0.63 | -5.3% | -0.8% |
DLI | Delta Lithium | 0.0% | $0.17 | -5.7% | -25.0% |
CXO | Core Lithium | 0.0% | $0.36 | 0.0% | 29.1% |
AGY | Argosy Minerals | 0.0% | $0.03 | -11.4% | -74.2% |
INR | Ioneer | 6.4% | $0.12 | 11.4% | -36.8% |
Chinese fuel stockpiles slide, raising odds of fresh export curbs
[11:17 am] Falling domestic gasoline and diesel inventories could push Beijing to throttle clean product exports again, with knock-on effects for Asian buyers and crude prices.
Gasoline stockpiles at state-owned suppliers fell 2.9% last week to the lowest since 2022, with diesel holdings down 2.4% to a 15-month low, according to JLC International
Energy Aspects analyst Jianan Sun sees an increasing risk Beijing restricts monthly clean product exports to around 1.2m tons in the fourth quarter as the domestic market tightens
Clean product shipments had recovered to 2.55m tons in July after Beijing eased the curbs it imposed in the early weeks of the US-Iran war
Refiners were only allowed to resume exports on the condition they keep inventories at elevated levels, with the government strictly controlling export volumes
Independent teapot refiners have lost access to Iranian crude under the US blockade, pushing up premiums for African and Latin American barrels and raising the prospect of run rate cuts in coming weeks
Hormuz volumes remain well below pre-war levels, with the Saudi East-West pipeline closure and Houthi gains in Yemen now threatening Red Sea shipments
Source: Bloomberg
ASX 200 snaps back to breakeven
[10:58 am] The ASX 200 briefly rose 0.38% in early trade, but now back to around breakeven as miners struggle to bounce, while tech and real estate stocks trend lower.
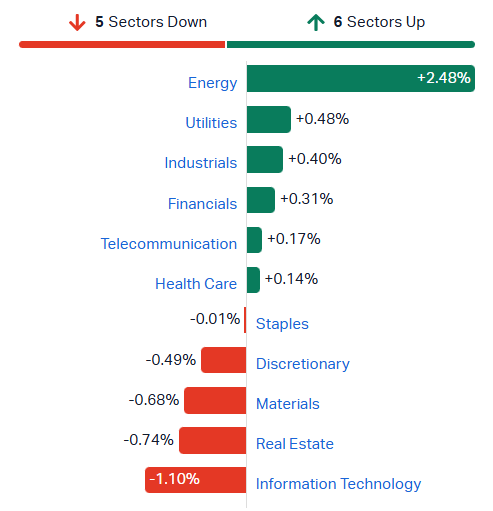
S&P/ASX 200 sectors (Source: Market Index)
Pengana International Equities settles litigation and appoints Antipodes
[10:54 am] The listed investment company has resolved court proceedings brought by its manager, clearing the way for its buy-back and a portfolio handover. The stock is up 9.2% in early trade to $1.12.
The settlement resolves Supreme Court proceedings commenced by Pengana Capital and provides a pathway to end PCG's Takeovers Panel application, without admission of liability by any party
Antipodes Partners has been appointed sub-investment manager, with the portfolio to transition to its Global Small and Mid-Cap strategy after the buy-back completes
Antipodes manages more than A$20bn globally and was recommended by the Independent Board Committee following the Strategic Review
Frank Gooch and Brendan O'Dea join the board immediately, with Geoff Wilson, Jesse Hamilton, Julian Martin and Brett Jollie resigning on 29 September and Gooch becoming interim chairman
Shareholders who have already tendered can withdraw all or part of their election until 5pm on 24 September, with the buy-back closing date unchanged at 21 September
PCG will not participate in the buy-back, while Wilson Asset Management intends to participate and retain no more than 2.69% of pre-buy-back issued capital
Company page: Pengana International Equities (PIA)
Top ASX 200 gainers
[10:44 am] Infratil rallies on a guidance upgrade, while energy stocks trade broadly higher, lifting the S&P/ASX 200 Energy Index by 2.3% and within 2.5% of the 7 April high.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
IFT | Infratil | 5.7% | $11.55 | -2.3% | 20.6% |
RWC | Reliance Worldwide | 4.5% | $4.53 | 6.5% | 16.0% |
VEA | Viva Energy Group | 3.9% | $3.17 | 6.4% | 53.1% |
CNI | Centuria Capital | 3.5% | $1.32 | 0.8% | -33.9% |
KAR | Karoon Energy | 3.2% | $1.92 | 4.4% | 24.4% |
WDS | Woodside Energy | 3.1% | $33.34 | 1.4% | 40.5% |
BPT | Beach Energy | 2.9% | $0.90 | 1.1% | -23.5% |
STO | Santos | 2.5% | $8.77 | 3.1% | 41.8% |
ALD | Ampol | 2.3% | $43.20 | 6.0% | 35.3% |
ASB | Austal | 2.0% | $4.26 | -10.2% | -36.7% |
Top ASX 200 losers
[10:44 am] Life360 gives back yesterday's gains, James Hardie tanks on an FY27 free cash flow upgrade (but sales and EBITDA guidance left unchanged) and miners open broadly lower.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
360 | Life360 | -6.1% | $19.26 | -3.7% | -40.2% |
JHX | James Hardie | -5.4% | $37.22 | -9.8% | 20.1% |
TLX | Telix Pharmaceuticals | -5.0% | $16.86 | 2.6% | 49.9% |
MI6 | Minerals 260 | -4.5% | $0.84 | 2.4% | 100.0% |
4DX | 4DMedical | -4.3% | $3.58 | 6.9% | -10.5% |
BGL | Bellevue Gold | -3.0% | $1.47 | -9.5% | -13.0% |
CMM | Capricorn Metals | -2.7% | $14.36 | -9.0% | 2.5% |
PLS | PLS Group | -2.5% | $4.16 | -17.2% | -1.1% |
LTR | Liontown | -2.4% | $1.02 | -16.8% | -35.4% |
CYL | Catalyst Metals | -2.4% | $6.30 | -5.3% | -14.7% |
Reliance Worldwide signs binding scheme deed with Brookfield
[9:57 am] The plumbing products maker has agreed to a US$3.38 per share cash takeover and kicked off a go-shop process to test for rival bidders.
Cash consideration of US$3.38 per share implies A$4.75 at the AUD/USD rate of 0.7122 on 15 September, with shareholders able to elect delivery in either currency at implementation
The offer represents a 31.5% premium to the undisturbed last close, 32.7% to the three-month VWAP and 43.0% to the six-month VWAP
Enterprise value of about US$2.9bn implies an EV/FY26 EBITDA multiple of roughly 12.1x post-AASB16, or US$2.8bn and 12.9x pre-AASB16
The deal follows a series of unsolicited proposals from Brookfield in April and May at A$4.15, A$4.25 and A$4.50, lifted to A$4.75 in early August after an eight-week due diligence period
A go-shop provision runs until 15 October, allowing RWC to solicit alternative proposals and terminate the deed to pursue one, subject to Brookfield's matching right, with matching break fees of US$25.3m either way
The board unanimously recommends the scheme absent a superior proposal, with the scheme booklet and Grant Thornton's independent expert report due in November and implementation expected in Q1 2027
Company page: Reliance Worldwide (RWC)
Talga signs non-binding anode supply LOI with Germany's EAS Batteries
[9:55 am] The graphite developer has agreed a pathway toward a five-year European supply deal from its Vittangi project in Sweden.
Talga is a battery materials company advancing the mine-to-battery Vittangi Anode Project in northern Sweden, producing Talnode graphite anode products
The LOI is expressly non-binding other than confidentiality and governing law, with no obligation on either party to buy, sell, reserve capacity or provide financing
Milestones target April 2027 for a binding terms sheet and a definitive five-year Supply Agreement by July 2027, with extension potential
Pricing would be euro-denominated under a mutually agreed mechanism, with potential volumes still under discussion
Qualification work covers product specifications, quality requirements and supply-chain, human rights and environmental due diligence, including FEOC-free status and CO2 footprint
EAS is a German specialist manufacturer of custom large-format cylindrical lithium-ion cells with 30 years' experience across maritime, aerospace, defence, automotive and industrial applications, with both parties agreeing to support each other's project financing
Company page: Talga Group (TLG)
Global Lithium doubles Manna NPV via Nova plant conversion
[9:28 am] The integration study has confirmed a cheaper, faster development path after GL1 agreed to buy IGO's Nova operations in July.
Post-tax NPV8 of A$946m, up A$474m or 100% on the A$472m in the December 2025 DFS, with post-tax IRR of 120% against 25.7%
Pre-production funding cut 59% to A$180.1m from A$439.1m, with payback of 11 months from production start versus 3.5 years in the DFS
Probable Ore Reserve up 8% to 21Mt at 0.89% lithium oxide from 19.4Mt at 0.91%, supporting a 13-year mine life
Life-of-mine concentrate production of 2,684.3kt, averaging 257kt of SC5.5 annually over the first seven years
First DSO shipment targeted for May 2027 ahead of first spodumene concentrate in mid-2027, with FID on track for the December quarter
Ore will be hauled 135km from Manna to the modified 1.8Mtpa Nova flotation plant, removing the greenfield concentrator that was the single largest capital item in the DFS, with 70% of concentrate committed to Lopal and Canmax
Company page: Global Lithium Resources (GL1)
Explorers wrap: high-grade hits from Pantoro, Turaco, Toubani and Barton
[9:27 am] A busy morning of drilling results across gold, silver and tin, plus a planning milestone for Bowdens.
Pantoro Gold extended high-grade mineralisation at the Racetrack discovery within Norseman, with hits including 11.12m at 5.48g/t from 488.6m, confirming roughly 900m of strike to 600m depth and an exploration decline starting in the December quarter
Turaco Gold returned results from Begnopan at the Afema project in Côte d'Ivoire including 11m at 4.33g/t from 72m and 24m at 3.30g/t from 105m, from 13,000m of drilling aimed at lifting confidence in the 260koz maiden resource
Toubani Resources hit bonanza grades at Foroko within Mali's Kobada project, including 28m at 8.86g/t from 188m, 3km from a plant under construction with first gold scheduled for Q3 2027
Barton Gold reported Tunkillia starter pit assays including 21m at 3.62g/t from 57m and 50m at 1.45g/t from 62m, with gold and silver resource updates to follow and the PFS on track for Q1 CY27
Dart Mining assayed 3.96% tin, 165ppm tantalum and 197ppm niobium from a grab sample at the historic Walwa tin mine in Victoria, with maiden diamond drilling scheduled for October
Silver Mines cleared a planning hurdle at Bowdens, with the IPC hearing resuming 14-15 October and a determination now expected by 9 December 2026
Company pages: Pantoro Gold (PNR), Turaco Gold (TCG), Toubani Resources (TRE), Barton Gold (BGD), Dart Mining (DTM), Silver Mines (SVL)
Infratil lifts FY27 guidance on CDC data centre contract wins
[9:02 am] The infrastructure investor has upgraded earnings guidance at its Sydney investor day as data centre demand drives portfolio growth.
Proportionate FY27 EBITDAF guidance lifted to NZ$1,320-1,420m from NZ$1,300-1,400m, a 1.5% upgrade at the midpoint, with guidance for the other operating businesses unchanged
CDC Data Centres raised its FY27 EBITDAF range to A$710-750m from A$680-720m, a 4.3% midpoint upgrade, reflecting another 70MW of signed contracts, operating cost savings and non-recurring managed services delivery
CDC has 350MW of deployed capacity and 1.1GW of contracted capacity expected to deliver A$2.2bn of EBITDAF when fully deployed, with the new contracts landing across late FY27 and early FY28
Data centre investments now make up just over half of Infratil's NZ$22bn total asset value, with CEO Jason Boyes flagging CDC, Kao Data in the UK and Longroad Energy all benefiting from AI demand
Longroad Energy has acquired a 2.8GW project, lifting development cadence to about 2.5GW a year over 2027-2029 and total fleet to 14GW, and has identified a 10GW pipeline of solar sites for potential data centre co-location
A sales process is underway for Qscan, the radiology business, with the balance sheet backed by a BBB+ credit rating and ongoing portfolio refinement
NZX-listed Ifratil shares are up 5.0% this morning to N$14.30.
Company page: Infratil (IFT)
Paragon Care launches buy-back and employee trust purchase
[9:02 am] The healthcare products distributor has flagged two separate on-market share purchase programs.
The buy-back covers up to 82,765,269 shares, the maximum permitted under the 10/12 limit and roughly 5% of current shares on issue
At the 15 September closing price of $0.13, the aggregate cash cost of the buy-back would be about $10.8m
Timing is tied to the FY26 result, with the buy-back to commence on or shortly following the release, subject to market conditions, trading volumes and the right to suspend or terminate
Separately, the ParagonCare Employee Share Trust has been instructed to acquire up to 23,900,401 shares on market to satisfy future vesting under the Employee Incentive Plan
Trust purchases begin on or shortly after the announcement at no more than 5% above the five-day VWAP, with ASX to be notified when purchasing ceases or completes
No shareholder approval is required as the buy-back sits within the 10/12 limit under the Corporations Act
Company page: Paragon Care (PGC)
James Hardie 2026 Investor Day highlights
[8:56 am] Management used its New York investor day to reaffirm FY27 guidance, lift the free cash flow target and lay out a growth algorithm it says works regardless of housing.
The presentation was held at 8:30 am ET, so right before the US market opened. NYSE-listed James Hardie shares finished the session 4.4% lower.
On the growth algorithm: "what we are targeting is organic growth of 4%-7%. That is not market-dependent... one year, one may be more than the other, but in balance, we are confident that we can get to that 4%-7%"
On cost synergies: "We were targeting $125 million of cost synergies over three years, and we are excited to update you that we plan to exit the FY27 run rate of $125 million by the end of FY27, which is one year ahead of our original schedule"
On free cash flow: "Our FY27 guide expected roughly $500 million of free cash flow. We are raising that target to roughly $600 million now based on the cash the business is generating this year... We anticipate 40% moving forward for free cash flow conversion"
On the Europe divestiture: "The agreed sale price is roughly $980 million on a USD basis, which represents a 12x multiple on 2026 EBITDA... We expect this divestiture to be accretive to the overall margin by roughly 150 basis points, and we plan to use the proceeds, roughly $600 million for debt paydown, and roughly $250 million share repurchase"
On the housing backdrop: "our guidance does not assume any macro housing recovery, and we remain cautious on housing until we see key indicators meaningfully improve. In addition, we've seen no relief on fundamental costs, including freight and diesel"
On spare capacity: "You can see 70% on the fiber cement, 65% in decking and 60%. We've already got assets on the ground ready for that growth... We're ready to enable that share growth, without the need for near-term investment"
On Australia and New Zealand: "are you committed to Australia and New Zealand? Yes, absolutely... We like this business. It is our most profitable business. We have good market share there"
On US index inclusion: "An average of 23% of S&P 500 shares are held via US index today, and only roughly 2% for James Hardie... We are now in the MSCI Small Cap Index, as well as the S&P Completion Index"
Company page: James Hardie (JHX)
Auric picks up Burbanks plant infrastructure for $1.2m
[8:51 am] The WA gold junior has secured second-hand processing equipment at a heavy discount to replacement cost, keeping its restart timeline intact.
Auric Mining is a WA gold producer working to re-establish its own processing plant at the Burbanks project near Coolgardie, having previously relied on third-party toll treatment
The package cost $1.2m against an estimated replacement cost of $15m to $20m, with the all-in cost of delivering it to site expected to be substantially below that figure
The NSW-based plant supports the initial 600ktpa Burbanks CIL design and comprises a complete three-stage crushing circuit, fine ore bin and conveyors, material handling equipment and shedding, and milling structure
Associated spare parts and consumables are included, along with two complete spare cone crushers and one spare jaw crusher, adding operational redundancy
Interquip will start removal and relocation in Q4 2026, with all equipment on site at Burbanks ready for installation in Q1 2027 and plant re-establishment still targeted for Q1 2028
Auric has a market cap of approximately $43 million vs. $38m cash at 30 June 2026, no debt and no hedging. It reports off-cycle, with the latest 1H26 result (to 30-Jun) delivering operating cash flow of $33.7m on pre-tax profit of $28m.
Company page: Auric Mining (AWJ)
Tungsten Mining confirms Watershed flowsheet with high-grade concentrate
[8:50 am] The junior has produced saleable tungsten concentrate from its north Queensland project and shipped samples to potential offtake partners.
Tungsten Mining is a WA-based developer advancing the Watershed tungsten project in far north Queensland, with tungsten used in cutting tools, alloys and defence applications
Metallurgical testwork produced concentrate grading up to 65.9% tungsten trioxide, confirming the ability to deliver a +50% or +65% tungsten trioxide product
The go-forward flowsheet is confirmed using conventional ore sorting, gravity and flotation beneficiation, underpinning the Definitive Feasibility Study
The DFS remains on track for October 2026, allowing a Final Investment Decision on Watershed during the fourth quarter of 2026
Multiple commercial-grade samples have been dispatched to potential downstream offtake partners, with commercial terms under negotiation
Further bulk testwork is in progress on a larger 134t pilot sample, while a 16.9kg rock chip sample from the bulk sample area assayed 64.3% tungsten trioxide
Company page: Tungsten Mining (TGN)
Wiluna Mining lines up $180m IPO for ASX return
[8:44 am] The West Australian gold producer is targeting a relisting in late October, two and a half years after being kicked off the bourse.
Argonaut Securities and Barrenjoey have asked fund managers to bid at 65c to 85c a share, implying a market capitalisation of $471.7m to $539.4m depending on the final price
CEO Victor Rajasooriar leads a roadshow from 21 September to mid-October, with the company potentially rejoining the ASX around 26 October
Of the $180m raised, $40m repays debt owed to mining contractor Byrnecut and $45.6m is reserved for working capital, with the rest going to exploration
Exploration is the near-term focus after a carbon-in-leach tank ruptured at the processing plant in July and halted mining operations
The register is far from vanilla, a legacy of the 2022 voluntary administration, with lender Deutsche Balaton entitled to shares at a 22.5% discount to the IPO price and three sets of convertible notes converting at 10% to 25% discounts
The asset holds 7m ounces of gold, paired with a 2.1mtpa processing facility, a gold concentrator, a gas-fired power station and a 300-person camp
Source: AFR
JPMorgan maps five Fed scenarios for the S&P 500
[8:42 am] JPMorgan has set out how US equities could react to each possible outcome from the Fed's next decision.
JPMorgan runs this "how US equities could react" series ahead of CPI, Fed meetings and other major catalysts fairly regularly. The S&P 500 rarely lands where the scenarios say it will, so take it as illustrative rather than a forecast.
No hike would likely add upward pressure to longer-dated bond yields as inflation expectations rise, with the S&P 500 falling 1.25% to 1.75%.
A 25 basis point hike with no guidance is the consensus view on Wall Street and would contain the back end of the yield curve, lifting the S&P 500 0.25% to 0.75%.
A 25 basis point hike that removes 2025 eases could be greeted even more positively, with Fed Chair Warsh flagging hikes in October and December rather than December and March worth 0.50% to 1% on the S&P 500.
R-star is the neutral real interest rate that satisfies both full employment and stable inflation.
A 25 basis point hike with no R-star guidance could have traders concluding the current rate is too accommodative and pricing a half point move at any meeting this year, sending the S&P 500 down 0.25% to 1%.
A 25 basis point hike framed around crushing inflation, with Warsh suggesting the fed funds rate needs to be materially higher, would repeat the 2022/2023 hiking cycle and could end the bull market, with the S&P 500 down 1% to 2%.
Fed set to hike for the first time since 2023
[8:42 am] Markets have all but locked in a quarter-point increase on Wednesday, putting Chair Kevin Warsh at odds with the White House weeks out from the midterms.
Futures traders assign better than a 92% chance to a hike at this week's FOMC meeting, which would lift the funds rate from its current 3.5% to 3.75% target range, with December odds above 75%
August CPI showed headline inflation at 3.4% and core at 2.4%, with Warsh signalling at Jackson Hole the Fed would move absent more convincing evidence inflation was heading back to 2%
The July meeting went 9-3 in favour of a hold, with Hammack, Kashkari and Logan dissenting for a hike, meaning at least four more members need to cross over on Wednesday
Waller and Williams have both signalled little urgency, with Waller questioning on 3 September what a single 25bp move would actually achieve for inflation
Goldman economist David Mericle sees no strong economic case for hiking and attributes the overshoot to one-off factors, but revised to a hike call on the weight of market pricing
An updated dot plot lands alongside the decision, with the June projections showing nine officials favouring at least one increase before year-end and Warsh not submitting his own
Source: Quartz
Brent tops US$108 as Saudi export route seizes up
[8:40 am] Attacks on Saudi Arabia's westward crude route have pushed oil to four-month highs while the US blockade of Iran grinds on.
Loadings suspended at Yanbu, Saudi Arabia's Red Sea export terminal, after Riyadh told European customers some late-September cargoes would be cancelled
The 1,200km East-West pipeline that carries 7m barrels a day to the Red Sea was shut after a Houthi drone strike, though US Energy Secretary Chris Wright expects a restart within days
Goldman Sachs strategist rigsby said the infrastructure attacks mark a meaningful escalation and raise the probability of the bank's upside scenario of Brent above $120
The US naval blockade now involves about 22 ships at roughly $32.5m a day, with costs topping $7.1bn since January and the CBO putting the total war bill at $38bn as at 1 August
Iran exported about 2m barrels a day pre-war, close to 2% of global supply, with satellite images showing almost no tankers at Kharg Island and domestic inflation running above 80%
BofA survey shows fund managers trimming equity bullishness
[8:36 am] Bank of America's latest global fund manager survey has investors pulling back from risk assets as bond market fears build ahead of the Fed.
A net 49% of fund managers are overweight global equities, down from 56% last month, with a disorderly rise in bond yields now viewed as the biggest tail risk to the market
Cash holdings rose to 3.9% of portfolios, though strategist Michael Hartnett notes they remain at levels that flash a sell signal for risk assets
A net 48% of fund managers are underweight bonds, the most since May 2022, with nearly half expecting no impact on yields from the Treasury's buyback program
A net 25% of participants said monetary policy is too stimulative, the highest since 2022, with swaps traders pricing about 94% odds of a Fed hike on Wednesday
The share expecting a double-digit increase in corporate earnings over the next year was the highest since August 2021, with Hartnett saying the sole worry is companies over-investing capital
About 44% of investors see a split Democratic House and Republican Senate as the most likely midterm outcome, while nearly half expect yields to rise and stocks to fall on a Democratic sweep
Source: Bloomberg
Good morning!
[8:26 am] ASX 200 futures are up 31 pts (+0.35%). Here's what happened overnight:
Wall Street fell for a second session but off worst levels as small gains for chipmakers cushioned the benchmarks
S&P 500 (-0.45%), Nasdaq (-0.78%), Dow (-0.63%), Russell 2000 (-0.76%)
US 10-year Treasury yield crossed 5.0%, the highest since 2007 as futures moved to price better than a 90% chance of a Fed rate hike on Wednesday, which would be the first since July 2023
Brent rose almost 2% to US$108.49 as Saudi Arabia's East-West pipeline remains offline, keeping roughly 4% of global supply at risk
Fed decision at 4:00 am AEST tomorrow morning, the US 2-year yield is currently ~100 bps above the federal funds rate of 3.50–3.75%, lots of possible scenarios here (a hike is near-certain but will Warsh opt for a dovish hike or guide to a new hiking cycle)