ASX 200 Live Today - Wednesday, 12th August
The ASX 200 is trending lower, with sectors like Discretionary, Telcos, Staples and Real Estate all down more than 1%.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Wednesday, August 12.
The Live Blog has wrapped up for today.
Reporting season is heating up and we've got you covered. Our reporting season calendar has over 250 stocks plus earnings and dividend estimates.
Best of Livewire: reporting season insights and Morgan Stanley's big calls
[1:09 pm] A roundup of the best reads across markets, earnings and asset allocation from our friends at Livewire.
The market punished Life360. Its CEO says the growth story is far from over:
Vishal Teckchandani speaks with CEO Lauren Antonoff after shares fell around 20% post-result, on why moderating MAU growth obscures record member additions and how international, pets, ageing parents and AI drive the path to 150 million users
CBA sees profit and cash up - does it change the equation for investors?: Tom Stelzer unpacks CBA's FY26 result with ClearBridge's Matthew Davison, who holds an underweight on a stretched valuation and flags softening housing credit, rising problem loans and margin competition risks post-budget
Morgan Stanley's 5 big investment calls for the rest of 2026: The investment bank is staying overweight equities with the US as top pick, backing AI infrastructure and power, Japan and Korea, copper as its top commodity, and a near-maximum underweight on Australia
The AI bubble meets reporting season: Forager's Steve Johnson argues US earnings show investors turning more discerning, rewarding Microsoft and Amazon for cash-backed demand while punishing Alphabet and Meta on spending, in an environment he likens to 2000 more than the GFC
Car Group posts record revenue and profit: Chris Conway breaks down CAR Group's FY26 result with Auscap's Will Mumford, who rates it a buy on compelling valuation, strong offshore growth and an audience lead that widened despite AI disruption fears
Retail stocks under pressure
[12:24 pm] The discretionary sector is under pressure today after Premier's FY26 trading update set a downbeat tone for retailer reporting season.
“The discretionary retail conditions in 2H26 have been very challenging, in particular during the latter months of 2H26. Given this environment, the Board believes the FY26 Premier Retail Underlying EBIT result to be a creditable outcome being down 3.8% on the guidance given in March 2026," said Premier Chairman Solomon Lew.
This echoes some of the prior commentary from Myer (27-Jul), which noted:
Despite mixed trading month-to-month for Myer Group, including a strong recovery in May, these impacts have compounded in June and July, significantly constraining household budgets and consumer spending.
This has been further compounded by a warmer than average start to winter in most of Australia’s major cities.
Myer Group sought to stimulate demand by increasing promotional activity and whilst Value Creation and Integration Synergies have supported performance, it has not been sufficient to offset weak underlying consumer spending.
The S&P./ASX 200 Discretionary Index is down 1.3%, but still up a massive 23% since the 12 May low.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
PMV | Premier Investments | -8.6% | $12.29 | -7.6% | -11.3% |
LOV | Lovisa | -4.5% | $24.99 | -2.9% | -14.7% |
SUL | Super Retail Group | -4.3% | $13.28 | -2.2% | -17.0% |
APE | Eagers Automotive | -3.8% | $23.53 | -1.9% | -3.8% |
GYG | Guzman Y Gomez | -3.1% | $24.06 | -3.8% | 10.1% |
ARB | ARB Corporation | -2.8% | $19.68 | -4.4% | -38.1% |
BRG | Breville Group | -2.5% | $33.84 | -0.4% | 14.7% |
FLT | Flight Centre | -2.4% | $13.22 | -0.1% | -11.8% |
NCK | Nick Scali | -2.3% | $16.92 | 3.2% | -28.0% |
WEB | Web Travel Group | -2.1% | $3.49 | 2.5% | -27.1% |
HVN | Harvey Norman | -1.9% | $4.91 | -1.7% | -29.6% |
LNW | Light & Wonder | -1.8% | $127.56 | 6.6% | -17.7% |
JBH | JB Hi-Fi | -1.7% | $82.17 | 0.0% | -14.6% |
DMP | Domino's Pizza | -1.7% | $19.41 | -2.9% | -7.7% |
ALL | Aristocrat Leisure | -1.6% | $64.30 | -1.7% | 11.3% |
CKF | Collins Foods | -1.3% | $8.08 | -3.7% | -23.7% |
QAN | Qantas Airways | -0.8% | $10.04 | -3.5% | -3.5% |
WES | Wesfarmers | -0.7% | $88.79 | -1.9% | 9.5% |
SNL | Supply Network | -0.6% | $35.03 | 0.5% | 8.0% |
TLC | Lottery Corporation | -0.6% | $5.42 | 0.0% | 5.2% |
HLO | Helloworld Travel | -0.3% | $1.55 | -0.3% | -18.5% |
VGN | Virgin Australia | -0.2% | $2.74 | -4.7% | -22.1% |
TAH | Tabcorp | 0.8% | $0.91 | 4.8% | -6.5% |
Codan reaffirms FY26 guidance, shares surge back towards all-time highs
[12:13 pm] Codan reaffirmed its FY26 guidance at an investor presentation this morning, with the stock currently up 8.3% ($44.16%) and within 1% of all-time highs.
FY26 EBIT guided to approximately $235m, up more than 60% on FY25
FY26 NPAT guided to approximately $170m, also up more than 60% on FY25
Communications revenue growth expected at the top end of the 15-20% range on strong defence demand for unmanned systems amid geopolitical tensions, with Zetron 2H revenue broadly in line with 1H
Communications segment profit margin expected to reach 30% for FY26 on revenue growth and operating leverage
Minelab 2H revenue tracking ahead of a strong 1H, supported by a favourable gold price and recent product releases
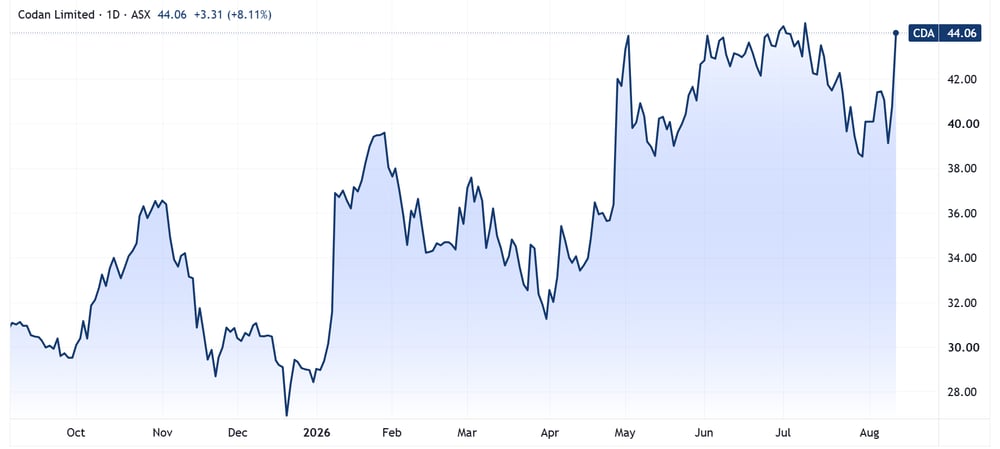
Codan 12-month price chart (Source: TradingView)
ASX 200 slips to session lows with only Utilities higher
[11:47 am] The benchmark is down 0.58% on very weak breadth, with Utilities the sole sector in the green.
S&P/ASX 200 down 0.58%, trading at session lows, with 141 constituents (70%) in the red and every sector bar Utilities lower
Discretionary (-1.1%) is among the hardest hit after Premier Investments flagged FY26 underlying EBIT of circa $176m, down 3.8% on the $183m guidance given 20 March
Adding to the gloom, used-car refurbisher and dealer Carma noted in a trading update that used car market conditions deteriorated from March through June on higher fuel prices and broader macroeconomic pressures
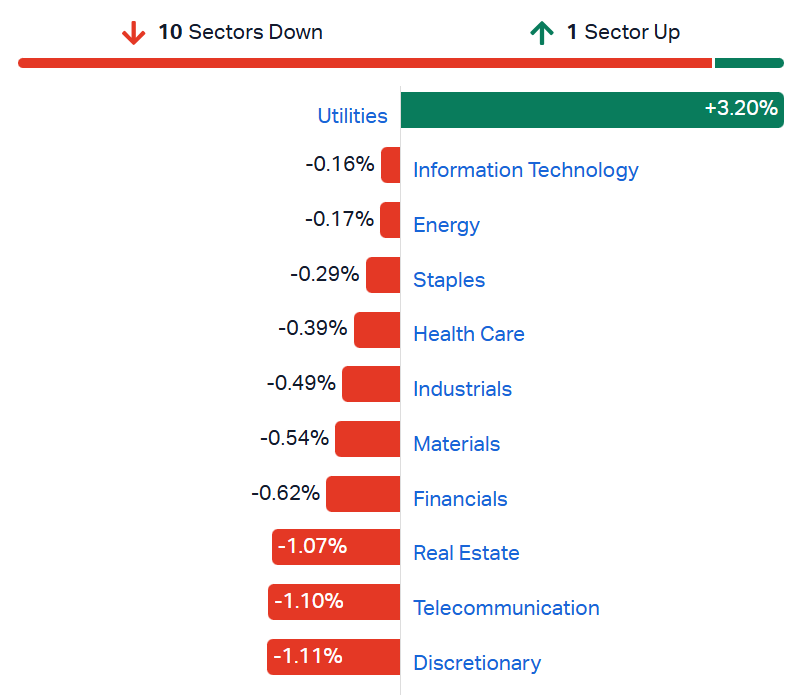
S&P/ASX 200 sectors (Source: Market Index)
Australian household spending and savings as slowing
[11:40 am] One of my favourite slides from the CBA FY26 results presentation (pg 127) captures a broad slowdown in Australian household activity, with spending easing across both essentials and discretionary categories and savings falling sharply for five of the six key age groups.
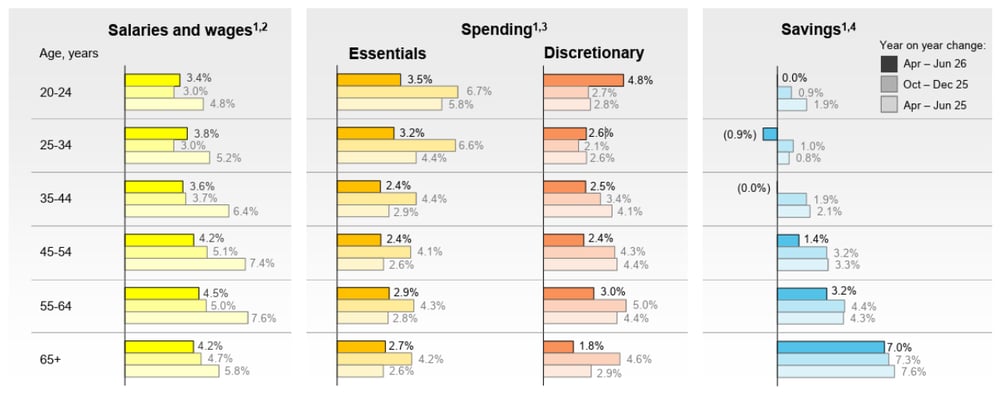
Source: CBA | 1. Per customer. For salary and wages 13 weeks to end of quarter, for spending 13 weeks to 28 Jun 2026, 4 Jan 2026 and 29 Jun 2025, for savings the average balance as at end of quarter. Consistently active card customers and CBA brand products only. 2. Paid into CBA transaction accounts, represents customers with payments identified as salary and wages after PAYG but before net tax return. Excludes government benefits and gig economy. 3. Spending based on consumer debit and credit card transactions data (excluding StepPay). 4. Includes all forms of deposit accounts (transaction, savings and term) and home loan offset and redraw balances. Trimmed mean excluding top and bottom 5% of customers within each age band.
Top ASX 200 gainers and losers
[10:41 am] Alcoa tops the leaderboard after aluminium prices ticked 0.8% higher overnight to US$3,348 a tonne (now up ~4.5% in the last five sessions). AGL and Suncorp rally on better-than-expected FY26 results, while Helia continues to trend higher (1H26 result featured a 16 cps ordinary plus 27 cps special dividend, equal to ~7.3% yield at today's prices).
On the flip side, Seek is tanking after its FY27 guidance came in well-below market expectations. Premier is also driving the broader retail sector lower, after its preliminary FY26 result fell short of its prior March guidance.
Ticker | Company | % Chg | Price |
|---|---|---|---|
AAI | Alcoa Corporation | 4.93% | $76.81 |
AGL | AGL Energy | 4.25% | $8.58 |
CDA | Codan | 4.12% | $42.43 |
SUN | Suncorp Group | 3.99% | $19.30 |
HLI | Helia Group | 3.90% | $5.86 |
ORG | Origin Energy | 2.70% | $11.24 |
ARF | Arena Reit | 2.68% | $2.30 |
CYL | Catalyst Metals | 2.07% | $6.65 |
ABB | Aussie Broadband | 1.82% | $5.03 |
MP1 | Megaport | 1.71% | $20.26 |
Ticker | Company | % Chg | Price |
|---|---|---|---|
SEK | Seek | -16.55% | $13.41 |
PMV | Premier Investments | -6.99% | $12.50 |
IPX | Iperionx | -4.17% | $3.57 |
LOV | Lovisa | -3.93% | $25.15 |
S32 | South32 | -3.70% | $4.95 |
APE | Eagers Automotive | -3.21% | $23.69 |
MFG | Magellan Financial Group | -3.09% | $10.68 |
NCK | Nick Scali | -2.97% | $16.81 |
SUL | Super Retail Group | -2.96% | $13.46 |
BSL | Bluescope Steel | -2.86% | $33.93 |
Dateline ordered by US court to halt Colosseum operations, shares crash 40%
[10:32 am] A preliminary injunction requires the miner to pause work at its flagship rare earths project pending resolution of the NPCA proceedings. The stock is currently down 40% to 7.5 cents.
US District Court issued a preliminary order on 10 August requiring Dateline and subsidiary Colosseum Rare Metals to halt operations at the Colosseum Project in an orderly manner until the injunction is lifted or a final judgment is delivered
The order stems from an NPCA motion challenging the National Parks Service's 2025 acknowledgement of the mine's existing plan of operations, which both Dateline and the US Department of Justice defended
Company is considering its options, including a potential appeal, and stresses the order is not a final judgment on NPCA's claims, with mining able to resume once compliance requirements are met
Company page: Dateline Resources (DTR)
Amotiv's in line FY26 result overshadowed by CEO exit
[10:29 am] Amotiv's FY26 result on Tuesday landed broadly in line with guidance and expectations, with underlying earnings holding up despite a soft domestic. Shares closed down 13.5% after touching an intraday low of 16.9%, with the announcement that CEO Graeme Whickman would step down later in the year, without a named successor.
JPMorgan retained Overweight, lowered target from $9.70 to $9.30, expecting subdued domestic conditions to persist and flagging cost inflation as the key margin headwind, though pricing action should offset the pressure and valuation looks undemanding versus history.
Macquarie retained Outperform, lowered target from $11.90 to $11.60, seeing a resilient result and viewing offshore growth and pricing as supporting margin recovery, with the succession process the key swing factor and the low multiple still attractive.
Stocks on the move: Earnings season drives sharp swings
[10:14 am] A slightly busier day of FY26 results sent reporting stocks in both directions, with Bravura the standout gainer and SEEK the heaviest faller.
Bravura Solutions (+12.1%): underlying NPAT of $63.1m beat ests by 16% and rose $38.7m on FY25, though cash EBITDA of $77.1m missed by 8%, offset by a $50m buyback, new $100m HSBC facilities and a 15c final dividend
AGL Energy (+5.1%): underlying NPAT of $631m missed by 1% and revenue was in line, but FY27 underlying NPAT guidance of $470-670m sat 3% above consensus at the midpoint, with the final dividend lifted to 26c
Suncorp (+2.5%): cash earnings of $1.04bn came in line and NPAT of $1.03bn beat by 2%, with underlying earnings up 4.5%, funding a 10c special dividend and a fresh $250m buyback despite hazard costs $254m above allowance
Commonwealth Bank (flat): cash NPAT up 7% to $10.98bn beat by 1%, growing at or above system across all five core domestic product categories for the first time in 15 years, with a $5.05 full-year dividend
Computershare (-2.0%): management EPS up 7% to US145.2c came in line and the final dividend rose 35%, but FY27 EPS guidance of around 6% growth undershot Macquarie's 7.2% forecast, prompting profit-taking
Premier Investments (-8.7%): flagged FY26 underlying EBIT of circa $176m, down 3.8% on March guidance, on tough discretionary conditions, and exited Peter Alexander's three UK stores
SEEK (-14.7%): FY26 adjusted NPAT of $199.1m beat by 1%, but FY27 adjusted NPAT guidance of $185-215m landed 13% below consensus at the midpoint, with revenue and EBITDA guidance also short
Karoon sanctions Who Dat East development in the Gulf of America
[9:43 am] The joint venture reached a final investment decision on the low-cost tie-back, with first production targeted for the second half of 2028.
Who Dat East JV, operated by LLOG, sanctioned the one-well development, with first production expected in 2H28 at an initial rate of about 5,900 boepd net to Karoon on an NRI basis (45% liquids, 55% gas)
Capital cost of US$155-165m net to Karoon, of which US$15-20m falls in 2H26
Expected to deliver an IRR above 20% at mid-case
Development comprises completion of the 2024 discovery well, a 29km pipeline to the Who Dat FPS, subsea controls and minor FPS upgrades, using existing infrastructure and routes to market
Company page: Karoon Energy (KAR)
Bravura beats on profit, launches $50m buyback
[9:40 am] The software group posted a sharp lift in underlying earnings and unveiled fresh capital returns, though cash EBITDA fell short of estimates.
Underlying revenue up 9.6% to $283.6m vs $283.0m ests (in line)
Underlying cash EBITDA up 131% to $77.1m vs $84.0m ests (8% miss)
Underlying NPAT up 63% to $63.1m vs $54.4m ests (16% beat)
Final dividend of $0.15 per share unfranked, comprising an 8.31c ordinary and 6.69c special dividend
Ended the year with $50.3m cash and no debt, entering new HSBC facilities of up to $100m
Launching an on-market buyback of up to $50m over 12 months from 31 August
FY27 revenue guided to $280-300m vs $289.6m ests (in line at midpoint) and cash EBITDA to $84-94m vs $89.9m ests (in line at midpoint)
Company page: Bravura Solutions (BVS)
Computershare grows management EPS 7% and lifts final dividend 35%
[9:37 am] The registry group beat its upgraded guidance, with earnings momentum building through the year and a stronger final payout.
Revenue up 3% year-on-year, with growth in client-paid fees and strong event and transactional revenues
Management EBIT (incl margin income) of US$1.20bn vs US$1.20bn ests (in line), EBIT ex MI up 8% with margins above 18%
Management EPS up 7% to US145.2c vs US145c ests (in line)
Margin income of US$749m vs US$734m Macquarie est (2% beat), aided by interest rate hedging offsetting rate cuts
Final dividend up 35.4% to A$0.65 per share unfranked vs A$0.62 Macquarie est (5% beat)
FY27 management EPS guided to grow around 6%, vs. Macquarie's forecast of 7.2% in actual currency or 6.5% constant currency
Company page: Computershare (CPU)
Pro Medicus wins 7-year, $23m contract with St. Luke's Health System
[9:30 am] The imaging group added another cloud-based Visage 7 client spanning the health system's 10 medical centres across three states.
Signed a 7-year, $23m contract with Idaho-based St. Luke's Health System for Visage 7 Viewer and Visage 7 Workflow
Cloud-based implementation on a transaction-based licensing model with potential upside
Go-live targeted for Q1 of CY27, with rollout planning to begin immediately
Company page: Pro Medicus (PME)
FleetPartners draws three-way takeover interest with offers up to $4.00 a share
[9:27 am] The fleet leasing group is now fielding competing bids from Element, SG Fleet and ORIX after rejecting Element's request for exclusivity.
Rejected Element's request for exclusivity, which would have lifted its indicative cash offer to $4.00 from $3.80 per share
Received a revised SG Fleet proposal at $4.00 per share cash, not conditional on exclusivity but requiring consistent treatment of parties on due diligence
Received an ORIX proposal at $3.80 per share cash, to be implemented via Scheme of Arrangement
All three offers remain indicative, non-binding and conditional, with the Board considering each and no certainty any will become a binding offer
Company page: FleetPartners Group (FPR)
Premier flags FY26 EBIT below guidance and exits Peter Alexander UK stores
[9:27 am] The retailer lifted its earnings shortfall on tough discretionary conditions while pulling its Peter Alexander bricks-and-mortar presence out of the UK.
Premier Retail FY26 unaudited sales down 2.0% to $795.5m
FY26 underlying EBIT now expected at circa $176m, down 3.8% on the circa $183m guidance given in March 2026
Exiting Peter Alexander's three UK stores at Bluewater, Stratford and White City, continuing online and exploring international wholesale
Peter Alexander to return to Myer as a concession partner across 24 stores from August 2027, with at least 5 new store openings in 1H27 including a Sydney CBD flagship in October 2026
Smiggle's strategic reset on track, with the brand retaining its UK presence and a refreshed direction to be unveiled at FY26 results in late September
Company page: Premier Investments (PMV)
SEEK beats on FY26 earnings but guides FY27 profit below consensus
[9:22 am] The jobs platform delivered its sixth straight year of double-digit APAC yield growth, though FY27 adjusted profit guidance sits well under estimates.
Net revenue up 10% to $1.20bn vs $1.19bn ests (in line)
EBITDA up 15% to $529.9m vs $529.4m ests (in line), with margin up to 44%
Adjusted NPAT up 28% to $199.1m vs $197.5m ests (1% beat)
Final dividend of $0.25 per share fully franked, taking the FY26 dividend to a record $0.52, up 13%
APAC paid ad yield grew 18%, with ANZ revenue up 12% and Asia up 3%, offsetting lower paid ad volumes on soft macro conditions
FY27 revenue guided to $1.21-1.28bn vs $1.28bn ests (3% below at midpoint)
FY27 adjusted NPAT guided to $185-215m vs $228.6m ests (13% below at midpoint)
Company page: SEEK (SEK)
AGL guides FY27 profit broadly in line as FY26 lands near estimates
[9:15 am] The energy retailer set a wide FY27 earnings range with a midpoint just above consensus, alongside a lift in the final dividend.
Revenue of $13.59bn vs $13.64bn ests (in line)
Underlying EBIT of $1.26bn vs $1.24bn ests (2% beat)
Underlying EBITDA up 2% to $2.10bn vs $2.13bn ests (in line)
Underlying NPAT down 2% to $631m vs $636.3m ests (1% miss)
Final dividend of $0.26 per share fully franked
Total dividend for FY26 of $0.50, at a 53.3% payout ratio
FY27 underlying NPAT guided to $470-670m vs $550.8m ests (3% above at midpoint)
FY27 underlying EBITDA guided to $1.90-2.20bn vs $2.09bn ests (in line at midpoint), targeting a 55-60% dividend payout ratio
Company page: AGL Energy (AGL)
Carma lifts quarterly retail deliveries 122% year-on-year
[9:14 am] The online used-car retailer grew volumes sharply despite deteriorating market conditions through the June quarter.
Delivered 423 Retail Units in July 2026, taking the three months to 31 July 2026 to 1,200 units
Up 122% on the 540 Retail Units delivered in the three months to 31 July 2025
Used car market conditions deteriorated from March through June on higher fuel prices and broader macroeconomic pressures
Company page: Carma (CMA)
Macmahon named preferred underground contractor for Ravensthorpe Gold Project
[9:13 am] The mining services group secured a roughly $240m contract from Medallion Metals spanning an initial three-year term.
Selected as preferred underground mining contractor for Medallion Metals' Ravensthorpe Gold Project, covering portal establishment, underground development, production and ancillary works
Contract valued at approximately $240m with an initial 36-month term, with works expected to start in the December quarter 2026
Company page: Macmahon Holdings (MAH)
Suncorp lifts underlying earnings 4.5% and returns capital via special dividend and buyback
[9:05 am] The insurer beat on cash earnings despite natural hazard costs running $254 million above allowance, funding a 10 cent special dividend and a fresh buyback.
Cash earnings of $1.04bn vs $1.03bn ests (in line)
NPAT down 44% to $1.03bn vs $1.01bn ests (2% beat), with the FY25 figure including the gain on sale of Suncorp Bank and NZ Life
GWP of $15.41bn vs $15.47bn ests (in line)
Underlying insurance trading result up 4.5% to $1.64bn, with the underlying ITR at 11.8% versus 11.9%
Natural hazard costs ran $254m above the $1.77bn allowance, with more than $10bn paid out across 120,000 claims
Final dividend of $0.52 per share plus a $0.10 special dividend, fully franked, for a 70.5% payout ratio, with a further $250m buyback planned for FY27
Morgans ests was for a final dividend of $0.51
FY27 GWP growth guided to 3-5% with underlying ITR expected in the top half of the 10-12% range
Company page: Suncorp (SUN)
CBA edges past estimates with 7% lift in cash profit
[8:57 am] Australia's biggest bank grew at or above system across all five core domestic product categories, a first for any major bank in 15 years.
Cash NPAT up 7% to $10.98bn vs $10.86bn ests (1% beat)
Statutory NPAT up 8% to $10.91bn
Net interest margin down 3 bps to 2.05%
Operating expenses up 6% to $13.76bn
Loan impairment expense up 9% to $788m as home and personal loan arrears rose to 0.73% and 1.72% on cost-of-living pressures
Final dividend of $2.70 per share fully franked
Total FY26 dividend up 4% of $5.05, at a 77% payout ratio
Return on equity rose to 14.0%, with investment spend up 6% to $2.43bn and guided to hold at $2.4bn in FY27
Cash profit was broadly in-line or fractionally above most analyst estimates, NIM varied (Morgan Stanley at 2.06%, Morgans at 2.04%), FY26 dividend also in-line or slightly ahead (Morgan Stanley at $5.05, Morgans at $4.95).
Company page: Commonwealth Bank (CBA)
Today's reporters: AGL, CBA, Suncorp and more
[8:43 am] Here's a list of today's key reporters, which we'll dig into in a moment.
AGL Energy (AGL)
Bravura Solutions (BVS)
Commonwealth Bank (CBA)
Dexus Industria REIT (DXI)
Kelly Partners (KPG)
Suncorp (SUN)
US-Iran standoff drags on as oil disruptions set to persist into 2027
[8:42 am] Mixed peace signals kept Brent near US$89 a barrel as Washington flagged prolonged supply losses and fresh refinery attacks tightened the diesel market.
Brent up 1.6% to US$89.29 as traders weighed conflicting signals, with Pakistan's defence minister saying the two sides are close to "some sort of an arrangement" even as Trump hardened his stance and demanded Iran pay reparations
EIA now expects supply disruptions of about 600,000 barrels a day through end-2027, with oil through the Strait of Hormuz averaging 4.9m barrels a day in Q2 versus 21.6m in Q4 2025
EIA lifted 2026 gasoline and diesel price forecasts by 3.7% and 5.4% and raised its 2027 retail gasoline forecast by 6.5%, expecting flows to take until early 2027 to return to pre-war levels
Hormuz traffic fell to six vessels on Monday against a 10-day average of about 11, versus 130-140 ships in pre-war days
European diesel futures jumped more than 10% as refinery attacks in Libya and Russia tightened supply, with Saudi Aramco delaying the restart of its 400,000-barrel-a-day Jazan plant to late August after a Houthi strike
Iran and Oman talks on reopening the strait are said to be advanced, though officials stress any Oman deal stays separate from a broader closure agreement
Fed's Hammack says multiple rate hikes may be needed to tame inflation
[8:41 am] The Cleveland Fed chief argued one move alone would do little, ahead of Wednesday's pivotal CPI print.
Hammack said a single 25bp move probably does little for the economy, so bringing inflation to 2% likely needs "some number" of hikes, though she declined to prejudge the total
She was one of three officials who dissented against last month's decision to hold rates steady, favouring a hike
Argued rates are not "meaningfully restricting" the economy and she does not see inflation returning to target on its own
Supermicro and CoreWeave rally after hours on AI demand signals
[8:37 am] Two bellwethers for AI infrastructure spending both beat expectations, sending shares sharply higher after the close.
Supermicro (+6.5% after hours):
Revenue of US$11.1bn vs US$11.55bn ests (4% miss)
Adjusted EPS of US$1.70 vs US$0.96 ests (77% beat), up 315% year-on-year
Gross margin of 17.5%, up 800bps year-on-year, though management flagged around 75% of the sequential improvement came from contract deferrals into Q1'27 with lower tariffs and inventory reserves driving the rest
Adjusted EBITDA of US$1.7bn vs US$655m ests (160% beat) and net income of US$1.2bn vs US$636m ests (89% beat)
FY27 revenue guided to US$65-72bn vs US$52.5bn ests (30% above at midpoint), citing more than US$60bn in new orders and record backlog
CoreWeave (+13.8% after hours):
FY26 revenue guided to US$12.4-13.2bn vs US$12.63bn ests (in line at midpoint)
FY26 adjusted operating income guided to US$960m-1.15bn vs US$893m ests (18% beat at midpoint)
FY26 capex guided to US$35-39bn vs US$33.3bn ests (11% above at midpoint)
Backlog of US$104bn, up 46% year-on-year, with contracted power lifted to 4.2GW from 3.7GW at Q2-end and July pricing up around 25% across SKUs
Targeting active power above 8GW by 2030 and year-end annualised run-rate revenue of US$18.5-19.5bn
Intel upsizes share sale to US$20bn on AI demand
[8:33 am] The chipmaker lifted its raise by a third after drawing more than US$100bn in demand for the offering.
Priced at US$95 per share, a 6.5% discount to Friday's close, after targeting US$15bn when announced Monday
Proceeds build cash for a bigger AI role as Intel struggles to compete with Nvidia and AMD in AI processors and funds its outsourced manufacturing push
Deal underscores resilient demand across the AI supply chain, following SK Hynix's US$26.5bn ADR debut and Alphabet's raise of up to US$85bn
Source: Bloomberg
Citadel Securities flags a re-leveraging setup for equities
[8:33 am] Systematic buyers are poised to rebuild stock exposure after a record unwind, with buybacks and retail flows adding fuel.
Leveraged ETF assets fell nearly 42% to US$154bn last month from US$218bn at end-June, with the sharpest drop in semiconductors, where leveraged ETFs now hold about US$31bn
Citadel Securities says the leverage reset has largely run its course, with the next meaningful mechanical flow more likely re-leveraging than deleveraging
Companies are authorised to buy back more than US$1trn in stock, the largest on record at this point in the calendar
Households are logging US$7.5bn a day in passive ETF inflows, with individual traders turning net buyers last week
Goldman Sachs' prime desk saw the largest hedge fund buying since November 2020, driven by short covering, while Morgan Stanley noted funds rebuilding AI-linked exposure beyond what was unwound in June and July
Source: Bloomberg
CTAs pile into record bond short ahead of US CPI
[8:32 am] Trend-following funds hold their largest-ever underweight in global bonds just as this week's inflation data threatens a sharp reversal.
Commodity trading advisers tripled their underweight bond positions at end-July versus two weeks earlier and have held steady since, per UBS
CTAs stand to gain or lose about US$300m per one-basis-point move in 10-year yields, the biggest such exposure since UBS records began in 1990
Rate swaps put September Fed hike odds at roughly a coin toss, making Wednesday's CPI print pivotal for positioning
Source: Bloomberg
Good morning!
[8:30 am] ASX 200 futures are down 40 pts (-0.43%). Here's what happened overnight:
Wall Street faded a positive open to finish mostly lower for a second session, with the US-Iran standoff and tonight's CPI print keeping buyers sidelined
S&P 500 up 0.19% in early trade, finished the session (0.32%) lower
Nasdaq down (0.60%), Dow down (0.34%), Russell 2000 up 0.32%
Equal-weight S&P 500 eked out a 0.21% gain to close at record highs
Brent gained 1.6% to US$89.3 a barrel, as Trump added compensation demands to Hormuz talks, though Pakistani negotiations believe "some sort of an arrangement" is nearing
Intel raised $20bn in an upsized capital raising, while asset managers like Blackstone, Apollo and KKR rallied on Nvidia's AI financing coalition