ASX 200 Live Today - Monday, 6th July
The ASX 200 is trading slightly lower as declines in banks, staples and miners outweigh gains elsewhere.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Monday, July 6. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
ASX 200 slips but healthcare stocks kick on
[2:10 pm] That's a wrap. The ASX 200 is trading 0.27% lower amid a relatively uneventful session, where weakness from Materials (-0.70%) and Financials (-0.57%) offset the strength in Healthcare (+1.4%), Tech (+0.7%) and Energy (+0.6%).
Banks pulled back after the index closed at a near two-month high last Friday. The index has been trading around breakeven year-to-date for the past few weeks.
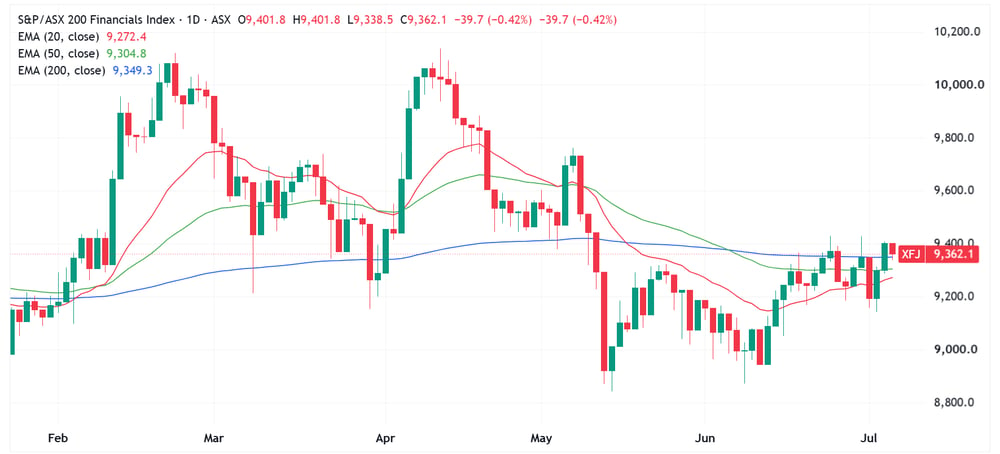
S&P/ASX 200 Financials index daily chart (Source: TradingView)
Likewise, Materials also pulled back after an outsized 2.5% rally last Friday, though the index is still down around 7% since its 17 June record high.
Healthcare has arguably been one of the strongest sectors in recent weeks, now up 23.4% since 3 June.
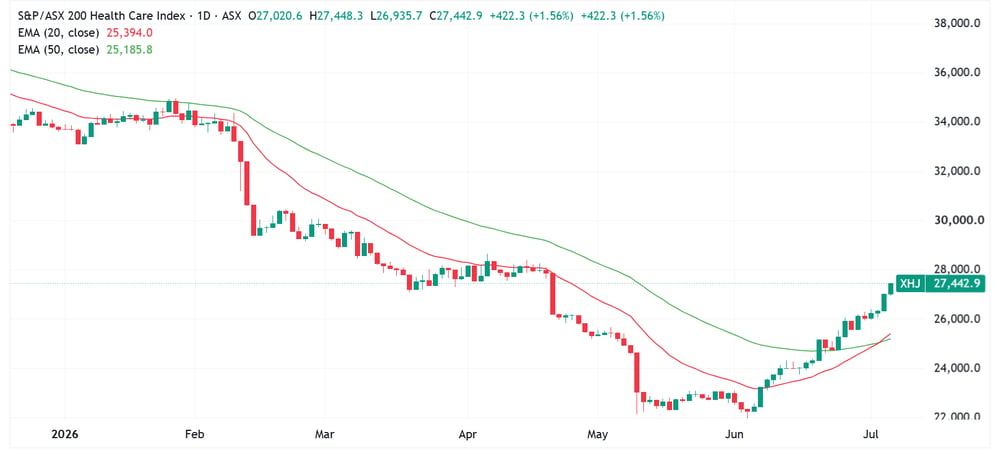
S&P/ASX 200 Healthcare index daily chart (Source: TradingView)
Large cap healthcare names are trading broadly higher today, but names like CSL and Cochlear are still down heavily year-to-date.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
4DX | 4DMedical | 4.8% | $4.46 | 6.3% | 11.4% |
TLX | Telix Pharmaceuticals | 4.4% | $17.62 | 13.8% | 56.6% |
COH | Cochlear | 2.4% | $127.93 | 8.8% | -51.0% |
PME | Pro Medicus | 2.1% | $214.08 | 10.6% | -3.0% |
CSL | CSL | 2.0% | $124.22 | 9.9% | -28.4% |
SIG | Sigma Healthcare | 1.8% | $2.84 | 1.8% | -3.4% |
SHL | Sonic Healthcare | 1.7% | $21.62 | 5.4% | -4.4% |
RMD | Resmed | 1.3% | $30.89 | 5.6% | -14.4% |
ANN | Ansell | 0.8% | $32.72 | 3.7% | -7.0% |
EBO | Ebos Group | 0.3% | $17.53 | 4.7% | -25.7% |
FPH | Fisher & Paykel | 0.3% | $32.85 | 2.8% | -0.5% |
MSB | Mesoblast | -0.5% | $2.05 | 7.6% | -24.9% |
RHC | Ramsay Health Care | -0.8% | $43.80 | 1.7% | 27.2% |
Macquarie upgrades Boss Energy to Outperform, lifts target to $1.75
[1:57 pm] The analysts sees improved risk/reward heading into an accelerated feasibility study and investor day, backed by growing confidence in Honeymoon's wellfield approach.
Macquarie upgraded to Outperform and lifted its 12-month target 35% to $1.75 on higher Gould's Dam and Jason's values and a firmer strategic uranium inventory valuation
Confidence has grown in wider-spaced wellfields at Honeymoon, which if proven would make more lower-grade resource economic at lower capex and opex
The new feasibility study and updated JORC resource have been brought forward about a month to late August, followed by an investor day in September
Q4 production was solid at an implied ~366klbs (versus 360klbs guidance), with IX column 5 and the first East Kalkaroo wellfield commissioned and flushing times beating expectations
Top All Ords gainers and losers
[1:08 pm] Here are the top S&P/ASX All Ords movers at noon.
Ticker | Company | % Chg | Price |
|---|---|---|---|
CU6 | Clarity Pharmaceuticals | 12.67% | $2.49 |
VAU | Vault Minerals | 12.39% | $5.13 |
SHV | Select Harvests | 7.07% | $3.94 |
BOE | Boss Energy | 7.06% | $1.37 |
MEI | Meteoric Resources | 6.25% | $0.17 |
MM8 | Medallion Metal | 6.02% | $0.44 |
DRO | Droneshield | 5.81% | $2.55 |
PWH | PWR | 5.24% | $8.63 |
SX2 | Southern Cross Gold | 5.04% | $9.79 |
NXL | Nuix | 4.64% | $1.24 |
Ticker | Company | % Chg | Price |
|---|---|---|---|
CBE | Cobre | -10.96% | $0.33 |
DTR | Dateline Resources | -9.29% | $0.13 |
TEA | Tasmea | -7.80% | $8.22 |
GNG | GR Engineering Services | -7.43% | $4.86 |
FTI | Fortifai | -6.85% | $0.99 |
LIN | Lindian Resources | -6.81% | $0.89 |
SRL | Sunrise Energy Metals | -6.03% | $16.68 |
EQR | EQ Resources | -6.00% | $0.28 |
SLS | Solstice Minerals | -5.58% | $2.03 |
BRE | Brazilian Rare Earths | -5.03% | $4.34 |
UBS keeps Coles ahead of Woolworths on execution and cheaper multiple
[1:07 pm] The broker's 40th supermarket supplier survey found Coles retaining its overall lead, though Woolworths is now seen best placed to win near-term share.
Coles led on the survey's 26 sub-categories with an average score of 6.77 versus Woolworths' 6.31, ahead in 24 of them and retaining leadership held since Jan-25
Suppliers said Woolworths had the better Apr-May trading (52% versus 33% in Jan-26) and is now best placed to win share over the next six months, with IGA most likely to lose
Inflation expectations moderated to 2.6% from 3.3% in Jan-26, while COGS inflation rose to 4.9%, with 68% expecting it harder to pass on price rises, a margin headwind for suppliers
Woolworths' Customer Offer Reset is seen primarily as margin expansion at suppliers' expense, providing upside risk to its gross margins
UBS prefers Coles (BUY) over Woolworths (Neutral) on stronger execution and a 5.3x forward P/E gap (23.0x versus 28.3x) against a 3.0x five-year average, suggesting Woolworths upside is priced in
CSL continues to climb
[1:04 pm] CSL has now climbed 17 of the last 22 trading sessions, up 33.8% since 3 June.
The company has not announced any market sensitive news since its earnings downgrade on 11 May.
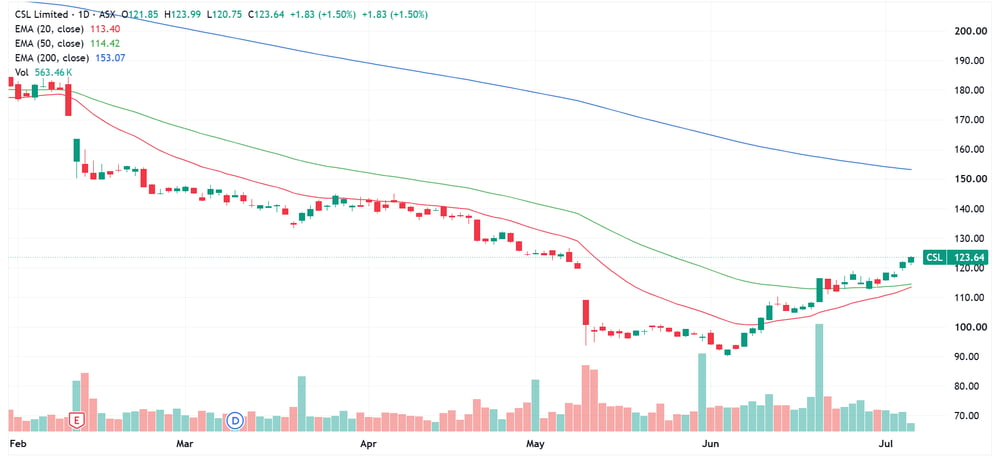
CSL daily price chart (Source: TradingView)
Goldman cuts yen forecast to 165 per dollar, backs carry trades
[1:04 pm] The investment bank turned more bearish on the currency, citing rate differentials and fiscal pressures as it joins a growing chorus expecting further weakness.
Goldman revised its 12-month forecast to 165 per dollar from 155, ranking among the most bearish forecasters surveyed by Bloomberg
The call reflects Japan's fiscal pressures, higher-for-longer US Treasury yields and only gradual BOJ hikes, arguing for continued depreciation despite extreme undervaluation
Near-term forecasts also lifted, to 162 in three months and 163 in six, from 160 and 158 previously
The yen traded at 161.79 per dollar Monday, around its weakest since 1986, with hedge funds' bearish bets at the most since 2017
Goldman favours the yen as a carry-trade funding currency and sees any official intervention as likely short-lived while fundamentals push the other way
Source: Bloomberg
ANZ job ads flat in June as labour market softening looms
[12:09 pm] Advertised roles held broadly steady, with the bank expecting demand to ease as rate rises and housing weakness bite.
ANZ-Indeed Australian Job Ads fell 0.2% month-on-month in June after an upwardly revised 2.0% rise in May, up 0.9% in annual terms and 0.4% in trend terms
Both ABS Job Vacancies and the ANZ series have eased about 28% since late 2022 but remain well above pre-pandemic levels
Employment was essentially flat over the past two months after a 40.3k May rise offset a revised 40.7k April fall, with hours worked down 1.1%, the largest drop since June 2025
ANZ expects labour demand to gradually ease and unemployment to edge higher on higher rates, the housing slowdown and Middle East uncertainty
Gains were led by Tasmania, South Australia, Queensland and Victoria, while NSW and Western Australia declined, with retail and food preparation the biggest drags
Melbourne Institute inflation gauge falls again in June as fuel prices ease
[12:08 pm] The private monthly measure declined for a second straight month, though annual inflation remains well above the RBA's target band.
The gauge fell 0.4% month-on-month in June, following a 0.3% decline in May, its second consecutive drop and third this year
The fall was primarily driven by lower transport prices, largely attributable to fuel
Headline inflation ran at 3.9% in annual terms, still above the RBA's 2-3% target range
The monthly cost of living declined for three of five selected household types, including age pensioners and other government transfer recipients
CATL takes 20% stake in NZ firm turning wood into battery graphite
[12:06 pm] The world's biggest EV battery maker is backing CarbonScape to scale bio-based graphite as the West faces years of supply deficits.
CATL and Hong Kong's Lochpine Capital will become strategic investors in CarbonScape with a combined 20% interest, testing its technology at demonstration scale at CATL's facilities
CarbonScape converts forestry byproducts into graphite for lithium battery anodes, targeting commercial biographite production by the end of the decade
China dominates the global graphite supply chain, with the rest of the world facing natural and synthetic deficits until at least 2031, per Benchmark Mineral Intelligence
Battery-grade graphite demand is expected to grow around sixfold between 2025 and 2040, with over 75% of battery graphite currently derived from oil-based feedstock
Source: Bloomberg
Gold stocks as bullion bounces
[11:13 am] A relatively mixed day for gold miners, though the broader All Ords Gold Index is still tracking 0.7% higher and now up 12.7% in the last three sessions. Gold prices are up 1.5% on Monday but still down 3.3% in the past month to US$4,185/oz.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
VAU | Vault Minerals | 12.0% | $5.11 | 9.8% | -6.2% |
RRL | Regis Resources | 3.6% | $6.87 | 2.5% | -8.6% |
BGL | Bellevue Gold | 3.2% | $1.37 | 2.8% | -18.8% |
EMR | Emerald Resources | 2.1% | $5.82 | 1.9% | -7.3% |
SBM | St. Barbara | 2.0% | $0.52 | 6.2% | -10.4% |
CYL | Catalyst Metals | 2.0% | $6.21 | 12.9% | -15.9% |
BC8 | Black Cat Syndicate | 1.8% | $0.98 | 3.4% | -19.6% |
CMM | Capricorn Metals | 1.6% | $14.26 | 12.3% | 1.9% |
NEM | Newmont | 0.5% | $142.92 | 3.4% | -4.8% |
EVN | Evolution Mining | 0.3% | $12.86 | 4.0% | 2.3% |
ALK | Alkane Resources | 0.1% | $1.44 | -2.6% | 8.4% |
RMS | Ramelius Resources | 0.0% | $3.21 | 3.9% | -21.5% |
AMI | Aurelia Metals | 0.0% | $0.30 | 7.3% | 20.4% |
RSG | Resolute Mining | -0.3% | $1.00 | -3.2% | -18.2% |
WGX | Westgold Resources | -0.4% | $5.06 | 3.5% | -19.7% |
OBM | Ora Banda Mining | -0.4% | $1.19 | 1.7% | -22.5% |
NST | Northern Star Resources | -0.5% | $22.06 | 6.5% | -10.2% |
PRU | Perseus Mining | -0.7% | $5.19 | -1.8% | -5.9% |
PNR | Pantoro Gold | -1.3% | $2.36 | -3.7% | -51.8% |
MEK | Meeka Metals | -2.6% | $0.11 | 13.1% | -58.5% |
GMD | Genesis Minerals | -3.4% | $6.08 | 8.9% | -15.2% |
Chip bulls look to Samsung earnings to steady jittery AI trade
[11:11 am] The memory giant's Tuesday preliminary print is shaping as a key test of AI demand after weeks of volatile swings in semiconductor shares.
Samsung is forecast to report preliminary Q2 operating profit of 84.3 trillion won ($55.1bn), an 18-fold jump on a year earlier that would dwarf its full-2025 profit, with revenue seen up 127% to a record 169 trillion won
The stock is up more than 155% this year but fell nearly 9% over five sessions to Friday, its worst week since late March, amid wild swings across global chip names
The AI memory crunch drove average DRAM selling prices up more than 40% quarter-on-quarter and NAND up more than 50%, per HSBC, lifting margins at Samsung and SK Hynix
Despite the rally, Samsung trades at just 5.7 times forward earnings, near its cheapest ever, versus 7 for Micron and nearly 24 for the Philadelphia Semiconductor Index
Citi raised its target to 530,000 won from 460,000 won, 71% above Friday's close, viewing the pullback as a technical correction with memory fundamentals intact
Source: Bloomberg
Analysts' take on Suncorp
[11:07 am] Suncorp's pre-result trading update last Friday trimmed premium growth expectations again while reiterating underlying margins toward the upper end of the target range, confirming stronger investment income and finalising a reinsurance program that includes a previously flagged aggregate cover. The stock fell 3.7% on the day and down a further 2.4% today.
Jarden retained Neutral, lowered target from $19.70 to $19.60, flagging a deliberate margin over volume positioning shift and highlighting capital management as the key earnings driver amid top line risks ahead of guidance.
UBS retained Buy, raised target from $19.60 to $20.80, citing stronger investment returns lifting the earnings outlook and an increased likelihood of further buybacks while viewing valuation as still undemanding.
Goldman Sachs retained Neutral, target unchanged at $20.00, flagging demand softness as a risk into the following year and expecting reinsurance costs to rise on the aggregate cover while noting scope for further capital release.
Analysts' take on Pexa
[11:06 am] IPART's draft report on PEXA's ELNO service fees last Friday recommended a far steeper cut to Exchange transfer fees than the market had anticipated, driven by a lower initial asset base than most brokers had modelled, sending shares down 21.3% on the day.
Analysts broadly viewed the outcome at the harsher end of scenarios and, given the division's largely fixed cost base, expected a proportionally larger earnings hit, though most anticipated some softening through consultation.
JPMorgan downgraded to Neutral from Overweight, lowered target from $14.00 to $10.50, modelling margin compression from the lower revenue base while awaiting management's response and noting the volume adjustment mechanism offers some protection.
Macquarie retained Outperform, lowered target from $19.30 to $16.00, assuming the proposed cuts could be partially walked back and citing unregulated ancillary products as a revenue offset and tier one lender commitments as a near term catalyst.
UBS retained Neutral, lowered target from $12.80 to $9.80, highlighting asymmetric downside risk already reflected pre release while warning the initial asset base could decline further amid weaker transaction volumes and leadership changes.
Top ASX 200 gainers and losers
[10:22 am] Vault surges after receiving a takeover offer from Genesis Minerals, growth names like 4DMedical, Droneshield and Telix catch a bid, while Suncorp continues to tumble after management trimmed GWP growth expectations last Friday.
Ticker | Company | % Chg | Price |
|---|---|---|---|
VAU | Vault Minerals | 10.09% | $5.02 |
4DX | 4DMedical | 5.88% | $4.50 |
MI6 | Minerals 260 | 3.40% | $0.76 |
DRO | Droneshield | 2.90% | $2.48 |
CMM | Capricorn Metals | 2.78% | $14.42 |
TLX | Telix Pharmaceuticals | 2.25% | $17.26 |
IFT | Infratil | 2.08% | $12.75 |
HUB | Hub24 | 1.86% | $82.55 |
PXA | Pexa Group | 1.81% | $8.70 |
RRL | Regis Resources | 1.81% | $6.75 |
Ticker | Company | % Chg | Price |
|---|---|---|---|
GMD | Genesis Minerals | -7.15% | $5.84 |
SUN | Suncorp Group | -3.65% | $17.95 |
GGP | Greatland Resources | -2.42% | $11.49 |
TUA | Tuas | -1.94% | $2.28 |
MFG | Magellan Financial Group | -1.79% | $10.44 |
IMD | Imdex | -1.72% | $4.00 |
IAG | Insurance Australia Group | -1.60% | $7.99 |
AAI | Alcoa Corporation | -1.49% | $72.00 |
PNR | Pantoro Gold | -1.46% | $2.36 |
AMP | AMP | -1.46% | $1.69 |
ASX 200 slips as Staples, Utilities and Banks open lower
[10:18 am] The ASX 200 is down 0.20% in early trade, as defensives and recent high-flying sectors like Staples and Discretionary take a breather. This follows a sharp resource-led 1.37% bounce last Friday.
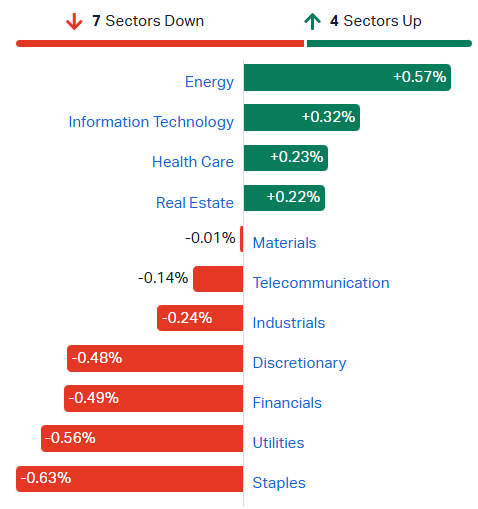
S&P/ASX 200 sectors (Source: Market Index)
Auction clearances stay below 50% for third week as housing slump deepens
[9:55 am] Buyers are holding back on falling prices and negative gearing changes, with values recording their biggest monthly drop in more than three years.
The preliminary national clearance rate was 49.8%, the third straight week below 50%, with last week's 49.2% preliminary figure revised down to 45% on final tally
Brisbane clearances crashed to 23.8%, the lowest in six years, from 39.3% a week earlier, against Melbourne at 54.5% and Sydney at 51.6%
National home values fell 0.4% in June, the largest monthly decline since December 2022, led by Sydney down 1.2% and Melbourne down 1%
Auction listings dropped 17.2% week-on-week and were 19% below the same week last year on the winter slowdown, with capital city sales in the June quarter estimated 16.2% below a year earlier
Source: Cotality
Dexus flags marginal portfolio valuation dip as market stabilises
[9:48 am] Draft external valuations point to a slight decline over the half, with a weaker office book offset by industrial gains.
The portfolio of 27 office and 148 industrial properties fell an estimated $24m or 0.2% on book values for the six months to 30 June 2026
Office values slipped around 0.4% on higher capitalisation and discount rates, partially offset by market rental growth
Industrial values rose around 0.5%, driven by rental growth and a slightly firmer discount rate
The weighted average capitalisation rate expanded 3 basis points to 6.06% for the stabilised total portfolio, 6.22% for office and 5.58% for industrial
CEO Ross Du Vernet said the valuations reflect a stabilising market driven by fundamentals, with final details due in FY26 results on 20 August 2026
Company page: Dexus (DXS)
Talga signs non-binding LOI with Mitsubishi Chemical for anode supply
[9:48 am] The battery materials group has secured a structured engagement to progress commercial talks on supplying its graphite anode to a major Japanese manufacturer.
Talga has executed a non-binding LOI with Mitsubishi Chemical Corporation covering potential supply of its Talnode anode products for hybrid electric vehicle batteries
The parties are targeting a conditional Supply Terms Sheet in September 2026 and a definitive three-year Supply Agreement by December 2026, subject to testing and qualification
The LOI is expressly non-binding with no obligation to buy, sell or reserve capacity, and no material financial impact is expected at this stage
Volume ranges and raw-material security requirements remain under discussion, with deadlines extendable by mutual agreement
Company page: Talga Group (TLG)
Endeavour and Treasury Wine put vineyards on the block amid industry glut
[9:28 am] Endeavour Group and Treasury Wine Estates have appointed selling agents for a raft of vineyard assets as both companies cut costs and shift toward asset-light wine strategies under new chief executives.
Endeavour appointed Colliers for Oakridge Wines in the Yarra Valley and Elders for its South Australian vineyards, targeting sales within FY27
Endeavour's vineyards up for sale could fetch about $20m combined, with the Oakridge brand and land alone worth an estimated $10m-$15m
Endeavour is also offloading Chapel Hill in McLaren Vale plus properties in the Barossa, Coonawarra and Tasmania, retaining the Chapel Hill brand
Treasury Wine appointed Colliers to sell the near-1,300 hectare Markaranka vineyard in the Riverland, central to its Penfolds fortified program
Treasury is also selling the Schultz and Lights vineyards in the Limestone Coast, with buyers likely to be graziers
Treasury is shrinking its global portfolio from 76 brands to fewer than 30 under new CEO Sam Fischer
Consultant AlixPartners estimates about one-fifth of Australian vines may need to be removed to reset an industry facing oversupply and falling consumption
Source: AFR
Morgan Stanley lifts Santos to overweight in triple energy upgrade
[9:27 am] Morgan Stanley's Rob Koh has upgraded Santos, Beach Energy and Woodside, turning most constructive on Santos while flagging limited upside across the sector.
Santos upgraded to overweight from equal-weight, target lifted to $7.67 from $7.50
Beach Energy upgraded to equal-weight from underweight, though target cut to $0.88 from $1.20
Woodside upgraded to equal-weight from underweight, target held at $28
Vault gets superior $5.6bn Genesis bid, triggering Regis matching right
[9:27 am] The gold miner's board has judged Genesis's unsolicited cash-and-scrip offer superior to its existing scheme with Regis, opening a five-day matching window.
Genesis has offered 0.7629 new shares plus $0.475 cash per Vault share, valuing Vault at $5.6bn or $5.274 a share based on Genesis's 3 July close
The bid represents a 14.5% premium to the implied $4.614 Regis scheme price and a 15.7% premium to Vault's last close
Vault's board unanimously deemed it a "Superior Proposal", with the offer carrying no financing or due diligence conditions
A mix-and-match facility lets shareholders vary cash or scrip, subject to aggregate caps of about $500m cash and 803.4m Genesis shares
Regis now has a five-business-day matching right, expiring 11:59pm AWST on 10 July, during which Vault cannot comment further
Company page: Vault Minerals (VAU)
Anthropic tenders for 1.4GW of Australian data centre capacity in deal worth up to US$15bn
[9:24 am] Anthropic has issued a confidential RFP seeking at least 1.4GW of Australian data centre capacity, with CDC, AirTrunk, NextDC, Iren and Stack among the parties invited to bid on a project that could cost up to US$15 billion to build, according to the AFR.
Anthropic wants at least 1GW of capacity operational by the end of 2027, exceeding previous estimates of its needs
Base case is a single long-term partner for a 1.4GW-plus campus, with willingness to co-develop a site from scratch
Initial proposals landed end of March, with on-site meetings held in Canberra in early April
Anthropic is at least six weeks from a final decision and may split the deal into four or five smaller contracts rather than one landlord
Infratil-owned CDC is expected to take the largest share at about 500MW if the deal is split
RFP financing questions centre on Anthropic's non investment-grade credit status despite a $US965 billion valuation in its May Series H round
Bidders were asked for land bank details, construction track records on projects above 200MW, and energy solutions for projects above 300MW, including on-premises generation
Source: AFR
Infratil's CDC valuation jumps 23.6% to A$18.5bn on surging data centre demand
[9:21 am] Infratil's independent valuation of Canberra Data Centres (CDC) rose A$3.5 billion to a A$18.5 billion (mid-point) in the June quarter, driven by contracted capacity crossing 1GW and a sharp expansion of the future development pipeline.
30 June 2026 independent valuation of CDC increased 23.6% to A$18.5bn, within an assessed range of A$17.5bn to A$19.7bn
Infratil's 49.72% stake in CDC now valued at A$9.21bn
Contracted capacity exceeded 1GW during the quarter, including a 555MW contract signed in May and 14MW in New Zealand
Total leasable pipeline to FY40 increased 1.9GW to 3.9GW, including 1.3GW of new future build capacity in Australian markets
Cost of equity increased to 12.45% from 11.84%, driven by a 25bps rise in the risk-free rate to 4.25% and higher forecast gearing
Net debt increased on accelerated debt-funded construction; CDC issued a A$1 billion hybrid capital bond at a blended margin of 250bps following its public Moody's Baa2 (Stable) rating
Infratil's share price is up 3.2% in morning trading on the NZX
Regis hits top of FY26 guidance with 379koz as cash swells past $1.2bn
[9:13 am] A stronger fourth quarter lifted annual output to the upper end of the range, with the balance sheet materially strengthened over the year.
Group FY26 production of 379koz landed at the top of the 350-380koz guidance range, with Q4 output of 101.5koz up 12% quarter-on-quarter
Cash and bullion of $1.21bn at 30 June, up $692m over the financial year after $151m of dividends and $156m of tax
The quarter generated $284m of underlying cash before a $114m April dividend, $64m of tax and about $25m of higher-than-usual diesel costs
Duketon produced 62.5koz and Tropicana 39.1koz in Q4, with both divisions finishing FY26 within their respective guidance ranges
AISC, growth capex and exploration all reaffirmed within guided ranges, with AISC toward the top end
Company page: Regis Resources (RRL)
Capricorn delivers FY26 gold at top of guidance as KEP nears commissioning
[9:12 am] The miner hit the upper end of its production range while advancing two growth projects and paying a maiden dividend.
KGP produced 123,589oz in FY26, at the top end of 115,000-125,000oz guidance, with Q4 output of 30,437oz
AISC expected to land within the FY26 cost guidance range of $1,530-1,630/oz
Cash and gold on hand of $507.0m at 30 June, broadly flat on March's $507.6m, after $46.0m of capex, a $22.8m maiden dividend and a $68.2m underlying cash build
The Karlawinda Expansion Project is advancing toward commissioning this quarter, with concrete works complete
At the Mt Gibson Gold Project, Capricorn received federal EPBC approval and awarded MACA Interquip the main plant construction scope, with the state assessment process now being finalised
Company page: Capricorn Metals (CMM)
ASX June trading activity jumps as capital raisings slump
[9:02 am] Secondary market volumes surged on higher trades and volatility, while new capital quoted fell sharply against a strong prior-year comparison.
Average daily value traded on-market rose 19% to $8.413bn, with the average daily number of trades up 47% on the pcp
Total new capital quoted fell to $3.3bn from $11.0bn in the pcp, though June YTD net new capital of $37.1bn edged ahead of $35.6bn a year earlier
Volatility picked up, with the All Ordinaries average daily movement at 0.6% versus 0.3%, and the ASX 200 VIX up 12% to an average of 12.4
Total average daily futures and options on futures volumes rose 21%, with index options up 16% while single stock options fell 4%
Participant margin balances held on balance sheet fell to $10.4bn at 30 June from $13.0bn a year earlier
Company page: ASX (ASX)
Helia retains ING as exclusive LMI provider
[9:01 am] The four-year renewal shores up a major customer relationship for the mortgage insurer following the loss of its largest client earlier this year.
Helia has been selected as ING's exclusive Lenders Mortgage Insurance provider for four years from 1 July 2026, replacing the prior agreement that expired 30 June
ING represented around 20% of Helia's FY25 Gross Written Premium, making the renewal a material contract to secure
The win carries added weight after Helia lost its CBA contract, which accounted for~40% of FY25 GWP, with no new CBA business written since 31 January 2026
Company page: Helia Group (HLI)
China services growth eases in June as export demand hits 20-month high
[8:57 am] The private PMI dipped slightly but stayed firmly in expansion, with overseas orders and a return to price rises the standout features.
The RatingDog China General Services PMI fell to 54.1 in June from 54.4 in May, holding above the 50 expansion threshold as new business growth slowed
New export business rose at its fastest pace since October 2024, cushioning the softer domestic new-work trend
Companies raised selling prices for the first time in four months and at the quickest rate in over two years, even as input cost inflation eased
Service providers added jobs faster on improving demand, though year-ahead business optimism softened
The Composite Output Index eased to 53.6 from 54.0, while a separate official survey showed services edging up on a different sample
Source: Reuters
Trump gives Warsh leeway on rates, flags "hostile" Fed board
[8:56 am] The president softened his rate-cut pressure after weak June payrolls, while vowing to renew his push to remove governor Lisa Cook.
Trump said new Fed chair Kevin Warsh faces a board that is "a little bit hostile" and may struggle to steer colleagues on policy, a marked shift from months of hectoring Powell to cut rates
June payrolls showed hiring slowed sharply while unemployment fell to 4.2% on shrinking participation, prompting investors to scale back bets on a rate increase this year
Trump vowed to restart efforts to oust governor Lisa Cook after the Supreme Court ruled 5-4 to keep her in post while she challenges removal, faulting the administration on process rather than merits
Warsh said this week that price risks have eased recently and reaffirmed his commitment to the 2% inflation target and Fed independence
Inflation accelerated in May to its fastest in more than three years on higher energy costs from the Iran war, though economists say it has likely peaked as oil prices fall
Source: Bloomberg
Citi sees Brent sliding to US$60 as Hormuz shock unwinds
[8:54 am] The investment bank joins a bearish chorus, urging clients to sell summer rallies as normalising shipping flows and absent Chinese buyers reassert oversupply.
Citi forecasts Brent at US$60-65 a barrel by year-end and recommends selling any summer rallies, citing normalising shipping flows, absent Chinese buyers, weakening physical markets and smaller-than-expected inventory draws
Goldman Sachs sees the market swinging back into oversupply as the Iran war impact fades, while Morgan Stanley has cut its oil forecasts twice recently on glut risks
Source: Bloomberg
Oil supply builds as Hormuz fee standoff clouds tense Iran ceasefire
[8:53 am] Iran insists on transit fees once a 60-day pause expires, while OPEC+ adds barrels into a falling price environment.
Iran reaffirmed it will charge fees on ships transiting the Strait of Hormuz once the current 60-day free-passage window ends, with "special treatment" flagged for friendly nations, an idea the US and Oman reject
OPEC+ agreed a fifth straight monthly output increase, with seven members adding a combined 188,000 barrels per day in August as prices sit at pre-war lows
Iran issued a "serious warning" to France and the UK after they pledged to help Oman keep the waterway safe, raising the risk of renewed escalation
The fee dispute has stalled US-Iran talks before nuclear arsenal discussions have even begun, leaving the ceasefire fragile
Multi-day funeral ceremonies for slain supreme leader Ali Khamenei drew mass crowds and revenge chants, with successor Mojtaba Khamenei still unseen since February
Prediction markets hit record volumes as World Cup drives betting surge
[8:41 am] The FIFA World Cup fuelled blockbuster June trading across event contract platforms, pressure-testing the sector as regulators and institutions watch.
Kalshi did more than $31bn in notional volume in June, up over 70% from May's $17.9bn, sustaining daily volume above $1bn since the tournament began on June 11
Polymarket's international exchange set a monthly record above $10.8bn, reversing April and May declines, while its US platform did north of $3.5bn, up from $1.77bn
Kalshi open interest now tops $1bn, while Polymarket sits just under $400m, with both elevated on World Cup excitement
More than $64m on Kalshi and $122m on Polymarket has been traded on a US tournament win, despite odds of just 4.3% and 3% respectively
Source: CNBC
US equity funds bleed as global flows tilt to tech dip-buyers
[8:38 am] Fund flow data diverged last week, with BofA flagging the fastest US stock exodus since March even as broader global equity funds drew money into a tech pullback.
US stock funds saw US$17.2bn of outflows in the week to July 1, the fastest pace since March, per BofA citing EPFR data, with overall equities losing US$13.9bn
The Philadelphia Semiconductor Index fell 11% over two days as AI valuation scepticism persisted, with JPMorgan flagging an unsustainable gap between chip stocks and hyperscalers
Investors rotated internationally, with Japanese equities drawing their biggest inflows in seven weeks at $1.9bn
Separately, LSEG Lipper data showed global equity funds took in US$10.44bn, up about a quarter on the prior week, as investors bought the tech dip after the MSCI World fell 2.07%
Investment grade bonds attracted $17.2bn and high-yield funds saw their biggest inflows in over a year, while gold and precious metal funds logged a seventh straight weekly outflow
Wall Street bets resilient markets can absorb every shock into second half
[8:36 am] A diversified stocks, bonds and commodities portfolio posted its best first-half return since 2021, and the sell-side sees the expansion holding despite stretched valuations.
The Nasdaq 100 gained nearly 20% and semiconductors surged triple digits in the first half, though the Magnificent Seven lost about 2% on a total-return basis as investors favoured AI builders over deployers
Gold, silver and Bitcoin all finished the half lower despite months of geopolitical turmoil, while government bonds delivered positive returns
Bloomberg's survey puts the average S&P 500 year-end target at 7,716, implying roughly 3% upside from June 30 after the benchmark's 9% year-to-date climb
Barclays argues the rally is far narrower than it looks, estimating semiconductor and computer hardware names drove around 87% of first-half S&P 500 gains
Source: Bloomberg
JPMorgan slashes gold forecast to US$4,500 as demand disappoints
[8:36 am] The investment bank sees weaker sector demand capping this year's rally and warns the risks skew lower still if the Fed hikes early.
JPMorgan now forecasts gold at US$4,300/oz in the third quarter and US$4,500/oz in the fourth, down sharply from the US$6,000 year-end call it held as recently as June 9
Risks skew to the downside on the possibility of early Fed rate hikes should summer data run hot, with high rates weighing on non-yielding bullion
Retained a long-term bullish view, expecting gains to extend into 2027 on central bank buying and structural physical demand
Silver forecast to average US$60-65/oz as tight physical conditions ease and the gold-to-silver ratio normalises
Source: Reuters
India emerges as AI hedge as calmer markets draw back investors
[8:35 am] Indian equities are regaining favour as a low-volatility diversifier, with easing oil prices and a stabilising rupee brightening the earnings outlook.
India's absence from the AI trade has turned it into a relative safe haven, with the Nifty 50 moving 1% or more on just 38 sessions in the first half of 2026 versus 59 for MSCI emerging-market and Asian gauges and 32 for the S&P 500
The Nifty 50 outperformed the MSCI Emerging Markets Index in June by the most since November, while foreign outflows were the smallest in four months
Falling commodity prices, a rupee recovering from a record low and stable rates have reduced inflation concerns and lifted growth prospects, setting up likely earnings upgrades
Morgan Stanley's Ridham Desai frames India as a "much larger macro asset class" offering defensive growth that can better withstand global shocks, with the Nifty 50 nearly tripling over the past decade
Source: Bloomberg
Good morning
[8:22 am] ASX 200 futures are down 52 pts (-0.39%) despite European stocks rising to record highs and gold bouncing towards US$4,200/oz.
The overnight session in a nutshell:
Wall Street was closed Friday for the Independence Day holiday, leaving Thursday's record Dow close, a flat S&P 500 and a lower Nasdaq as the most recent read
European equities notched fresh record highs and a fourth straight weekly gain, while gold rallied back toward US$4,200
OPEC+ approved another 188,000 barrels per day August output rise as Strait of Hormuz shipping recovers, and Iran held a state funeral for slain Supreme Leader Khamenei