ASX 200 Live Today - Friday, 7th August
The S&P/ASX 200 is set for a flat open as major US benchmarks continued to slip from record highs. Here are today's top stories.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Friday, August 7. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
Reporting season is heating up and we've got you covered. Our reporting season calendar has over 250 stocks plus earnings and dividend estimates.
ASX 200 claws back early losses
[2:20 pm] The S&P/ASX 200 is currently up 1 pt (+0.02%), having rallied off session lows of (0.59%). A fairly mixed session, with tech (+1.2%), materials (+1.2%), energy (+0.9%) and real estate (+0.2%) higher and everything else lower, led by financials (0.8%) and healthcare (0.8%).
WiseTech (+5.9%) headlines the tech rally, trading at its highest since 3 June and up 39% in ten sessions. The sector is now on a ten-day win streak, up 18.2%. It has yet to take out the 2 June high, but the strength in recent days has been quite remarkable. Catapult is one to watch here, a software name that's traded sideways since February.
Materials was the main swing factor, with BHP (+0.4%) recovering from a (1.1%) dip in early trade. Copper is 0.27% higher and hovering near record highs of US$6.80/lb, while gold is up 0.6% to US$4,265/oz, a near four-week high and just below its 200-day moving average. Breadth isn't as positive as it has been in recent sessions, but miners are doing the heavy lifting at the index level on the back of higher copper and gold. Reporting season heats up next week, so have a good weekend.
Light & Wonder decides to kick on
[2:07 pm] Light & Wonder reported a better-than-expected Q2 result on Wednesday. The stock closed 3.9% higher on the day, then flattish the next day. Today it's rallied 6.5% to a six-week high.
Thinking out loud: You often see these illiquid/thinly covered names barely move on a good catalyst. Maybe a little spike on day one, then nothing for day(s), then spikes out of nowhere.
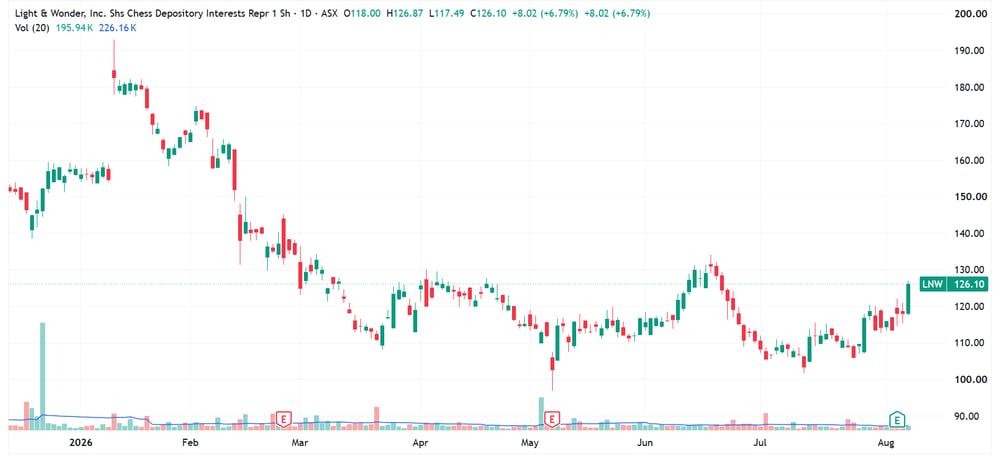
Light & Wonder daily price (Source: TradingView)
This is what we noted on the blog on Wednesday.
Revenue up 2% to $828m vs $842.4m ests (2% miss)
Consolidated AEBITDA up 9% to $383m vs $366.2m ests (5% beat)
EPS of $1.53 vs $1.23 ests (24% beat)
Adjusted free cash flow up 50% to $156m vs $110.1m ests (42% beat)
UBS flagged that FY26 guidance for mid-to-high single digit AEBITDA growth was reiterated in mid-July, and the ~8% share price reaction that day showed the market's earnings-risk sensitivity. The Q2 result leaves the company well placed against UBS's full-year estimate, which is looking for 6% growth over the remainder of 2026. UBS reiterated a Buy rating on 28 July, calling LNW the strongest shareholder return in its gaming coverage and flagging its ~60% PE discount to Aristocrat.
Very confused price action for 'cheap' reporters
[1:15 pm] Just thinking out loud here. We've seen some very whipsaw-like price action in a couple of growth-y kind of names this week, with Nick Scali (UK growth story, and sector-leading margins), and REA Group (Aussie property/pricing power). Both stocks have de-rated in recent months, with both results giving something for bullish and bearish investors.
Nick Scali's FY26 was relatively mixed, with solid margins offsetting a softer-than-expected revenue outcome.
Revenue of $516.7m vs $533.5m ests (3% miss)
EBITDA of $180.7m vs $182.4m ests (1% miss)
NPAT of $75.7m vs $76m ests (in line), up 22% year-on-year
Final dividend up to $0.39 fully franked from $0.33 a year ago
Group gross margin up 210bps to 65.60%
FY27 off to a mixed start, ANZ written sales orders flat over the first five weeks against high single-digit growth a year ago while the UK surged 35%, with four new ANZ stores and one UK opening planned
"We note at the February result the stock was cycling January ANZ WSO of -8% and delivered +3% growth, which surprised the market and contributed to a 22% share price decline on result day. In our view, the result day could present an attractive entry point for an investor willing to look through the cyclical headwinds," said Morgans.
So you've got a stock that's de-rated from highs of ~35x to 22x, delivering a broadly in-line result with the all-important margin outcome in line too. What followed was a massive rip-n-dip move: Nick Scali opened slightly higher, dropped as much as 5.5% inside the first two minutes, V-shaped back to a 1% gain, rolled over to a 2% decline, then ripped to a session high of 6.7% by 10:45 am. It's now trading slightly lower.
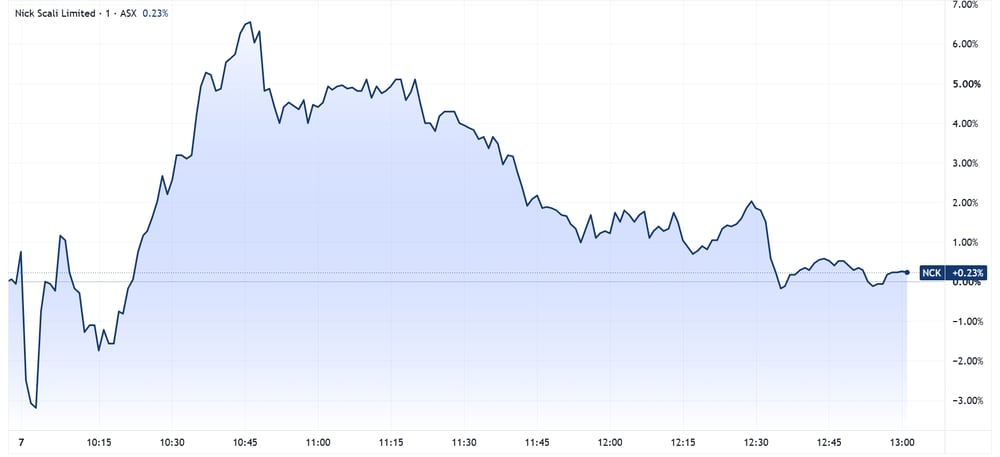
Nick Scali intraday price chart (Source: TradingView)
REA did much the same on Thursday. The stock gapped up, dipped, ripped, dipped again and finished around opening levels, up 3.4%.
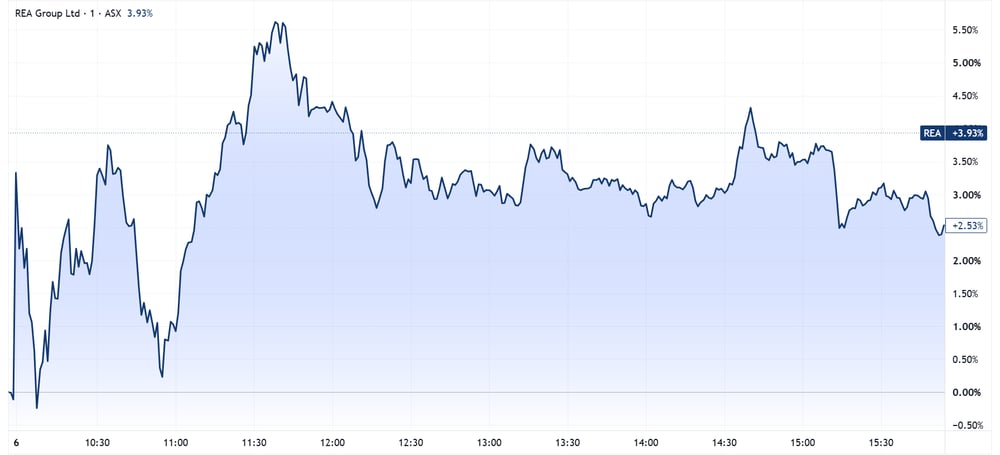
REA intraday price chart (Source: TradingView)
The result, much like Nick Scali's, had a little for both sides.
Revenue up 7% to $1.79bn, in line with ests
Core NPAT up 15% to $650.5m vs $637.3m ests (2% beat)
Final DPS of $1.73 fully franked, with full-year dividend up 20% to $2.97 vs $2.95 Macquarie ests (1% beat)
Residential revenue up 12% on 13% Buy yield growth and flat listings, better than the anticipated 1-3% decline
FY27 new Buy listings guided flat to down low single-digits, with July down 2% and combined Sydney/Melbourne listings down 16%
FY27 yield growth guided low double-digits, underpinned by an 8% Premiere+ price rise, with operating costs up mid single-digits ex-M&A
The result highlighted REA's non-listing levers, that being, pricing power and premium products.
The result highlighted REA's growth levers, beyond new listings, namely pricing power and premium products. Even as new listings are forecast to be flat or slightly lower in FY27, the company is still widely expected to grow earnings by the low teens. New listings are forecast flat to slightly lower in FY27 and the company is still widely expected to grow earnings by the low teens. That isn't how REA has grown over the past decade, but it does show the business can keep compounding in a soft market. With the multiple back from 2020-21 highs of 55x to around 25x, look through the near-term property headwinds and it might even screen cheap.
Top ASX 200 gainers and losers at noon
[12:18 pm] Light & Wonder opened flat this morning but caught an aggressive bid (reported better-than-expected Q2 result two days ago), while gold and lithium names continue to hold onto early gains. Meanwhile, ResMed and growth-y names like Zip and Droneshield continue to lag.
Ticker | Company | % Chg | Price |
|---|---|---|---|
MI6 | Minerals 260 | 7.81% | $0.79 |
LNW | Light & Wonder | 6.70% | $125.99 |
ILU | Iluka Resources | 6.27% | $7.21 |
PLS | PLS Group | 5.23% | $4.53 |
BGL | Bellevue Gold | 4.60% | $1.52 |
PDI | Predictive Discovery | 4.41% | $0.76 |
WAF | West African Resources | 4.37% | $3.47 |
LTR | Liontown | 4.35% | $1.13 |
TLX | Telix Pharmaceuticals | 4.29% | $15.69 |
JHX | James Hardie | 4.10% | $42.50 |
Ticker | Company | % Chg | Price |
|---|---|---|---|
4DX | 4DMedical | -9.70% | $4.19 |
RMD | Resmed | -5.84% | $29.64 |
DRO | Droneshield | -5.04% | $2.17 |
ZIP | Zip Co | -4.90% | $2.82 |
XYZ | Block | -4.53% | $113.06 |
JDO | Judo Capital | -2.90% | $1.01 |
MSB | Mesoblast | -2.69% | $2.17 |
PNI | Pinnacle Investment Management | -2.65% | $18.74 |
NWL | Netwealth Group | -2.05% | $24.40 |
PME | Pro Medicus | -1.88% | $174.64 |
Nick Scali FY26 earnings call highlights
[12:15 pm] Management pointed to record margins, an improving UK turnaround and a deliberately cautious read on a tough ANZ furniture market.
On the macro: Anthony Scali called it "one of the worst macro for rates for furniture", citing falling house prices, a negative wealth effect and housing transactions slow for six months, with the first-five-week trading update off high comps and "very difficult to predict"
On ANZ margins: the 66% gross margin is "a very high number", with management guiding to "somewhere between 65 and 66" as lower-rate hedges roll off but are offset by freight and bunker cost increases
On the UK: second-half margin improved to 61.2% and is seen settling "somewhere between 60 and 61", with the breakeven point now expected below the prior $51m as conversion improves and a new leased warehouse replaces third-party distribution
On UK growth: the +35% first-five-week written orders growth flatters the picture given prior-year closures, with the like-for-like Nick Scali branded stores up 19% in 2H a better guide, and roughly 10 more stores needed to justify meaningful marketing spend
On conversion: with ANZ traffic down as much as 10-15% at times, focus has shifted to conversion, which is up, while average transaction values are holding
On capital and M&A: the stronger final dividend is unrelated to M&A, with a "stronger balance sheet than we've ever had", property independently valued at $208m against $43m of property debt, and management "always looking" at ANZ acquisitions
Company page: Nick Scali (NCK)
Charter Hall Retail REIT FY26 earnings call highlights
[12:14 pm] Management framed the result around a completed portfolio shift to net lease, an upcoming CPI-linked rent boost and confidence in convenience retail's supply-demand dynamics.
On strategy: "CQR has now curated the portfolio to its target mix of approximately 50% high quality shopping centers and 50% high quality net lease retail assets", with the net lease book "free of any material capital expenditure"
On the September CPI print: a key tailwind, with Ben Ellis noting "82% of our portfolio has got its rent review in the net lease sector of this upcoming September CPI print, which is going to be really strong"
On guidance: FY27 operating earnings of "no less than AUD 27.3 per unit, representing growth of no less than 3.5%", with no acquisitions or divestments assumed in that base
On value creation: net lease invested equity has "grown by 35% or AUD 317 million", achieved "through genuine rental growth rather than cap rate compression"
On supermarkets: MAT growth of 3.6% up from 2.5%, with tenants in turnover or within 10% of the sales threshold "now at 89%, an all-time portfolio record high"
On the demand backdrop: "Australia's population is expected to grow by more than 1 million people over the next three years, while new retail supply is forecast to reach a 30 year low", which Ellis sees as "a potential tailwind" in anchor lease negotiations
Company page: Charter Hall Retail REIT (CQR)
Brokers raise AMP targets as China partnerships and Platform flows outweigh Bank drag
[11:30 am] AMP's 1H26 result on Thursday landed broadly in line with its earlier trading update, with strength in Platforms and the China partnerships offsetting a weaker Bank, while management lifted the interim dividend above guidance and announced a further buyback. The stock rallied 6% on the day, and up 34% since the 16 July trading update.
JPMorgan retained Overweight, raised target from $2.09 to $2.40: Platforms and superannuation accelerated against softer industry flows, with China now nearing a third of earnings and surplus capital plus tax assets supporting further returns, while a Bank divestment was seen as potentially positive for shareholders.
UBS retained Buy, raised target from $2.55 to $2.61: Partnership forecasts were upgraded and Bank earnings downgraded, with conservative partnership guidance and expected consensus upgrades on Platform flows, though the attractive earnings outlook was viewed as already priced.
Goldman Sachs retained Neutral, raised target from $2.00 to $2.15: Underlying profit modestly beat consensus, with China partnership acceleration drivers not fully explained and return guidance viewed as conservative, while weak Bank returns remained the key drag.
James Hardie soars to a 12-month high
[11:02 am] James Hardie is up 4.6% in early trade after reporting a clean sweep of better-than-expected numbers for Q1, Q2 guidance and full-year guidance. The stock is now up 63% since the 18 May low, but trading flat over the past twelve months (suffered a ~27% one-day selloff on 20-Aug-25).
Q1 adjusted EBITDA of $422.1m vs $393.9m ests (7% beat), with cost synergies ahead of schedule
Q2 revenue guided to $1.485-1.575bn vs $1.33bn ests (15% beat at the midpoint)
Q2 adjusted EBITDA of $420-455m vs $367m ests (19% beat)
FY27 revenue guidance raised to $5.564-5.723bn from $5.25-5.41bn prior (6% upgrade), with adjusted EBITDA lifted to $1.536-1.625bn
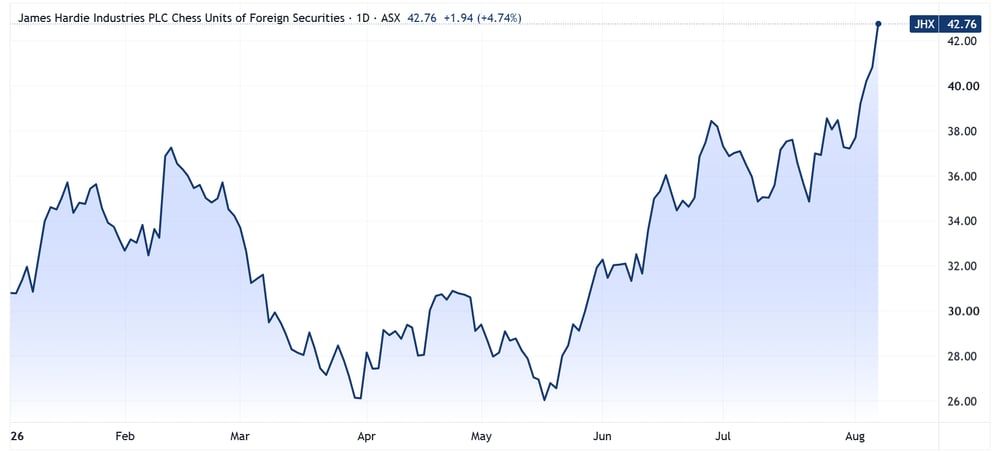
James Hardie year-to-date price chart (Source: TradingView)
Congo bans copper and cobalt concentrate exports, lifting copper to near-record highs
[10:59 am] The Democratic Republic of Congo has banned exports of copper and cobalt concentrates as it pushes to force domestic processing and capture more value from its minerals.
Ban effective immediately, though one-year waivers may be granted in strategic circumstances, with a new tax regime introduced for economically significant by-products
Repeals the 2023 export ban and its exemptions, replacing them with a broader framework as Congo leverages its position as the world's largest cobalt supplier
Limited impact expected for most operators, with the bulk of Congo's copper and cobalt already refined domestically, exporting 696,725 tonnes of cathodes in Q1 versus far smaller concentrate volumes
Ivanhoe's Kamoa-Kakula seen most exposed, with the Zijin joint venture having exported concentrate under multiple exemptions since 2021, though most is now smelted on-site or at Lualaba
Source: Reuters
ASX 200 slips as banks and healthcare stocks weigh
[10:34 am] The S&P/ASX 200 is down 38 pts (-0.40%) in early trade, following a five-day win streak where the index gained 3.4%.
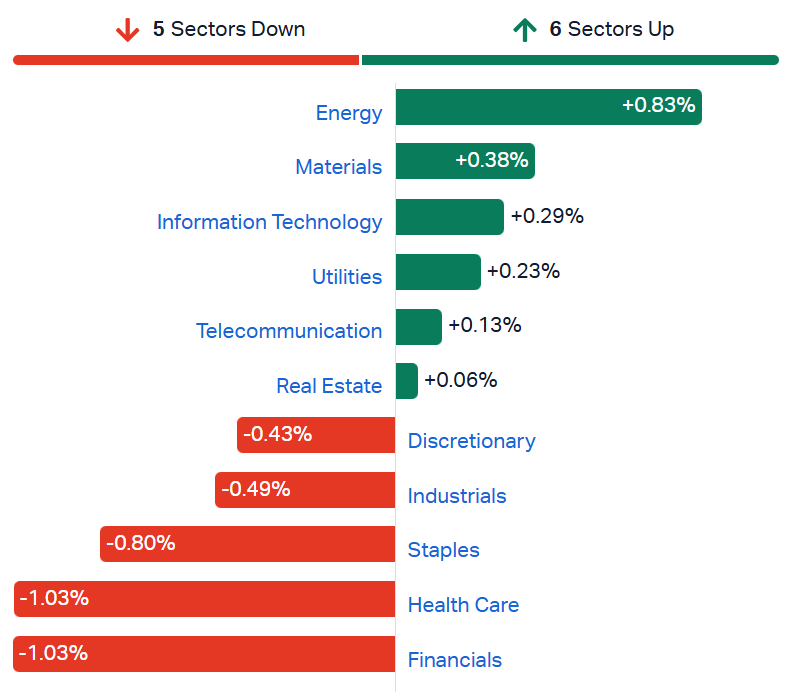
S&P/ASX 200 sectors (Source: TradingView)
Healthcare stocks are trading broadly lower, with the move headlined by a 5% dip for ResMed, after its Q4 result.
Ticker | Company | % Chg | Price |
|---|---|---|---|
4DX | 4DMedical | -7.54% | $4.29 |
RMD | Resmed | -5.07% | $29.89 |
MSB | Mesoblast | -2.02% | $2.19 |
EBO | Ebos Group | -1.46% | $18.28 |
FPH | Fisher & Paykel | -1.28% | $34.83 |
ANN | Ansell | -0.98% | $34.23 |
RHC | Ramsay Health Care | -0.86% | $43.94 |
SHL | Sonic Healthcare | -0.67% | $22.09 |
SIG | Sigma Healthcare | -0.50% | $2.98 |
COH | Cochlear | -0.49% | $125.37 |
CSL | CSL | -0.30% | $131.97 |
PME | Pro Medicus | 0.02% | $178.03 |
TLX | Telix Pharmaceuticals | 2.06% | $15.35 |
Banks are also under pressure, with most majors down around 1%.
Ticker | Company | % Chg | Price |
|---|---|---|---|
CBA | Commonwealth Bank | -1.62% | $176.96 |
MQG | Macquarie Group | -1.43% | $263.43 |
BEN | Bendigo & Adelaide Bank | -1.30% | $11.43 |
JDO | Judo Capital | -1.26% | $1.02 |
NAB | National Australia Bank | -1.25% | $42.17 |
WBC | Westpac | -1.09% | $38.11 |
ANZ | ANZ Group | -1.08% | $37.70 |
BOQ | Bank Of Queensland | -0.82% | $6.64 |
AMP holds onto gains after 33% profit jump and $150m buyback
[10:23 am] AMP shares rallied 5.9% on Thursday, to the highest since October 2018, after its first-half came in broadly in line with expectations, but the strength of its platform net flows is the most important number. Growing demand among both advisers and direct members has helped offset a fall in its banking division’s revenue and could position the company for further growth.
As part of Livewire Markets' reporting season coverage, we spoke to James van de Graaff from Fidelity about the outlook for AMP and what the result means for investors.
Top ASX 200 gainers and losers
[10:16 am] Lithium stocks top the leaderboard, James Hardie rallies on a bumper result (Q1 beat, Q2 guidance ahead and full-year guidance upgrade) and AMP continues to trend higher after yesterday's FY26 result. Meanwhile, healthcare stocks open broadly lower, while ResMed tanked on soft earnings/guidance.
Ticker | Company | % Chg | Price |
|---|---|---|---|
LTR | Liontown | 5.09% | $1.14 |
PLS | PLS Group | 4.88% | $4.51 |
JHX | James Hardie | 4.14% | $42.51 |
MI6 | Minerals 260 | 4.11% | $0.76 |
PDN | Paladin Energy | 3.36% | $10.16 |
AMP | AMP | 2.81% | $2.38 |
NXG | Nexgen Energy | 2.70% | $14.47 |
LNW | Light & Wonder | 2.46% | $120.98 |
BGL | Bellevue Gold | 2.20% | $1.49 |
WAF | West African Resources | 2.11% | $3.39 |
Ticker | Company | % Chg | Price |
|---|---|---|---|
4DX | 4DMedical | -7.97% | $4.27 |
ZIP | Zip Co | -5.07% | $2.81 |
XYZ | Block | -4.79% | $112.75 |
RMD | Resmed | -4.64% | $30.02 |
MSB | Mesoblast | -2.24% | $2.18 |
DRO | Droneshield | -2.19% | $2.23 |
ASX | ASX | -1.81% | $57.31 |
IPX | Iperionx | -1.76% | $3.34 |
EVT | EVT | -1.67% | $14.17 |
FPH | Fisher & Paykel | -1.64% | $34.70 |
Lycopodium wins $93m EPCM contract for Artemis Gold's Blackwater Phase 2 expansion
[9:43 am] Lycopodium has secured the EPCM contract for Artemis Gold's Expanded Phase 2 project at the Blackwater gold and silver mine in British Columbia.
Contract valued at around $93m within Artemis Gold's overall EP2 budget, delivered by Lycopodium's Canadian-based business
EP2 adds 13Mtpa of throughput, lifting Blackwater's total capacity to 21Mtpa and making it one of Canada's three largest gold mines
Builds on existing involvement, having delivered EPCM for Phase 1A and prepared the EP2 feasibility study and FEED for the new plant
Construction well underway, with major works started and the first concrete pour for the ball mill foundations completed ahead of schedule
Company page: Lycopodium (LYL)
James Hardie Q1 FY27 earnings call highlights
[9:41 am] Management pointed to a strong start to the year led by fiber cement, upgraded distribution reach and disciplined cost control against an uncertain housing backdrop.
On the quarter: "First quarter results were ahead of our expectations, led primarily by better than expected organic growth in our fiber cement business" against a macro backdrop that "remains uncertain"
On fiber cement: CEO Aaron Erter split the 20% organic growth into "a third, a third, a third" across strategic initiative execution, an easier destock comp, and price and mix, noting "our sell through for fiber cement really accelerated each month with June being our strongest with up 19%"
On the Boise Cascade deal: "This agreement makes Boise a national distribution partner across our entire portfolio", with Erter adding "Boise now has every reason to grow our brands and actively convert, because their success is directly tied to ours"
On costs: "We are holding our assumption of $80 million to $100 million of cost pressure in fiscal 2027", with freight the sticking point as "elevated spot rates and network dynamics are running above our original planning assumptions"
On the back half: "We continue to plan the back half prudently against an uncertain macro backdrop", framed as "being prudent" and normal seasonality rather than a demand change
On the SBC change: "starting in Q1, we are excluding share based compensation expense" from adjusted EBITDA, a move made "more comparable to our peers" after investor feedback
Company page: James Hardie Industries (JHX)
Charter Hall Retail REIT lifts FY26 earnings 4% and guides to further growth
[9:39 am] Charter Hall Retail REIT delivered a slight earnings beat and firmer valuations as it completed its shift towards convenience net lease assets, with FY27 guidance ahead of consensus.
Operating EPS of $0.264 vs $0.26 ests (2% beat), up 4.0% on FY25
FY distribution of $0.255, up 3.3%, with statutory NPAT up 78% to $389.4m
NTA up 8.4% to $5.03, driven by a $248m or 4.9% portfolio valuation uplift as the weighted average cap rate firmed 29bps to 5.45%
Occupancy at 99.1% with positive specialty leasing spreads of +4.1% and record specialty tenant retention of 86%
Gearing of 30.9% after refinancing the entire debt platform, cutting funding margins 40bps and lifting the weighted average cost of debt to 5.0%
FY27 guidance for operating EPS of no less than $0.273 (up 3.5%), the midpoint well ahead of $0.25 ests, and distributions of $0.264, also up 3.5%
Company page: Charter Hall Retail REIT (CQR)
ResMed Q4 earnings call highlights
[9:34 am] Management pointed to strong FY26 momentum, first-time FY27 guidance and a raft of portfolio and demand-generation tailwinds on the call.
On FY27 guidance: first-ever revenue and EPS guide, with core constant currency revenue growth of 5-7% and core EPS growth of 12-14% after stripping out MatrixCare and Noctrix dilution
On the Astral field action: a $42m Q4 provision covers the "total work that's needed for this field action globally", with an approximate $75m revenue and $0.15 EPS headwind from suspending FY27 sales, both baked into guidance
On GLP-1s: still a tailwind, with patients on both PAP and GLP-1 scripts around 11% more likely to start PAP therapy, though oral GLP-1s show "lower level of adherence and a lower level of weight loss" than injectables
On pricing: "very modest price increases" building through FY27 as inflation in electronic components and freight means productivity can no longer offset it alone, with growth still overwhelmingly volume-driven
On gross margin: low double-digit expansion guided for FY27 despite a slight Q1 decline, supported by supply chain productivity and US distribution network optimisation feathering in from Q2
On capital returns and M&A: over $1.85bn to be returned to shareholders in FY27, up more than 75%, alongside $100-500m tuck-in acquisitions in areas like the Noctrix RLS deal
Nick Scali grows FY26 profit 22% though revenue and NPAT land shy of estimates
[9:27 am] Nick Scali lifted full-year profit on stronger margins, but sales and earnings came in just below consensus as the ANZ retail backdrop softened.
Revenue of $516.7m vs $533.5m ests (3% miss)
EBITDA of $180.7m vs $182.4m ests (1% miss)
NPAT of $75.7m vs $76m ests (in line), up 22% year-on-year
Final dividend up to $0.39 fully franked from $0.33 a year ago
Group gross margin up 210bps, with ANZ revenue up 5.1% to $476.7m and the UK narrowing its net loss to $4.8m as gross margin jumped to 60.3% from 47.1%
FY27 off to a mixed start, ANZ written sales orders flat over the first five weeks against high single-digit growth a year ago while the UK surged 35%, with four new ANZ stores and one UK opening planned
Company page: Nick Scali (NCK)
Coles to send up to 1000 back-office jobs to India in Accenture outsourcing deal
[9:24 am] Coles is preparing to offshore hundreds to more than 1,000 corporate roles under an expanded multi-year partnership with Accenture as it cuts costs and invests in online, the AFR reports.
Up to 1000 jobs across marketing, finance, HR and technology to be outsourced, with most moving to India and some handled by Accenture locally
Deal worth hundreds of millions over multiple years, with cuts spread over time as functions are handed over, and retail store staff unaffected
Online competition the driver, with Accenture set to overhaul how Coles interacts with customers online as Amazon gains share in high-margin health, beauty and baby categories
Follows sector peers, with Woolworths moving hundreds of corporate jobs offshore in June and Qantas exploring a similar Accenture deal for up to 1000 roles
Consulting ties on the board, with directors including a former 16-year Accenture leader and CEO Leah Weckert a McKinsey alumna
Amazon investing heavily, having flagged more than $750m for a robot-run Queensland fulfilment centre on top of around $1.6bn over four years
Source: AFR
James Hardie beats on Q1 and lifts full-year guidance despite a soft US housing backdrop
[9:22 am] James Hardie topped estimates across Q1 and raised its FY27 outlook, crediting disciplined execution and above-market growth rather than any housing recovery.
Q1 revenue up to $1.48bn vs $1.46bn ests (1% beat)
Q1 net income ex-items of $209.3m vs $183.6m ests (14% beat)
Q1 adjusted EBITDA of $422.1m vs $393.9m ests (7% beat), with cost synergies ahead of schedule
Q2 revenue guided to $1.485-1.575bn vs $1.33bn ests (15% beat at the midpoint)
Q2 adjusted EBITDA of $420-455m vs $367m ests (19% beat)
FY27 revenue guidance raised to $5.564-5.723bn from $5.25-5.41bn prior (6% upgrade), with adjusted EBITDA lifted to $1.536-1.625bn and FCF reiterated at least $500m
Management said results reflected "disciplined execution and continued above-market growth, rather than a meaningful improvement in the underlying U.S. housing market", with more on long-term strategy due at its September Investor Day
Company page: James Hardie Industries (JHX)
ResMed lifts dividend 10% as Q4 earnings edge past estimates
[9:19 am] ResMed delivered a slight Q4 EPS beat and raised its dividend, capping a FY26 that saw double-digit revenue growth and margin expansion. NYSE-listed ResMed shares are down 5.9% after hours.
Q4 revenue of $1.46bn, in line with ests
Q4 EPS ex-items up to $0.295 vs $0.29 ests (2% beat)
Q4 operating income ex-items of $515m vs $525.3m ests (2% miss)
Q4 gross margin of 62.3% vs. 62.6% ests (30 bp miss)
Quarterly dividend up 10% to $0.66 from $0.60
FY26 revenue up 10% to $5.7bn vs. Morgans ests of $5.64bn (1% beat)
FY26 EPS up 17% to $11.17 vs Morgans' $10.98 ests (2% beat)
Company page: ResMed (RMD)
Woodside sells its 70% stake in Trinidad's Calypso project to bp
[9:15 am] Woodside has agreed to divest its operated interest in the Calypso Project in Trinidad and Tobago to joint venture partner bp, with terms undisclosed.
70% operated interest sold in production sharing contract TTDAA 14, with bp lifting its holding from the existing 30%
Cash plus contingent payments make up the consideration, though specific terms were not disclosed
Completion expected by end-2026, subject to customary conditions including government and regulatory approvals
Concludes a decades-long presence in Trinidad and Tobago that spanned the Ruby and Angostura offshore oil and gas operations
CEO Liz Westcott said the deal "further simplified Woodside's portfolio" and reflected a focus on opportunities with "the best potential to deliver sustained value for Woodside shareholders"
Company page: Woodside Energy (WDS)
Insider trades: Webjet CEO buys 250,000 shares
[9:11 am] Webjet CEO Nicole Sheffield purchased 250,000 shares on-market, valued at approximately $99,932 on 5 August 2026.
Sheffield was appointed as the company's new managing director and CEO on 15 July. Prior to joining Webjet, she was the managing director of Wesfarmers OneDigital.
US earnings wrap: Airbnb, Atlassian, Monster, MP Materials, Datadog and TripAdvisor
[9:05 am] A busy session of US quarterly results. Here are a few companies of interest.
Airbnb (+9.4% AH) beat across the board, revenue up 17% to $3.6bn vs $3.58bn ests (1% beat) and EPS up 33% to $1.37 vs $1.25 ests (10% beat), lifting FY26 guidance to at least mid-teens revenue growth and a 35.5%-plus adjusted EBITDA margin
Atlassian (+31.7% AH) delivered a strong Q4, revenue up 28% to $1.8bn vs $1.66bn ests (8% beat), cloud revenue up 31% to $1.2bn and RPO up 44% to $4.8bn, with Ken Exner appointed Chief Product Officer for Enterprise and Emerging
Monster Beverage (-0.3%) revenue up 20.2% to $2.54bn vs $2.43bn ests (5% beat) and adjusted EPS up 15.2% to $0.60 vs $0.58 ests (3% beat), with management noting international net sales rose 34.6% to "approximately 46 percent of total net sales" ahead of a two-for-one stock split trading from August 11
MP Materials (-0.8%) revenue up 89% to $108.5m vs $99.2m ests (9% beat) and NdPr sales up 127% to 1,006MT, though adjusted EBITDA of $28.5m was in line, as it signed a long-term gadolinium offtake with a new "U.S. aerospace and defense customer at attractive economics"
Datadog (-19.0%) revenue up 36% to $1.12bn vs $1.08bn ests (4% beat) and adjusted EPS up 41% to $0.65 vs $0.59 ests (10% beat), raising FY26 revenue guide to $4.45-4.47bn (midpoint 2% ahead of ests) as customers "observe, secure, and act on their AI-enabled solutions"
TripAdvisor (-25.5%) revenue down 7% to $441.9m vs $504m ests (12% miss) and adjusted EBITDA down 21% to $76.4m vs $82m ests (7% miss), with the TheFork sale expected by end-2026 to fund an "experiences-led strategy"
Oil climbs as Iran-Oman Hormuz deal looks set to fall short of a full reopening
[9:02 am] Crude extended gains after Iran reported strikes at the entrance to the Strait of Hormuz and signalled its proposed shipping pact would keep US and Israeli vessels out.
European natural gas futures spiked as much as 12% as traders priced in heightened risk to gas tankers transiting the strait
Deal seen falling short of a full resumption, with Iran seeking to bar US and Israeli ships, demand compensation from hostile countries and tie a reopening to the lifting of the US maritime blockade
Prices still down sharply on the week, Brent off around 20% over the past fortnight on hopes flows would soon increase before Thursday's setback
Saudi Aramco cut Arab Light to Asia by 50 cents to $2 under the regional benchmark, its fifth-lowest setting since 2000, with exports running near 5m barrels a day, about 70% of normal
Escalation risk persists, with a tanker reporting two explosions in the strait, a Houthi strike on a Saudi tanker in the Gulf of Aden, and Khamenei's sign-off on any deal still unclear
Dimon warns market leverage is 'pretty high', raising disruption risk
[9:01 am] JPMorgan CEO Jamie Dimon flagged elevated leverage across the financial system as a potential trigger for sudden market disruption.
Leverage running high across prime brokerage, hedge funds, ETFs and Treasury market arbitrage, Dimon told CNBC on Wednesday
Higher disruption risk when leverage builds, with a greater chance something rattles the market quickly
Situational Awareness cited as a recent example, the AI-focused hedge fund offloading part of its public stock book to Citadel after a tech selloff
Market coped well with that unwind, per Dimon, suggesting the system absorbed the stress
Source: Bloomberg
Australia posts surprise June trade surplus as commodity exports jump
[9:01 am] Australia unexpectedly swung to a trade surplus in June as exports rose the most in four years, led by commodities, while imports slipped.
$1.9bn surplus against forecasts for a $1.1bn deficit, reversing May's surprise shortfall
Exports up almost 10% month-on-month while imports fell 0.2%, lifting total exports to nearly $50bn, the highest since early 2023
Metal ores and minerals up 6.2% and coal, coke and briquettes up 4.6% on the month
Gold shipments topped $7bn in June and exceeded a record $40bn across the first half
Fuel imports above $6bn, the third-highest on record, as the Iran war lifts liquid fuel prices for a country reliant on imports
Outlook still deteriorating as the commodity boom winds down and data centre construction drives higher imports
Alphabet raises US$25bn in one of the year's most sought-after AI bond sales
[9:00 am] Alphabet's investment-grade offering drew roughly US$115bn of peak demand, signalling a rebound in appetite for AI-related debt after last month's tech bond selloff.
US$25bn raised across 10 tranches, with maturities from two to 40 years and peak demand of about US$115bn, behind only Oracle's and Amazon's deals earlier this year
Generous premiums drove interest, with the 40-year tranche pricing at 1.3 percentage points above Treasuries, tighter than initial talk of 1.55 points
Twice-yearly US issuance signalled to bond dealers, a message aimed at easing investor concerns over further tech debt supply
Alphabet now the biggest AI-related bond seller since 2025, with total issuance above US$114bn plus nearly US$85bn of shares sold
Backdrop had soured in July as Alphabet lifted its capex forecast to as much as US$205bn, more than double 2025's outlays, driving its first negative cash flow quarter since its 2004 IPO
Source: Bloomberg
China's cheap AI shifts investor focus from chipmakers to internet giants
[8:58 am] Falling AI costs are strengthening the case for China's internet stocks as value rotates away from hardware toward the companies that own consumer-facing applications.
KraneShares China Internet ETF up more than 20% since its June 25 low, roughly double the Hang Seng's gain, while the Philadelphia Semiconductor Index has fallen about 11%
Blended inference prices down 36% from their May peak, per Silicon Data, even as customers adopt more capable reasoning models and AI agents
Cheaper tokens seen as margin positive for Chinese hyperscalers, with Alibaba and Tencent rallying on expectations that lower costs spur AI demand among them and their clients
Alibaba Cloud estimated to have grown 45% in the June quarter, with Goldman preferring cloud and data centre names on accelerating token growth, rising second-half capex and increasing domestic chip supply
Microsoft's Nadella echoes the theme, arguing AI models are becoming interchangeable inputs so value accrues to owners of customer relationships and software platforms
Source: Bloomberg
'Sell America' trade resurfaces as Washington policy uncertainty weighs on bonds and the dollar
[8:55 am] Global investors are debating whether to revive last year's 'Sell America' trade after a run of Fed and Treasury policy decisions unsettled the bond and currency markets.
30-year Treasury yield above 5%, its highest since 2007, though it has retraced some of the move since the Fed meeting
Dollar weaker against nearly every G10 currency over the past month despite higher US yields, which would normally support it, with the Bloomberg Dollar Spot Index down around 2% since its June peak
Two policy triggers cited: Fed Chair Warsh's sparse communication style raising inflation-fighting doubts, and Treasury's first coordinated effort in almost 30 years to help Japan prop up the yen
Japan spillover risk flagged, with the largest foreign holder of US debt potentially forced to sell part of its $1trn-plus Treasury holdings to fund intervention
30-year term premium at 1.56%, the highest since 2013, as the Treasury lifts current-quarter borrowing needs to $739bn
Source: Bloomberg
Good morning!
[8:30 am] ASX 200 futures are down 4 pts (-0.04%). Here's what happened overnight:
A relatively uneventful session as the pullback continues after major US benchmarks rallied 4-5% in the past couple of sessions
Major US benchmarks finished mostly lower on weak breadth. The Dow lagged and trended lower intraday, snapping a five-day win streak, while the S&P 500 and Nasdaq closed marginally lower
Iran said its Hormuz shipping agreement with Oman is agreed in principle, but Tehran warned it will not automatically reopen the strait and shipping lobbies attacked the proposed transit fees, Brent rallied 4.6% to US$83.09 overnight
Notable session for software names, with Datadog posting its worst day on record and HubSpot its biggest fall since listing, despite reporting beat-and-raise results, while storage names dragged the chip complex lower