ASX 200 Live Today - Friday, 28th August
The S&P/ASX 200 is trading higher as Tech stocks bounce, Miners and Banks trade higher and consumer-facing sectors continue to slip.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Friday, August 28. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
Reporting season is heating up and we've got you covered. Our reporting season calendar has over 250 stocks plus earnings and dividend estimates.
Thanks for following our August reporting season coverage
[2:30 pm] That's a wrap! I've tried to cover everything under the sun, but the volume of announcements these last few days has far outpaced what I can put out. St Barbara's dividend surprise and WAM's FY27 dividend cut were two I would have liked to publish before the open. Thank you all for reading along. I hope the blog has added something useful to your investing and trading through what's been a volatile stretch for the market.
If you have any feedback and questions, you know where to find me ([email protected]).
Dicker Data rockets to all-time highs
[1:55 pm] Dicker Data, what a move, up ~16% on results, now up almost 60% year-to-date.
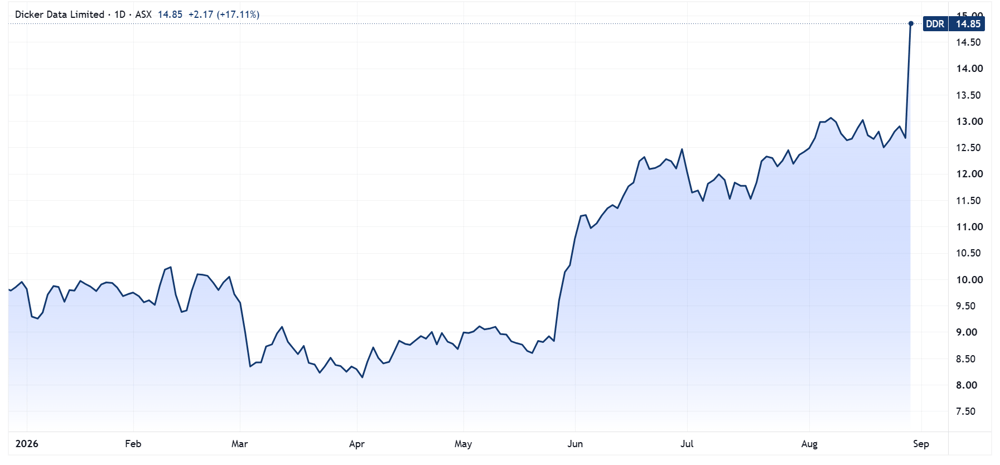
Dicker Data chart (Source: TradingView)
The stock experienced a brief intraday pullback but now back near session highs.
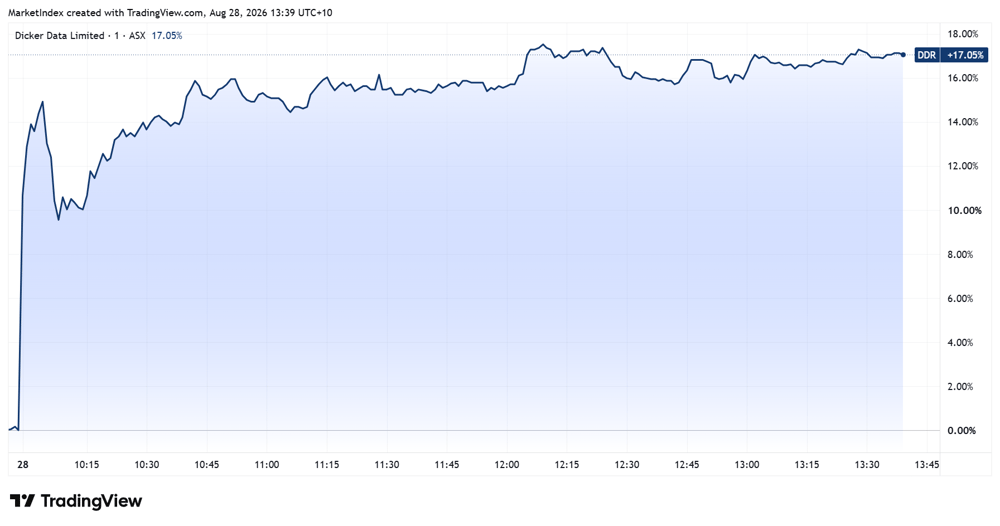
Dicker Data intraday chart (Source: TradingView)
The result was a clean one, with key metrics like gross margin topping ests by 40 bps, and most earnings-related metrics ~10% ahead of estimates. Guidance was also ahead.
Gross revenue up 14.2% to $2,100.9m vs $2,073.5m ests (1.3% beat)
Australian gross revenue up 18.3% to $1,831.5m with PBT up 55.9% to $82.5m, while New Zealand gross revenue fell 7.6% to $269.4m and PBT fell to $4.0m on softer conditions and FX translation
Recurring gross software sales up 20.7% to $600.0m, with Software adding $97m and Advanced Solutions $71m, and record first-half AI invoiced value above $50m
Gross profit up 23.0% to $205.6m vs $195.9m ests (5.0% beat), with gross margin up 70bps to 9.8% against 9.4% ests
EBITDA up 37.3% to $103.5m vs $93.4m ests (10.8% beat)
Net operating profit before tax up 50.1% to $86.4m vs $75.2m ests (14.9% beat), with PBT margin of 4.1% against 3.6% ests
No interim dividend was announced with the result
FY26 guidance of gross revenue $4.3-4.4bn and PBT $162-165m implies second-half PBT of roughly $77m, still 6.6% above the $72.3m consensus for the half but down about 11% on the first half
St Barbara surges 20% on $500m cash gain and maiden dividend
[1:02 pm] St Barbara has caught an aggressive bid today, after its FY26 highlighted the Lingbao transaction, which transformed the balance sheet and funded a maiden fully franked dividend, though the underlying business remains loss-making. The stock opened 7.5% higher ($0.71) and currently up 20% to 80 cents.
Statutory profit after tax of $490m against a restated $94m loss in FY25, driven almost entirely by a $500m gain on deconsolidation of New Simberi Gold following the Lingbao transaction
Underlying loss after tax of $29m, widening from a $18m loss in FY25
New Simberi Gold delivered an underlying profit of $40m for the first nine months of FY26, against a $30m underlying loss across the full 12 months of FY25, the clearest evidence the asset was turning before deconsolidation
Net assets up 148% to $928m, with cash of $475m against $157m, no debt and no hedging
Maiden fully franked dividend of 5.0cps declared, with $355m of statutory profit transferred to a distributable reserve and the franking balance falling from $97m to $71m post-payment
A buy-back of up to 100 million shares is under consideration but deferred until the updated 15-Mile Processing Hub pre-feasibility study lands at the end of September, making that release the next catalyst
Even at the current price ($0.80) that's 5 cent dividend is yielding ~6.2%. Pretty massive. I wrote about St Barbara at the start of the year, since it was (back then) at ~$740m market cap company, with $157m cash and no debt as at 30 September 2025, and $370m cash due from the Lingbao transaction.
Company page: St Barbara (SBM)
Virgin Australia FY26 earnings call highlights: demand, pricing and the cost squeeze
[12:33 pm] Management fielded repeated questions on whether the strong revenue environment is durable or simply a response to higher fuel costs.
On demand across segments: "The demand in the market remains really strong. We are seeing that in leisure. We are seeing that in B2B, both corporate and SME. Based on that, we feel really good about the demand outlook for the half"
On whether the RASK guide marks a change in trajectory: "The TRASK in half two was 5.3%. Quarter four was 6.4%. Your commentary around a change of trajectory for half one FY27, we are guiding 6%-8%. It is consistent with recent performance from our point of view"
On cost inflation shaping pricing discipline: "Post Iran crisis, we are expecting continued cost inflation that is above CPI in the industry and in our airline. We will need to continue being really disciplined around RASK growth to ensure that we do not have margin dilution as a result of that"
On competitor baggage changes and ancillary pricing: "The changes that were announced in the market around baggage, and that is a significant change, we don't at this point plan a change to our baggage policies, and therefore it's effectively for those customers a price increase for many of them... That means that we obviously will be reviewing how we handle that from a pricing point of view"
On the forward booking environment and capacity discipline: "Demand in forward bookings remains strong, with consumers continuing to prioritize travel. Against that backdrop, we remain disciplined on capacity. Domestic capacity is expected to reduce by around 3% in the first half of FY27"
On resource sector and regional demand: "We have been careful around the network discipline both to date and forward because we are seeing really strong demand, for example, intra-WA, and we've been having some success with our WA B2B clients"
Company page: Virgin Australia Holdings (VGN)
Top ASX 200 gainers
[11:29 am] Tech stocks are surging off the back of big overnight moves for US software names, energy, gold and lithium stocks are also trading broadly higher.
Ticker | Company | % Chg | Price |
|---|---|---|---|
XRO | Xero | 7.62% | $87.96 |
360 | Life360 | 5.01% | $20.98 |
LTR | Liontown | 4.98% | $1.20 |
IPX | Iperionx | 4.78% | $3.07 |
TNE | Technology One | 4.77% | $33.15 |
WTC | Wisetech Global | 4.73% | $41.42 |
KAR | Karoon Energy | 4.13% | $1.77 |
PME | Pro Medicus | 4.04% | $186.48 |
AAI | Alcoa Corporation | 3.83% | $71.53 |
NXT | NextDC | 3.61% | $14.07 |
VUL | Vulcan Energy Resources | 3.49% | $2.67 |
ZIP | Zip Co | 3.32% | $2.65 |
PLS | PLS Group | 3.30% | $5.32 |
ELV | Elevra Lithium | 3.22% | $8.65 |
XYZ | Block | 3.10% | $118.43 |
4DX | 4Dmedical | 3.02% | $3.75 |
MSB | Mesoblast | 2.90% | $2.48 |
VAU | Vault Minerals | 2.73% | $6.97 |
TLX | Telix Pharmaceuticals | 2.70% | $16.00 |
IGO | IGO | 2.53% | $8.50 |
Top ASX 200 losers
[11:29 am] Pexa tumbles on a disappointing FY27 guidance, while staples and real estate names continue to soften.
Ticker | Company | % Chg | Price |
|---|---|---|---|
PXA | Pexa Group | -18.36% | $6.61 |
INA | Ingenia Communities Group | -4.94% | $3.66 |
PPT | Perpetual | -3.46% | $19.53 |
WPR | Waypoint Reit | -3.29% | $2.35 |
IRE | Iress | -3.26% | $5.80 |
EOS | Electro Optic Systems | -3.18% | $10.66 |
GGP | Greatland Resources | -2.83% | $12.69 |
MFG | Magellan Financial Group | -2.74% | $9.24 |
CNI | Centuria Capital Group | -2.52% | $1.16 |
TUA | Tuas | -2.29% | $2.13 |
LOV | Lovisa | -2.23% | $26.30 |
ARF | Arena Reit | -2.14% | $2.29 |
DBI | Dalrymple Bay Infrastructure | -2.10% | $5.13 |
SGP | Stockland | -1.92% | $4.34 |
NEU | Neuren Pharmaceuticals | -1.86% | $20.63 |
REH | Reece | -1.85% | $16.42 |
HVN | Harvey Norman | -1.78% | $4.42 |
NEC | Nine Entertainment Co | -1.54% | $0.96 |
WOW | Woolworths Group | -1.52% | $38.95 |
SUN | Suncorp Group | -1.43% | $18.58 |
WAM Capital halves FY27 dividend target as profits reserve runs down
[11:13 am] WAM Capital has maintained its FY26 dividend but flagged a near halving of the FY27 target, after seven years of paying out more than the portfolio earned.
Final dividend of 7.75cps, partially franked at 60%, taking the FY26 full year dividend to 15.5cps, unchanged since FY20
FY27 full year dividend target cut to 8.0cps, comprising 4.0cps interim and 4.0cps final, a 48% reduction on the FY26 payout
The profits reserve will stand at 5.6cps after the final dividend is paid, below the 7.75cps needed to fund an FY27 interim at the current rate, which is what forced the reset
Portfolio performance to 27 August is expected to add roughly 1.3cps to the reserve, taking available capacity to about 6.9cps, still short of the 8.0cps target and dependent on further FY27 gains
The investment portfolio fell 10.5% in FY26 against the All Ordinaries Accumulation Index up 5.7% and Small Ordinaries up 8.1%, an underperformance of more than 16 percentage points
Management attributes the drag to consumer discretionary holdings, multiple compression in small and mid-cap technology, and stock-specific events at Corporate Travel Management and Tuas, and argues an RBA turning point sets up a rebound in FY27
As a bit of a dividend darling, you can't do this. WAM was obliterated this morning, opening the session 7.2% lower ($1.40) and now down 16.2% ($1.26).
Company page: WAM Capital (WAM)
Bond market wants a hawkish Warsh at Jackson Hole
[11:08 am] Investors at JPMorgan, Apollo and Morgan Stanley are pressing the Fed Chairman to deliver a clear rebuke of inflation on Friday, with the long end of the Treasury curve the main thing at stake.
The 30-year yield sat at 5.19% in early Friday trade after touching 5.34% last week, the highest since 2007, and has held above 5% for two months despite Bessent's interventions including a long bond buyback plan
The argument from JPMorgan is that a clear commitment to price stability would compress term premium, currently near levels last seen in 2014 on the New York Fed gauge, and restore some of the credibility lost since July
Apollo's Torsten Slok warns that an absence of framework guidance risks a much higher move in long rates, while JPMorgan's rates desk expects a walk-back would bearishly flatten the curve
Markets are pricing roughly a 35% chance of a quarter-point hike at the 16 September meeting, with the two-year still trading above fed funds, reflecting an uncertainty premium around Warsh rather than a settled view
Source: Bloomberg
ASX 200 higher as Tech, Banks and Energy stocks bounce
[11:03 am] The S&P/ASX 200 is up 35 pts (+0.39%) as tech bounces after a 5.7% skid in the last two sessions, financials catch a bid from 10-week lows and energy tries to snap a three-day pullback.
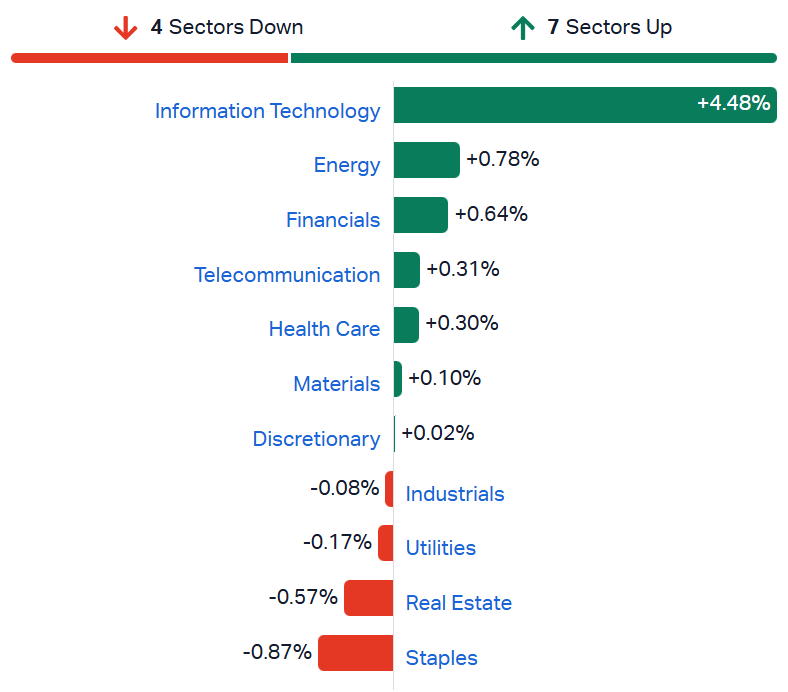
S&P/ASX 200 sectors (Source: Market Index)
Dicker Data beats hard on first half margins
[9:48 am] Dicker Data delivered sharp earnings growth in 1H FY26 on AI infrastructure and refresh demand, comfortably beating consensus on margins, with full-year guidance implying a softer second half.
Gross revenue up 14.2% to $2,100.9m vs $2,073.5m ests (1.3% beat)
Australian gross revenue up 18.3% to $1,831.5m with PBT up 55.9% to $82.5m, while New Zealand gross revenue fell 7.6% to $269.4m and PBT fell to $4.0m on softer conditions and FX translation
Recurring gross software sales up 20.7% to $600.0m, with Software adding $97m and Advanced Solutions $71m, and record first-half AI invoiced value above $50m
Gross profit up 23.0% to $205.6m vs $195.9m ests (5.0% beat), with gross margin up 70bps to 9.8% against 9.4% ests
EBITDA up 37.3% to $103.5m vs $93.4m ests (10.8% beat)
Net operating profit before tax up 50.1% to $86.4m vs $75.2m ests (14.9% beat), with PBT margin of 4.1% against 3.6% ests
NPAT up 54.1% to $60.7m
No interim dividend was announced with the result
FY26 guidance of gross revenue $4.3-4.4bn and PBT $162-165m implies second-half PBT of roughly $77m, still 6.6% above the $72.3m consensus for the half but down about 11% on the first half
Management flagged the drivers of that step down: lower-margin AI revenue accelerating, higher prices likely reducing unit demand, and component and supply chain constraints lifting inventory replenishment costs
Company page: Dicker Data (DDR)
Bisalloy earnings fall as Chinese plate pressures the core
[9:44 am] Bisalloy delivered lower FY26 earnings as softer resources demand and imported Chinese plate weighed on the domestic wear and structural business, offsetting sharp growth in armour.
Revenue down 10.6% to $136.6m
Operating EBITDA down 13.2% to $27.7m
NPAT attributable to members down 14.4% to $16.8m
EPS down 14.7% to 34.9cps
Fully franked final dividend of 13.0cps declared
Armour and Protection plate volumes into global markets up 229%, or 187% including domestic volumes and excluding AUKUS, the clearest evidence the defence pivot is converting into orders
July 2026 brought the first order to supply HY80 steel to the US submarine industry, the first time Australian-made steel will be used in Virginia-class construction, following qualification to the US Navy's TP300 standard
Chinese joint venture contribution up to $3.0m from $2.8m on a better mix of higher-value BISPLATE product, while the Indonesian business cut headcount 22% amid import licensing obstruction
FY27 framed as another year of investment with the focus on execution milestones rather than near-term earnings growth, funded from operating cash flow with no net debt
Company page: Bisalloy Steel Group (BIS)
Jupiter declares 0.75 cps final dividend
[9:42 am] Jupiter Mines has declared an unfranked final dividend for the six months to 30 June, following a ZAR350m distribution from its Tshipi manganese joint venture.
Unfranked final dividend of 0.75cps declared, with a record date of 4 September and payment on 18 September
The dividend follows Tshipi's decision to declare a ZAR350m final dividend to its shareholders for the second half of FY26
Management notes the payout again exceeds what Jupiter will actually receive from Tshipi for the period, meaning the company is drawing on its own balance sheet to sustain the distribution
Cumulative dividends now total $450m, or 23cps per share, over the past eight years
Tshipi has more than 100 years of resource life remaining at current production run rates, per the company
Company page: Jupiter Mines (JMS)
PEXA guides FY27 well below ests as volumes soften
[9:39 am] PEXA beat on FY26 EBITDA but missed on revenue, and FY27 guidance lands materially short across the board.
Note: The below ests refer to Macquarie forecasts, not consensus
Group revenue up 7% to $406.9m vs $414.8m ests (1.9% miss)
Group EBITDA up 12% to $151.7m vs $147.0m ests (3.2% beat), with margin up 1.7ppt to 37.3%
Australia revenue up 8% to $345.6m vs $344.6m ests (in line), on transaction volumes up 6.4% to 4.7m and average revenue per transaction up 2.2% to $80.6
International revenue up 1% to $61.3m vs $70.2m ests (12.7% miss), the source of the group revenue shortfall, with the EBITDA loss widening to $41.1m from $37.8m
Group NPATA up 35% to $65.3m
Group core NPAT of $26.3m, with EPS from continuing operations of 10.91cps against a loss of 37.07cps in FY25
No dividend declared, in line with ests of nil
Free cash flow up 39% to $93.5m, funding $92.4m of net debt repayment and taking leverage from 1.8x to 1.0x, with net debt down 35% to $158.7m
FY27 revenue guidance of $385-415m sits 6.7% below ests at the midpoint, with management flagging that Australian transfer volumes softened in July 2026
FY27 EBITDA margin guidance of 31.5-33.5% implies roughly $130m at the midpoint, 10.2% below ests and a step down of about 500bps from FY26
FY27 NPAT guidance of $5-20m, unclear if comparable to underlying NPAT est of $27.2m
IPART's draft report proposes a 20% cut to regulated revenue from FY28 with CPI increases thereafter, roughly $70m of revenue, with the final report due by 30 September
Company page: PEXA Group (PXA)
Westgold lifts capital returns by 329% and resets policy
[9:27 am] Westgold has declared a 10 cents per share fully franked FY26 dividend and adopted a new shareholder return policy, in a capital management release ahead of the full FY26 result.
Fully franked FY26 dividend of 10cps declared, a total payment of around $95m and 400% above the 2cps minimum annual commitment
Total FY26 capital returns up 329% to approximately $122m, comprising the $95m dividend and $27m of on-market buy-backs to 30 June
The $95m dividend represents just 16% of FY26 free cash flow of $602m, leaving substantial headroom given the new policy caps total returns at 30% of free cash flow
New FY27 Shareholder Capital Return Policy lifts the minimum annual return to 3cps, comprising a minimum 2cps ordinary dividend with the balance via buy-backs or additional dividends
FY27 buy-back extended to 10 September 2027 for up to $50m, subject to a 5% limit on issued capital
Company page: Westgold Resources (WGX)
Ashley Services swings back after a difficult FY25
[9:25 am] Ashley Services delivered a sharp earnings recovery in FY26 and reinstated a final dividend, with a large labour hire acquisition set to drive FY27.
Revenue up 16.7% to $602.2m
EBITDA up 70% to $14.7m
NPAT up 190% to $6.3m
EPS up 186% to 4.32cps
Fully franked final dividend of 1.15cps, taking the FY26 total to 2.55cps against 0.8cps in FY25, a payout ratio of 60% of distributable profits
Operating cash flow down to $7.2m from $8.9m, with the $6m EBITDA uplift offset by a $4.3m increase in working capital tied to revenue growth, so cash conversion is the line to watch as the business scales
Net debt down $1.8m to $9.4m, with the invoice financing facility lifted from $35m to $50m in July and the debt to EBITDA covenant replaced by an interest coverage ratio
Some pretty interesting numbers for a $40m market cap company. The final dividend implies yield of 4.2% based on yesterday's close of 27 cents. The stock is extremely illiquid (just 877 shares traded yesterday).
Company page: Ashley Services Group (ASH)
Virgin Australia declares first dividend since re-listing
[9:16 am] Virgin Australia beat on earnings and delivered margin expansion in FY26, enabling its maiden dividend since returning to the ASX.
Note: comparisons below are to UBS ests only, not consensus.
Airlines revenue up 8.0% to $6.0bn vs $6.03bn ests (in line)
RASK up 5.9% against CASK up 5.1%, though CASK ex-fuel rose 7.0% on airport charges, labour and depreciation. Passengers up 3.2% to 21.3m vs 21.1m ests (0.8% beat)
RASK is revenue per available seat kilometre, CASK is the cost per available seat kilometre, CASK ex-fuel is a bit more useful since fuel is largely outside of management control
Group underlying EBIT up 13.4% to $753m vs $726m ests (3.7% beat)
Velocity underlying EBIT up 12.3% to $143m vs $142m ests (in line) on revenue up 8.1% to $487m, in line, though FY27 EBIT is guided broadly flat as RBA interchange fee changes from 1 October and transformation investment offset billings growth of 12.4%
Underlying NPAT up 21.9% to $404m
Underlying EPS up 12.9% to 50.9cps vs 47.9cps ests (6.3% beat)
Fully franked dividend of 7.6cps declared vs. ests of nil
Net debt of $1.2bn at 0.9x underlying EBITDA well inside the $1.72bn ests and below the 1-2x target range, leaving available liquidity of $1.6bn
FY27 guidance points to 1H underlying EBIT broadly in line with 1HFY26, with domestic capacity down 3%, RASK growth of 6-8% in 1H27 ahead of CASK ex-fuel growth, fuel costs of around $700m and capex of $0.9-1.0bn against $880m ests
UBS has FY27 Velocity EBIT growth of ~8% in FY27, so today's guidance to be 'broadly in line' is a sizeable miss. FY27 capex of $0.9-1bn also 8% above UBS ests, reflecting the five 737-8 MAX and two E190-E2 purchases. Rask growth of 6-8% in 1H27 vs. UBS has 3% for the full-year, so possibly materially stronger pricing assumptions.
Company page: Virgin Australia Holdings (VGN)
Elevra swings to profit in first year as a merged group
[9:12 am] Elevra Lithium delivered a sharp earnings turnaround in FY26, its first result since the Sayona and Piedmont merger, driven by realised price gains and a large impairment reversal.
Revenue up 39% to US$202m, with average realised prices up 57% to US$1,092/dmt FOB more than offsetting a 13% fall in sales volumes to 181,494dmt
Spodumene concentrate production down 3% to 197,967dmt, with a record 22,202dmt in May
Unit operating cost sold up 2% to US$853/dmt FOB
Underlying EBITDA of US$14m, a US$57m improvement on the pcp, including US$46m from NAL, with merger cost synergies of US$15m over the ten months as a combined group
NPAT of US$44m, a US$292m swing from the pcp
Heavily flattered by US$62m of non-cash extraordinary items including a US$156m NAL impairment reversal offset by US$104m of merger accounting impacts
Closing cash of US$255m, up US$208m, after a US$202m equity raise that fully funds the NAL Brownfield Expansion, with Stage 1 due to lift capacity 15-20% from mid-CY27
FY27 guidance of production 198,000-210,000dmt and sales 200,000-230,000dmt implies volume growth, but unit cost sold guidance of US$880-950/dmt points to roughly 7% cost inflation at the midpoint, with capex of US$120-140m stepping up sharply from US$24m in FY26
Company page: Elevra Lithium (ELV)
McMillan Shakespeare posts record FY26 profit on margin expansion
[9:10 am] McMillan Shakespeare delivered double-digit earnings growth in FY26, missing slightly on revenue but beating on margins, earnings and the dividend.
Revenue up 6.8% to $602.1m vs $616.3m ests (2.3% miss)
EBITDA up 14.1% to $180.7m vs $178.6m ests (1.2% beat), with operating margin up 250bps to 41.5%
Statutory NPAT up 11.4% to $106.7m vs $106.8m ests (in line)
Underlying NPATA up 13.8% to $107.9m vs $106.8m ests (1.0% beat)
Fully franked annual dividend of 132.0cps vs 127.0cps ests (3.9% beat), a 6.6% yield, with the balance sheet at 0.4x debt to EBITDA and no facilities maturing in the next 12 months
Novated leases under management up 13.5% to 90,000 and sales up 8.4%, with Oly novated sales up 77% and BEVs now 57% of new novated leases, up from 31% in FY25
FY27 outlook points to July novated sales up 8%, with remarketing income supported by elevated EV demand though softer for used ICE vehicles, and NDIS reform the key watch item for Plan Management
Company page: McMillan Shakespeare (MMS)
Civmec beats across the board with order book at $1.4bn
[9:03 am] Civmec delivered FY26 earnings comfortably ahead of ests, with margin expansion and a diversified award pipeline underpinning the result.
Note: The below ests refer to Morgans forecasts, not consensus.
Revenue up 11.4% to $903.0m vs $882.9m ests (2.3% beat)
EBITDA up 17.0% to $107.3m vs $101.0m ests (6.2% beat), with EBITDA margin of 11.9%
NPAT up 22.5% to $52.1m vs $48.5m ests (7.4% beat), a net profit margin of 5.8%
EPS up 22.2% to 10.23cps vs 9.5cps ests (7.7% beat)
Final dividend of 3.5cps fully franked, taking the FY26 total to 6.0cps, in line
Order book of $1.4bn at 31 July, below the $1.5bn flagged in recent commentary, though management points to very strong tendering activity and a growing pipeline of early contractor involvement and pre-FEED work
Cash and equivalents of $54.6m against borrowings of $60.0m, with operating cash flow before working capital up 20.0% to $107.2m, the drawdown reflecting working capital investment to support higher activity levels
Company page: Civmec (CVL)
Synlait flags second-half swing back to profit
[9:02 am] Synlait has pre-announced FY26 earnings ahead of its 28 September result, pointing to a materially improved second half after a heavily loss-making first six months.
Reported EBITDA of -$2m to $3m for FY26, implying a second-half reported EBITDA of roughly $33-38m against the -$34.7m loss booked in the first half
Underlying EBITDA of $36-41m, with the roughly $38m gap to reported earnings reflecting items still subject to audit and impairment testing
Reported net loss after tax of -$70m to -$75m, implying the second half turned positive by around $6-11m after a -$80.6m first-half loss
Underlying net loss after tax of -$19m to -$24m
The update is preliminary and remains subject to external audit, impairment testing and finalisation of the 2025/26 season Milk Price, so the ranges could move
Acting CEO Leon Fung framed the result as evidence the recovery roadmap is working while conceding the numbers remain a long way from where the company wants them
Company page: Synlait Milk (SM1)
Hormuz diplomacy gathers pace but oil stays hostage to Washington
[9:00 am] Regional mediators intensified efforts to reopen the Strait of Hormuz this week, though the US has ruled out returning to the collapsed June memorandum, leaving crude caught between competing signals.
A WSJ report noted that Washington has told mediators it has no interest in reviving the June MoU, reversing three days of declines. Both contracts were still down more than 5% for the week
Iran and Oman have agreed a temporary joint shipping corridor through the strait, with two-way lanes about seven nautical miles wide, but Tehran says implementation is conditional on the US lifting the naval blockade, releasing frozen funds, imposing no new sanctions and halting military escalation. Iran's security chief says a formal list of conditions is being drawn up
Physical flows remain close to nil despite Trump's claims the strait is open. Kpler data showed five vessels crossed on Wednesday, down from seven, and CENTCOM has now redirected 75 ships since the blockade resumed on 14 July. A tanker was struck by an unknown projectile in the strait this week
Operation Economic Outcast has so far been more threat than action, with no major Chinese banks designated and Beijing publicly refusing to enforce the measures. Trump declined to confirm whether Chinese institutions would be targeted, which caps the near-term supply risk premium but leaves it live
Fed hawks turn up the volume at Jackson Hole
[8:55 am] Three regional Fed presidents used the opening of the Jackson Hole symposium to warn that US inflation is proving stubborn, with one openly calling for a hike.
Cleveland's Beth Hammack was the most hawkish, saying now is the time to act, having already dissented in favour of a quarter-point rise at the July meeting. She sees inflation ending 2026 around 3% and only reaching the mid-2s at best by end-2027
Kansas City's Jeffrey Schmid questioned whether the current 3.50-3.75% policy rate is restricting anything at all, though he wants more clarity on the demand side before committing to a September move
Chicago's Austan Goolsbee struck a more balanced tone, calling the three-month inflation trend not terrible and leaving the door open to cuts if inflation converges on 2%, while flagging Iran-driven energy prices and tariff volatility as pressures on households
The July FOMC vote was 9-3 to hold, and the minutes showed hawkish sentiment extended beyond the three dissenters, with some arguing an earlier hike could avoid a sharper tightening cycle later
July PCE came in at 3.7% year-on-year with core at 3.3%, more than five years above the 2% target, and Hammack's concern is that an inflationary mindset becomes embedded in household and business behaviour
Futures markets are pricing against a September hike but assign strong odds to one by year end
US software stocks back at breakeven for the year
[8:52 am] The iShares Expanded Tech-Software ETF rallied 7.7% overnight, largely thanks gains from Salesforce (+22.5%), CrowdStrike (+20.50%) and ServiceNow (+10.4%). The ETF is now up 6.5% year-to-date, trading at the highest since November 2025. It's a bullish sign that life is coming back to the software sector, though I'm not sure we can say the same about our local software names (Wisetech dipped 10% on results day, PME has given back almost the entirety of its 11.8% rally on 18-Aug, Life360 down 32% since its result on 10-Aug etc).
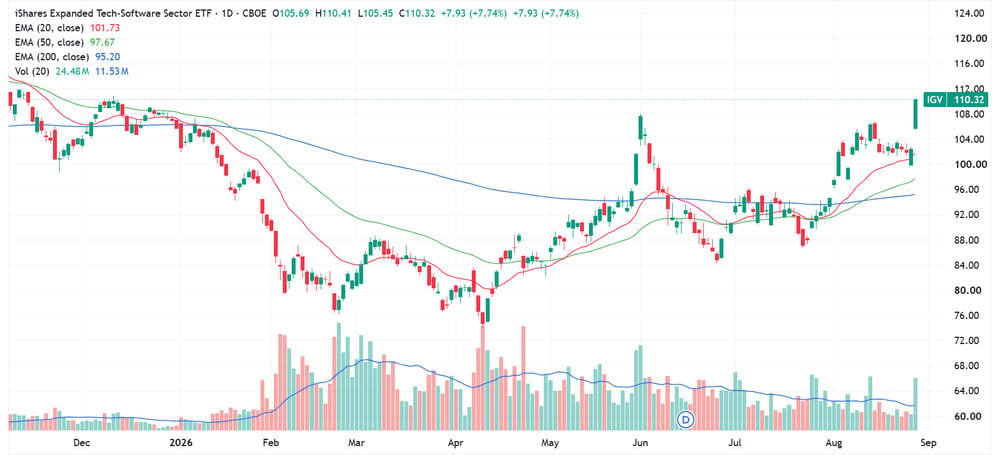
iShares Expanded Tech Software ETF daily chart (Source: TradingView)
Salesforce EPS blows past ests on AI momentum
[8:44 am] Salesforce delivered an in line revenue result in Q2 FY27 but a dramatic earnings beat, and lifted full-year guidance sharply. The stock rallied 22.5%, and a big driver of software related ETFs like the iShares Expanded Software ETF (+7.7%) and Global X Cloud Computing ETF (+5.2%).
Revenue up 11% to $11.3bn vs $11.32bn ests (in line)
Adjusted EPS up 103% to $5.90 vs $3.27 ests (80% beat)
cRPO up 14% in constant currency to $33.5bn, with total remaining performance obligation up 11% to $66.3bn
AI and data ARR up more than 210% to roughly $3.9bn, the standout metric and the clearest evidence yet that Agentforce is monetising
Free cash flow up 81% to $1.1bn, with operating cash flow up 71% to $1.3bn
FY27 guidance raised to revenue of $46.1-46.4bn vs $46.11bn ests (0.3% beat) and adjusted EPS of $16.67-16.71 vs $14.14 ests (18% beat), with non-GAAP operating margin of 34.3%
Nvidia lifts the market: Q2 beats across the board and Q3 guidance above consensus
[8:09 am] Nvidia shares rallied 8.7% higher on another blowout result. It added approximately US$400 billion in market cap from the move, making it the third largest single-day gain by any stock in history.
Here are the key numbers from the Q2 result:
Revenue up 106% to US$96.2bn vs US$92.2bn ests (4% beat)
Data Center revenue up 117% to US$89.0bn vs US$85.8bn ests (4% beat)
Edge Computing revenue up 27% to US$7.2bn vs US$6.61bn ests (9% beat)
Adjusted gross margin of 75.0% vs 75% ests (in line), up 250bps year on year
Adjusted operating income up 124% to US$64.0bn, with adjusted opex up 54% to US$8.2bn
Adjusted net income up 118% to US$54.0bn and adjusted EPS up 120% to US$2.22 vs US$2.10 ests (6% beat)
Free cash flow of US$21.3bn, with about US$26.0bn returned to shareholders in the quarter and roughly US$99.0bn left on the buyback authorisation
Q3 revenue guidance of US$108.0bn plus or minus 2% vs US$104.2bn ests (4% beat), with adjusted gross margin guided to 74.0% plus or minus 50bps
Good morning!
[8:04 am] ASX 200 futures are up 12 pts (+0.13%). Here's what happened overnight:
Major US benchmarks higher and finished near best levels, though technology was the only one of the 11 S&P 500 sectors to advance
S&P 500 (+0.72%), Nasdaq (+1.57%), Dow (+0.20%), Russell 2000 (+0.28%)
Breadth was weak, with sectors like Discretionary, Healthcare and Staples all down more than 1%, and the Equal-weight S&P 500 down 0.3%
Nvidia's guidance for 70% revenue growth in FY28 reset the AI debate, and blowout Salesforce, CrowdStrike and Okta numbers lifted beaten up software names
Jackson Hole opened with three regional Fed presidents warning on inflation, setting up Kevin Warsh's first keynote as chair on Friday