Why Codan might be the best growth stock on the ASX 200
Codan just overtook WiseTech as the ASX's largest tech stock after another upgrade. Defence demand is doing the heavy lifting.
Source: Shutterstock
Mentioned
KEY POINTS
- First-half NPAT is guided at $160 million or more, up at least 125%, as Communications margins hit around 40% and the FY27 growth target lifts to 30-40%
- Conflict regions will make up about half of first-half Communications revenue, but growth outside those regions is tracking around 20%, pointing to structural defence demand
- Shares have more than doubled year-to-date, making Codan the ASX's largest tech stock above $11 billion as WiseTech, Xero and Life360 sold off
Describing Codan (CDA) as one of the market's "best" growth stocks might sound subjective, but when you lay out all of its earnings upgrades, relative share price outperformance and sector tailwinds, "best" might be the only suitable word to describe where it's at.
Today's first-half FY27 update added to that case, with Codan lifting its FY27 Communications growth target to 30-40% and the shares jumping as much as 21% to a record $63.07.
Codan operates two core business segments: Communications and Metal Detection.
The Communications business focuses on solutions for military, security, public safety and commercial users, with products spanning radio systems, unmanned systems and emerging communication solutions. This segment recorded 22% revenue growth to $506.2 million in FY26, but more interestingly, defence customers now make up 58% of total revenue, up from 38% a year ago.
The Metal Detection segment (Minelab) effectively sells gold and treasure hunting detectors for hobbyists and specialised operations. Revenue in FY26 rose 42%, largely propelled by booming global gold detector demand, especially in African markets.
The year so far
There were three major catalysts for Codan this year, all of which pushed the stock up by double-digit percentages to fresh all-time highs.
First-half FY26 trading update on 9 January, shares up 16.8% to $36.89.
Revenue up 29% to about $394m vs $385m ests (2% beat), well ahead of typical mid-teens growth rates
Underlying NPAT up around 52% to at least $70m vs $67m ests (4% beat)
Metal detection revenue up 46% to $168m, driven by gold detector sales in Africa and double-digit growth across other recreational markets
Communications revenue up 19% to $222m, tracking at the upper end of management's 15% to 20% growth target range
FY26 guidance upgrade on 29 April, shares up 15.4% to $42.00.
FY26 NPAT guidance of ~$170m vs. ests of $152.5m (11% beat)
Communications revenue growth now expected at the top end of the 15-20% target range for FY26, driven by strong defence customer demand for unmanned systems and software-defined radios amid ongoing geopolitical tensions
Communications segment profit margin now expected to reach 30% in FY26, ahead of the prior FY27 target, representing a meaningful step up from the 26% margin delivered in FY25
Minelab revenue in 2H26 to date is tracking ahead of an already strong 1H, supported by a favourable gold price and recent product launches
The FY26 result on 20 August saw the share price rally another 12.4% to a record $48.88.
Revenue up 30% to $875.0m vs $847.7m ests (3% beat)
Communications revenue up 22% to $506.2m vs $496.2m ests (2% beat), above the 15-20% target range, and margin of 31%, hitting the FY27 target 18 months early
Metal Detection revenue up 42% to $362.0m vs $344.0m ests (5% beat), with segment profit up 65% to $162.4m vs $158.2m ests (3% beat)
NPAT up 69% to $175.2m vs $169.4m ests (3% beat), slightly above the guidance provided on 29 April
FY26 fully franked dividend up 70% to 48.5cps
FY27 revenue growth targeted in the order of 20%, implying ~$1,050m against $963.8m ests (9% above)
This then takes us to today's update where the company announced:
Communications 1H27 revenue guided to $400–410m, up 80–85% year-on-year
Conflict regions are expected to make up about 50% of Communications revenue in H1 vs about 20% in the pcp, with growth outside those regions in the order of 20%
Minelab's H1 revenue run-rate is now slightly above 2H26 levels, driven by the new GPZ8000 and Gold Monster 2000 detectors and a favourable gold price
Communications EBIT margin expected in the order of 40% vs 26% in the pcp and 31% in FY26
Group H1 NPAT of at least $160m, up at least 125% year-on-year
FY27 Communications revenue growth target lifted to 30–40% from about 20%
Codan rallied as much as 21% to $63.07, taking its year-to-date gains to 122% (including dividends).
Codan takes the crown
With the stock doubling year-to-date at a time when most of the large-cap Aussie tech basket has sold off (much of it battered software-related plays like WiseTech, Xero and Life360), Codan is now the largest tech stock on the ASX.
It surpassed WiseTech this morning, crossing the $11 billion market cap level, while WiseTech is trading around $10.9 billion.
Where to from here
Chasing such a large gap-up feels rather greedy and leaves you exposed to profit-taking and a potential pullback from overbought levels. Luckily, there's a bit of precedent with how Codan has traded in the prior three 'upgrade and gap-up' setups, all of which experienced 3-10% further upside over the next day to two weeks, although the latest August result saw the stock briefly rally 4% the next day but finish flat and that was about it.
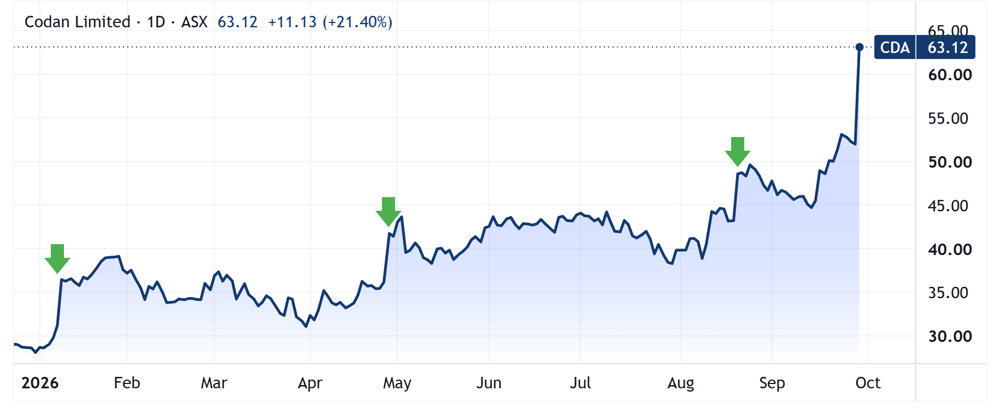
Codan year-to-date price chart, guidance upgrade/earnings marked via green arrow (Source: TradingView)
While the price chart is vertical, there's no denying that Codan's growth narrative just keeps on getting better. Sure, there's an element that's driven by the Russia-Ukraine and US-Iran conflicts, but the company notes that growth outside those regions is in the order of 20%, so in many ways, the demand environment is structural. I guess what to look out for from here is how the stock holds up after such a massive one-day move, since it's now trading around 25% above its 50-day moving average.