UBS says iron ore consensus is too low: What it means for BHP, RIO and FMG
UBS says Simandou is only part of the iron ore story and lifts its long-term price forecast to US$93 a tonne, 12% above consensus.
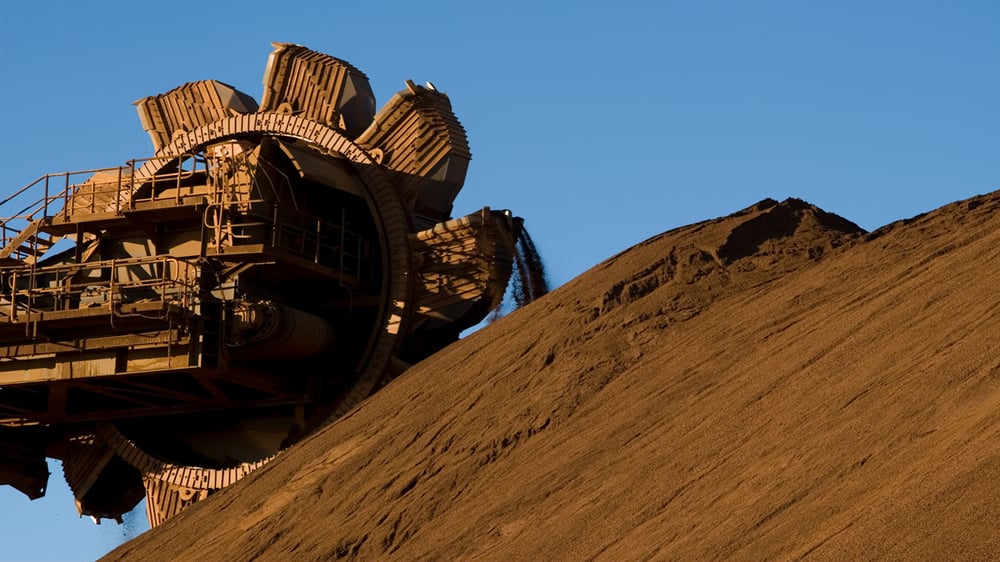
Source: Shutterstock
Mentioned
KEY POINTS
- UBS has lifted its long-term iron ore forecast to US$93 a tonne from US$85, although it expects prices to stay soft while Simandou ramps up.
- The bank says consensus underestimates steel demand from China's manufacturing pivot and the Global South, and overstates supply growth as ore grades fall and mines run out.
- Despite the upgrade, UBS has only slightly lifted its targets for BHP and RIO, cut its targets for FMG and MIN, and started coverage of CIA with a buy rating.
Analysts have been bearish on iron ore for years, and the forecasts keep calling for lower prices. But prices have held up better than most expected, and UBS thinks the consensus view is too narrow.
“We believe consensus underestimates the durability of steel demand outside China, overstates future iron-unit supply growth by focusing on ore tonnes rather than contained iron units, and assumes greater cost curve flexibility than industry data supports,” said UBS in a 29 September note.
Simandou accelerated its annualised run-rate to roughly 30 million tonnes in May. This was well-ahead of some analyst forecasts of only 6 million tonnes for the entirety of 2026, and placed downward pressure on iron ore prices.
But Simandou is only part of the picture. UBS lifted its long-term iron ore forecast to US$93 a tonne from US$85, about 12% above the consensus of US$83.
The upgrade has done little for UBS' price targets on the ASX producers. The bank nudged its targets for BHP (BHP) and Rio Tinto (RIO) slightly higher but cut them for Fortescue (FMG) and Mineral Resources (MIN). This article looks at the three reasons behind the upgrade and how each miner is positioned, including Champion Iron (CIA), which UBS has started covering with a buy rating.
UBS’ three reasons for higher long term iron ore price
UBS says the market is underestimating the forces shaping iron ore over the next decade. It argues demand will hold up better than expected as China pivots to manufacturing and the "Global South" industrialises, while supply will grow more slowly than headline tonnes suggest.
#1 China’s pivot to manufacturing & exports from construction
China produces more than half the world's steel and imports about three-quarters of global seaborne iron ore, according to UBS figures. Construction was the largest source of Chinese steel demand, accounting for as much as 60% at its peak, according to Wood Mackenzie. UBS says falling property and infrastructure activity has driven China's steel demand down about 21% since its 2020 peak, to 796 million tonnes last year.
But Chinese steel production has only fallen about 3% over the same period, which UBS attributes to mills shifting output towards manufacturing and exports. Demand from sectors outside construction overtook construction for the first time this year, according to UBS, and China now exports 130 million to 150 million tonnes of steel a year inside goods such as machinery, cars and ships.
UBS says bearish iron ore forecasts have underestimated this shift, which has kept Chinese mills producing at high rates despite weaker construction. Blast furnaces, which use iron ore, are running near 90% capacity, and UBS says scrap is supplementing iron ore rather than replacing it, concluding that "Chinese iron ore demand is more resilient than domestic property demand would suggest."
#2 Global South drives strong steel demand and offsets China retreat
The second reason UBS gives is the rise of what it calls the “Global South”, a group of 14 developing countries including India, Indonesia, Vietnam, Brazil and Saudi Arabia, with a combined population of about 2.9 billion. UBS says these countries are industrialising and have become a key destination for Chinese steel exports, and forecasts their own steel production to rise from 434 million tonnes last year to 640 million by 2035.
India leads the growth, with UBS forecasting its seaborne iron ore imports to rise from 10 million tonnes last year to 117 million by 2035. UBS says developing countries have little scrap steel to recycle, so their growth relies on blast furnaces, which use iron ore. The analysts say bearish forecasts have underestimated the scale of this demand, which it expects to more than offset China's decline and keep global steel demand growing through 2035.
#3 Grade decline, depletion, muted scrap use and weak capex
The third reason UBS gives is that supply will grow more slowly than headline figures suggest. UBS says consensus is focused on tonnes of ore shipped, but "it is supply and demand of iron units that determines market balance", and the iron content of ore is falling as miners work through their best deposits first. UBS estimates that falling grades mean the market needs about 50 million tonnes more ore this year than earlier forecasts assumed.
Rio Tinto estimates about 800 million tonnes of existing production will need replacing by 2035 as mines run out, and about 650 million tonnes of that is still uncommitted after accounting for Simandou and other committed projects. UBS says replacement mines are further from infrastructure, deeper and more expensive to build, and forecasts industry spending on new supply between 2027 and 2035 to be about 60% below the previous nine years. UBS still expects a surplus, but a modest one, and expects the market to tighten after Simandou reaches full production in 2029.
How ASX iron ore producers will fare
UBS says the higher long-term price lifts valuations across its coverage, but lower realised prices, higher costs and elevated bond yields offset much of the gain.
Here is how UBS rates the five producers:
BHP Group: Neutral, $61 target (up from $59). BHP's Pilbara business has the strongest cost position of the majors, but copper will make up 55% of group earnings in FY27, muting the iron ore benefit.
Rio Tinto: Neutral, $178 target (up from $177). Pilbara Blend and Simandou's high-grade ore protect it from wider discounts on lower-grade ore, but spending on Simandou and replacement Pilbara mines weighs on cash flow.
Fortescue: Neutral, $16.50 target (cut from $18.35). Fortescue has the most to gain from a higher iron ore price as a near pure-play, but its lower-grade ore is most exposed to wider discounts and its capital spending is high.
Mineral Resources: Buy, $74 target (cut from $76). The ramp-up of its Onslow Iron project should lift iron ore volumes and cash flow sharply over the coming years.
Champion Iron: initiated Buy, $4.15 target. Champion's concentrated iron ore exposure makes it highly sensitive to the long-term price, and the higher forecast materially improves its valuation.
The bottom line
The forecast made by UBS rests on factors that are set to play out over the next decade, with the bank still expecting prices to stay soft through to 2029. The forecast assumes Chinese mills keep exporting steel, demand from India and other developing countries grows as expected and miners fail to replace depleting mines as quickly as they run out. The lift in long term price only slightly raises price targets for producers and leaves Mineral Resources and Champion Iron the only Buy ratings among the five producers mentioned above.