Tuas beats FY26 estimates, but shares slump 17% amid regulatory uncertainty
Tuas beat Morgan Stanley expectations on revenue and profit, but gave investors no update on the regulatory breach that sank the M1 deal.
Source: Shutterstock
Mentioned
KEY POINTS
- Revenue rose 24%, underlying EBITDA rose 22% and underlying profit was up more than fourfold, all ahead of Morgan Stanley's estimates.
- Chairman David Teoh offered nothing new on the spectrum investigation, saying only that Tuas is cooperating and awaiting a formal decision. Shares fell 17%.
- Morgan Stanley rated the stock Overweight on 14 September arguing the valuation already prices in a poor regulatory outcome.
Tuas' share price has swung wildly over the past 12 months on developments tied to its now-lapsed $1.59 billion bid for M1 Limited, and today's FY26 result suggest that saga is still driving the stock. Revenue and profit both beat Morgan Stanley's estimates, which helps explain why the stock opened 6.8% higher at $2.49. But the share price went vertically lower from there, down as much as 19% in early trade.
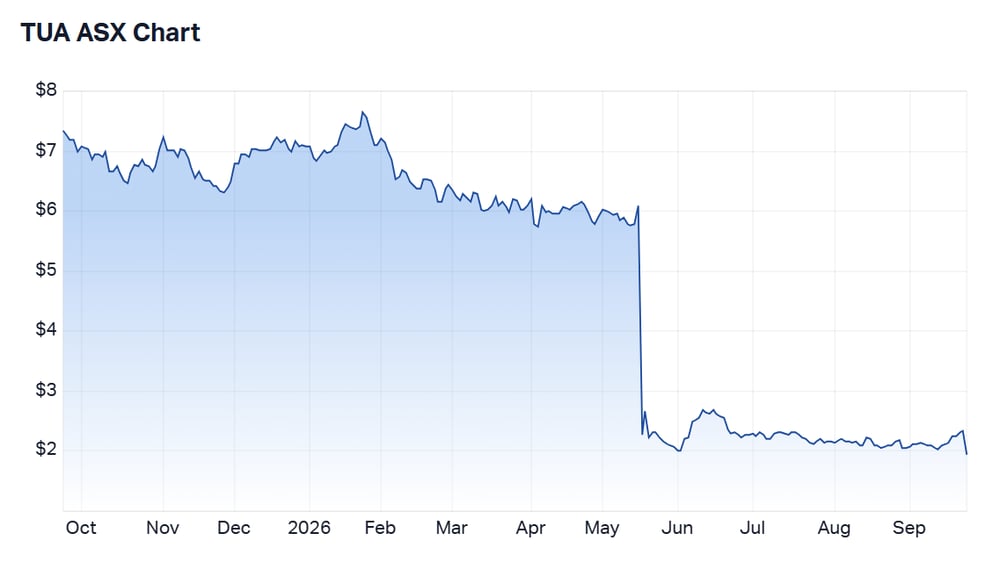
Tuas 12-month price chart (Source: Market Index)
“This financial year brought the significant milestone of entering into an agreement to acquire M1 Limited, the transaction ultimately lapsed as regulatory consent from the Infocomm Media Development Authority (IMDA) was not granted prior to the completion deadline,” said Chairman David Teoh.
“We remain fully cooperative with the IMDA regarding the unauthorised spectrum usage matter and are currently awaiting their formal decision,” added Teoh.
FY26 results in focus
FY26 results, with comparisons to FY25 and Morgan Stanley estimates dated 14 September:
Revenue up 24% to S$187.6 million vs S$185.7 million Morgan Stanley (1% beat), driven by growth in both mobile and fibre broadband subscribers
Underlying EBITDA up 22% to S$83.8 million vs S$83 million Morgan Stanley (1% beat), with the underlying margin steady at 45%
Mobile revenue rose to S$167.5 million from S$144.6 million, with active mobile services up 16% to 1.458m and gross mobile ARPU at S$9.42
Broadband revenue more than tripled to S$19.7 million from S$6.4 million as fibre subscriptions grew to 62,000
Underlying NPAT up 329% to S$29.6 million vs S$22.7 million Morgan Stanley (30% beat)
No dividend declared, extending a run with no distributions dating back to at least FY22
Cash and term deposits rose to S$498.8 million from S$80.7 million, largely reflecting the S$359.8 million capital raising that was conducted at $5.51 per share at a nil discount to last close raised last year to fund the M1 acquisition; the board says it has yet to decide how to deploy the funds
Looking forward, Tuas said its FY27 focus is on growing EBITDA through new product launches in the Singapore market. The company itself has guided to S$15 million to S$30 million in additional capital and operating spend to meet new cybersecurity requirements imposed on critical information infrastructure operators.
M1 deal in focus
Tuas is listed on the ASX but conducts its business through its wholly owned subsidiary, Simba Telecom, in Singapore. Tuas agreed to acquire M1 Limited in August 2025, excluding M1's ICT business, in a deal that would have consolidated Singapore's mobile market from four operators to three.
The deal fell over in May when the IMDA signalled it would suspend its review pending an investigation into unauthorised spectrum use by Simba, and the sale and purchase agreement hit its long-stop date on 21 May without clearance. Shares fell around 63% in a single session on 18 May and have traded largely sideways up until Wednesday’s earnings pushed the stock down 17%.
Earlier this month in a 14 September note, Morgan Stanley kept an Overweight rating and said it would buy on weakness, arguing the stock's roughly 4x FY27 EV/EBITDA is undemanding against a historical average near 34x even if the regulatory outcome disappoints.
Bottom line
Today’s volatile share price reaction continues a pattern for Tuas. When the company reported its first-half FY25 in March last year, Opened around 15.5% higher, dived about 28% to an intraday low, and finished 7.5% lower for the day. Citi said it was “perplexed” by the movement despite a broad beat on revenue, EBITDA and margins. It ultimately put it down to three possible factors: a sell-down by a major shareholder, a Chinese New Year driven slow down in net adds and a step-down in mobile APRU.
Today’s result also broadly beat most metrics against Morgan Stanley’s estimates, but the exception is the company was unable to add clarity on a resolution to a regulation breach that put a stop to its M1 deal. Until it resolves, Tuas is left running a business with strong underlying growth and S$498.8 million (A$550m)cash at the bank. It’s understandable why analysts have remained so bullish on the stock, but it's also worth remembering that the bulk of this cash was raised at $5.51 per share, while the stock trades at sub-$2 today.