ASX 200 Live Today - Wednesday, 17th June
The S&P/ASX 200 is set to slip after a mixed overnight session where tech dipped and defensives outperformed. Here are today's top stories.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Wednesday, June 18. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
ASX 200 higher as Miners return to fresh all-time highs
[2:00 pm] That's a wrap. The ASX 200 is currently up 0.49%, hovering session highs and on-track to record a four-day win streak. A solid session, with only three down sectors and 133 constituents (67%) trading higher. Energy and Utilities (which has large LNG exposure) down 2.2% and 1.6% respectively. Staples experienced a massive defensive rotation earlier this week (seven-day win streak between 3-12 June) and now starting to unwind. Meanwhile, strong gains for Tech (+1.7%), Materials (+1.1%) and Healthcare (+1.1%).
It's been a truly V-shape recovery for the Materials index, which suffered a four-day losing streak (4-10 June), down 8.6% and now, up 9.7% in the last five sessions. Miners are trading broadly higher today, with BHP (+0.7%) recording a third straight all-time high, Gold Miners (+3.4%) now up ~22% in the lats four sessions, Sandfire (+3.0%) at all-time highs, most lithium names up 2-3% and more.
Overall, the ASX is starting to find some momentum amid this resource-led rally, along with the recent outperformance of defensives (Real Estate, Staples and Healthcare) and a bounce for retail-related stocks. The Aussie 10-year is down a further 2 bps today, to a fresh three-month low of 4.77%.
Korean retail piles $800m into SpaceX on debut after IPO shut-out
[1:36 pm] South Korean retail investors bought a net $796m of SpaceX on its first trading day, making it their most popular US stock after being denied IPO access.
One-day net purchase of $796m exceeded the cumulative three-month net buying of any other US equity by Korean retail
SpaceX up 49% since listing, taking market cap to $2.65trn and surpassing Amazon by roughly $8bn
Korean retail were shut out of the IPO, with underwriter Mirae Asset Securities ultimately receiving no shares to allocate
A SpaceX-focused ETF drew net inflows of $301m from Korean retail over the past month
Source: Bloomberg
IFM declares Atlas Arteria offer unconditional, warns $5.10 is best and final
[1:32 pm] IFM has dropped all prescribed occurrences conditions on its bid and reiterated the $5.10 per security offer will not be increased absent a competing proposal, with voting power now at 38.42%.
Offer declared unconditional under section 650F, with IFM's voting power in ALX standing at 38.42%
$5.10 per security is best and final, backed by a truth-in-takeovers statement that IFM will not acquire securities above that price for 12 months absent a competing bid
Offer closes 7.00pm Sydney time on 25 June 2026 and will not be extended unless required by law
IFM argues its bid implies a Chicago Skyway valuation in line with the 2022 acquisition price and above book, with OTPP having recently rejected the ROFO at that level
$5.10 represents a premium to the undisturbed price of $4.33 and one-month VWAP of $4.28 prior to the offer
The funny thing is you can clearly see IFM sitting in the order book, with a ~94 million share buy order at $5.10.
Company page: Atlas Arteria (ALX)
Gold stocks broadly higher
[12:01 pm] The All Ords Gold index is up 3.9% today, and on track to record a four-day win streak, where its gained 22.1%. Despite the massive bounce, the index is still down 4.9% year-to-date.
Ticker | Company | % Chg | Price | YTD % |
|---|---|---|---|---|
SBM | St. Barbara | 7.4% | $0.65 | 13.0% |
PNR | Pantoro Gold | 7.3% | $3.03 | -38.3% |
RSG | Resolute Mining | 7.2% | $1.19 | -3.3% |
AMI | Aurelia Metals | 6.5% | $0.33 | 34.7% |
ALK | Alkane Resources | 6.2% | $1.67 | 25.7% |
EMR | Emerald Resources | 5.8% | $6.35 | 1.1% |
RRL | Regis Resources | 5.2% | $7.04 | -6.4% |
BGL | Bellevue Gold | 5.1% | $1.64 | -3.3% |
GMD | Genesis Minerals | 5.0% | $6.13 | -14.4% |
BC8 | Black Cat Syndicate | 5.0% | $1.10 | -9.3% |
RMS | Ramelius Resources | 4.7% | $3.35 | -18.1% |
WGX | Westgold Resources | 4.4% | $5.40 | -14.4% |
CYL | Catalyst Metals | 4.1% | $6.28 | -15.0% |
VAU | Vault Minerals | 4.0% | $4.90 | -9.9% |
OBM | Ora Banda Mining | 3.8% | $1.37 | -10.5% |
EVN | Evolution Mining | 3.6% | $13.56 | 7.8% |
PRU | Perseus Mining | 3.6% | $5.59 | 1.4% |
NST | Northern Star Resources | 3.1% | $21.97 | -10.5% |
NEM | Newmont | 2.7% | $154.18 | 2.7% |
CMM | Capricorn Metals | 1.9% | $13.66 | -2.4% |
MEK | Meeka Metals | 0.0% | $0.12 | -55.6% |
RBA flags more shock-prone financial system as geopolitics reshape capital flows
[11:58 am] Assistant Governor Brad Jones warned Australia's high foreign ownership of fixed income and offshore super exposure leave the system vulnerable to global fragmentation.
Around half of Australian super fund assets are invested offshore, leaving the financial system exposed to foreign shocks
FDI is increasingly flowing between geopolitically aligned countries, with the opposite dynamic playing out between geopolitically distant ones
US-China capital flows have "slowed to a crawl", with China's balance sheet pointing to recent outflows from the US in favour of emerging market exposures
USD still used in 90% of FX transactions and dominates reserve portfolios, with the renminbi's share of global reserves edging down to just 2%
More than 120 countries were subject to financial sanctions as of 2023, double a decade earlier, with financial sanctions now 42% of all sanctions versus 12% in the 1950s
Source: Bloomberg
Energy stocks at fresh three-month lows
[11:46 am] The S&P/ASX 200 Energy index is currently down 2.7%, trading fractionally above the key 200-day moving average. It's now down 7.2% in the last two sessions but still up 17.2% for the year.
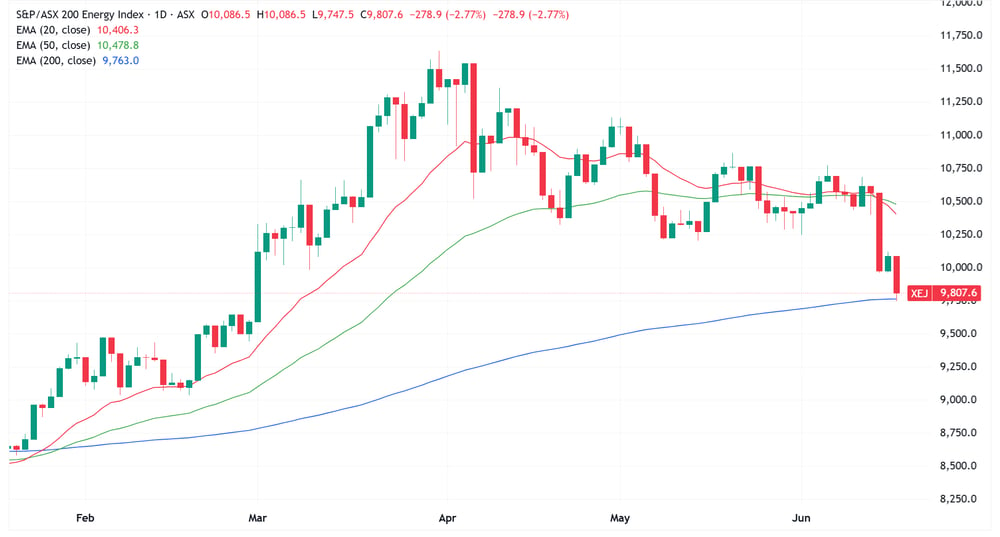
S&P/ASX 200 Energy Index daily chart (Source: TradingView)
Ticker | Company | % Chg | Price | YTD % |
|---|---|---|---|---|
KAR | Karoon Energy | -12.5% | $1.44 | -28.0% |
STX | Strike Energy | -4.5% | $0.11 | -36.4% |
WDS | Woodside Energy Group | -4.0% | $28.84 | 12.2% |
YAL | Yancoal Australia | -3.0% | $5.90 | -0.6% |
BPT | Beach Energy | -2.7% | $0.99 | -26.0% |
WHC | Whitehaven Coal | -2.6% | $8.33 | 43.3% |
STO | Santos | -2.2% | $7.29 | -6.0% |
NHC | New Hope Corporation | -1.9% | $5.49 | 38.5% |
BRK | Brookside Energy | -1.2% | $0.42 | -4.6% |
VEA | Viva Energy Group | -1.2% | $2.13 | 5.2% |
ALD | Ampol | -1.0% | $33.57 | 30.7% |
Banks on a four-day win streak
[11:42 am] The S&P/ASX 200 Financials Index is up 0.39% on Wednesday, and up 3.7% in the last four sessions, lifting year-to-date performance back to breakeven.
Ticker | Company | % Chg | Price | YTD % |
|---|---|---|---|---|
JDO | Judo Capital | 1.1% | $1.52 | -2.8% |
CBA | Commonwealth Bank | 1.0% | $163.56 | -8.6% |
ANZ | ANZ Group | 0.5% | $34.98 | 18.4% |
NAB | National Australia Bank | 0.4% | $38.05 | -1.8% |
MQG | Macquarie Group | 0.4% | $249.96 | 17.4% |
WBC | Westpac | 0.3% | $35.85 | 8.4% |
BOQ | Bank Of Queensland | 0.1% | $6.37 | -19.8% |
BEN | Bendigo & Adelaide Bank | 0.0% | $10.70 | -15.7% |
Macquarie reads RBA as hawkish hold, pushes back on market pricing for cuts
[11:17 am] Macquarie's tone analyser scored Tuesday's RBA decision and press conference at +46.1, firmly hawkish, with the analysts reading the Bank as pausing to assess transmission rather than signalling peak rates and pushing back against market pricing for cuts.
Strongest hawkish vectors were inflation (+97.5), forward guidance (+83.3), policy reaction function (+76.5) and risk (+72.0), with the statement calling headline and underlying inflation "still too high" and flagging higher fuel pass-through
Bullock said the Board did not consider hiking but also did not endorse rates having peaked, noting unemployment at 4.5% was not alarming and labour remains "a bit tight"
Press conference softened external and financial-conditions hawkishness, with Bullock saying Middle East de-escalation and a Hormuz reopening would help commodity flows and prices, but inflation pre-dated the conflict and second-round effects are emerging
Macquarie sees the RBA as no longer a local hawkish outlier, with the ECB and Denmark each hiking 25bp and Japan lifting to 1.0%, taking the developed-world tightening group to 5 of 11 with markets pricing hikes across 9 of 11
Global tightening backdrop seen constraining any near-term RBA cut, keeping the bias towards higher-for-longer beneficiaries and defensive income
REITs, duration growth and domestic rate-cut beneficiaries flagged as vulnerable if final-hike risk stays alive
Macquarie says El Niño now priced as winners and losers basket finalised
[11:16 am] Macquarie has updated its El Niño thematic baskets after Bureau of Meteorology declared the event underway on 16 June, following NOAA's call on 11 June, with both flagging the risk of one of the strongest El Niño events since 1950.
Two of three Macquarie nowcast triggers confirmed (surface temperature and atmosphere), with IOD still negative but expected to improve through winter-spring
Winners basket combining El Niño beneficiaries with momentum: MIN, NHC, NRW, RIO, where dry weather lifts uptime or reduces disruption across mining, mining services, contractors and building materials
Losers basket combining negative exposure with momentum: ELD, ORG, NAB, covering crop and rural services, food, grain, wine and agri-exposed credit
Insurance has been a common underperformer in El Niño events since 2000
Flight Centre surges despite earnings downgrade
[11:14 am] Flight Centre opened 3.9% lower and V-shaped its way into positive territory, now up 4.1%. The company's trading update had something for both bulls and bears, and so did the early price action.
The downgraded FY26 UPBT guidance to $275-295 million from $310-345 million on Middle East war disruption to leisure travel, while announcing an up-to-$200 million on-market buyback reflecting confidence in the recovery.
Bulls: Underlying business actually grew underlying profit before tax by 10% in the first three quarters of FY26, accelerating to ~20% in Q3 before the Q4 disruption, corporate business less affected, new on-market $200m buyback and expectations for strong FY27 recovery on Middle East peace deal
Bears: FY26 earnings downgrade, both materially below prior guidance and consensus, notable hit to leisure segment amid cancellations, re-routes and deferred bookings
The stock's high short interest (~10.98%) may also be contributing to this morning's volatility.
Symal acquires defence and resources contractor Shamrock Civil for up to $79m
[10:15 am] Symal has entered a conditional agreement to acquire 100% of Queensland-based defence and resources contractor Shamrock Civil, materially lifting its defence exposure and extending its national footprint into the Northern Territory.
Upfront payment of $51.0m ($40.8m cash, $10.2m SYL scrip), plus performance-based FY26/FY27 earn-outs capped at $28.4m
Shamrock forecast to deliver FY26 underlying EBITDA of ~$16m on annual revenue of ~$220m, with the deal expected to be EPS accretive in the first full year
Over 70% of Shamrock's work-in-hand and tendered pipeline is defence-related, with the national defence budget set to rise from $54bn to $68bn annually within five years and a near-term pipeline including ~$900m of AUKUS civil packages, ~$700m RAAF Townsville upgrade and ~$1bn Hervey Range facility
Symal shares are up 12.5% in early trade, but still down 13% year-to-date. A very solid deal by the looks of it, acquiring Shamrock at a 3.2x FY26 EBITDA multiple. Symal is guiding to $123-126 million for FY26, so Shamrock earnings are forecast to be low-teens EPS accretive.
Company page: Symal Group (SYL)
Top All Ords gainers and losers
[10:11 am] Symal surged on a acquisition and Karoon continues to tumble after yesterday's production downgrade.
Ticker | Company | % Chg | Price |
|---|---|---|---|
SYL | Symal Group | 14.81% | $3.10 |
DTR | Dateline Resources | 10.00% | $0.17 |
CBE | Cobre | 7.81% | $0.35 |
AS1 | Asara Resources | 7.41% | $0.15 |
SKC | Skycity Entertainment Group | 6.82% | $0.47 |
MM8 | Medallion Metal | 6.59% | $0.49 |
A1M | Aic Mines | 5.84% | $0.73 |
AUC | Ausgold | 5.06% | $0.94 |
UNI | Universal Store | 4.68% | $7.38 |
SGM | Sims | 4.59% | $30.79 |
Ticker | Company | % Chg | Price |
|---|---|---|---|
KAR | Karoon Energy | -9.12% | $1.50 |
AFP | Aft Pharmaceuticals | -5.54% | $3.07 |
ASG | Autosports Group | -4.99% | $1.81 |
SGQ | St. George Mining | -4.55% | $0.11 |
STX | Strike Energy | -4.55% | $0.11 |
MEK | Meeka Metals | -4.17% | $0.12 |
360 | Life360 | -4.10% | $22.11 |
AYA | Artrya | -3.87% | $4.47 |
NHC | New Hope Corporation | -3.85% | $5.38 |
PEB | Pacific Edge | -3.85% | $0.25 |
Top ASX 200 gainers and losers
[10:07 am] Sims rallies on an FY26 earnings guidance upgrade, gold stocks open broadly higher, while coal and refiners extend declines.
Ticker | Company | % Chg | Price |
|---|---|---|---|
SGM | Sims | 5.33% | $31.01 |
EOS | Electro Optic Systems | 3.89% | $9.08 |
RRL | Regis Resources | 3.44% | $6.92 |
RSG | Resolute Mining | 3.17% | $1.14 |
VAU | Vault Minerals | 2.97% | $4.85 |
ALK | Alkane Resources | 2.86% | $1.62 |
EMR | Emerald Resources | 2.83% | $6.17 |
FLT | Flight Centre Travel Group | 2.79% | $12.14 |
PRU | Perseus Mining | 2.50% | $5.53 |
DRO | Droneshield | 2.43% | $2.95 |
Ticker | Company | % Chg | Price |
|---|---|---|---|
NHC | New Hope | -4.11% | $5.36 |
360 | Life360 | -3.86% | $22.16 |
GYG | Guzman Y Gomez | -2.85% | $18.76 |
WHC | Whitehaven Coal | -2.81% | $8.31 |
ALD | Ampol | -2.80% | $32.97 |
SEK | Seek | -2.63% | $13.35 |
CEN | Contact Energy | -2.59% | $7.71 |
GMG | Goodman Group | -2.48% | $31.46 |
ELV | Elevra Lithium | -2.44% | $12.78 |
PMV | Premier Investments | -2.34% | $13.79 |
Flight Centre cuts FY26 UPBT guidance on Middle East disruption, launches $200m buyback
[9:52 am] Flight Centre has downgraded FY26 UPBT guidance to $275-295 million from $310-345 million on Middle East war disruption to leisure travel, while announcing an up-to-$200 million on-market buyback reflecting confidence in the recovery.
FY26 UPBT now expected at $275-295m vs $307.7m ests (7% miss at midpoint)
Q4 leisure earnings to be circa $50m below prior expectations, with a further $5m hit to UK touring businesses and $5m-10m of adverse FX from a stronger AUD
Underlying business grew UPBT almost 10% to $227m in the first three quarters of FY26, accelerating to ~20% growth in Q3, with leisure tracking towards a $200m UPBT milestone before the Q4 disruption
Corporate business less affected and on track to deliver strong FY26 profit growth, supported by the new Blockskye US partnership and an accelerating contract win pipeline
Q4 leisure hit driven by cancellations and reroutes on UK/Europe bookings via the Middle East, plus deferred long-haul bookings as airfares spiked; Flight Centre brand Australia enquiry still up 18% month-to-date
New up-to-$200m on-market buyback follows May 2026's program that retired 16.2m shares (7.3% of issued capital), with the Middle East peace deal seen as a significant FY27 earnings tailwind
Short interest in the stock has remained elevated over the past ~9 months.
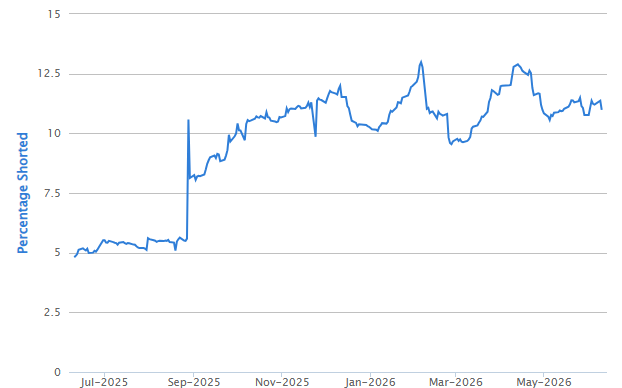
Source: Shortman
While Flight Centre shares have bounced 22% since 20 May, the stock is still down 21% year-to-date.
Overall, a material downgrade relative to prior expectations as well as consensus (which was already below the prior guidance range). Though high short interest, the $200 million buyback and share price softness may drive some intraday volatility.
Company page: Flight Centre (FLT)
Sims upgrades FY26 EBIT guidance on stronger metals and data centre demand
[9:19 am] Sims has lifted FY26 Underlying EBIT guidance to $420-435 million from $350-400 million, with North American metals leading the upgrade and Sims Lifecycle Services continuing to benefit from data centre tailwinds.
FY26 Underlying EBIT now expected at $420-435m vs prior $350-400m guidance (17% upgrade at midpoint)
North American Metal businesses (NAM and SA Recycling) expected to deliver a significant increase in 2H earnings, driven by continued non-ferrous strength and improved ferrous conditions
ANZ ferrous market conditions remain subdued due to ongoing elevated Chinese steel exports, despite recent improvement in Asian ferrous prices
Sims Lifecycle Services FY26 Underlying EBIT now expected at $170-175m, benefiting from structural growth in the global data centre ecosystem
A very material earnings upgrade, well-above prior guidance and $354 million consensus (May-26). However, the stock has ripped 63.7% year-to-date, with some analysts concerned about the durability of Lifecycle Services earnings.
Company page: Sims (SGM)
Analysts slash Karoon Energy target
[9:04 am] Karoon tumbled 11.5% on Tuesday after downgrading its FY26 production guidance.
Macquarie downgraded the stock to Underperform from Neutral and cut its target price from $2.00 from $1.50, while Morgans cut its target from $1.90 to $1.67.
Yesterday's update featured:
Operator LLOG advised E manifold production now expected to be restored in 2H27, with removal of the failed riser planned for Q3
CY26 total production guidance cut 11% to 7.2-8.2 MMboe from prior 8.1-9.2 MMboe (midpoint down to 7.7 from 8.65)
Who Dat CY26 production guidance cut 41% to 1.2-1.5 (NRI) MMboe from prior 2.1-2.5 (NRI) MMboe (midpoint down to 1.35 from 2.3)
Brazil production guidance unchanged
Remediation plan being developed to restore the deferred production
ARN Media settles Sandilands proceedings for $12 million
[9:02 am] ARN Media has reached a binding settlement with Kyle Sandilands to resolve all outstanding legal proceedings, with Sandilands no longer providing services to ARN and intending to pursue independent media opportunities.
Cash settlement sum of $12.09m, with $3m payable in July 2026 and the balance paid monthly until June 2029
ARN to provide $1.5m of advertising services on partner platforms over three years
Net revenue share arrangement giving ARN a 19.9% contribution from Sandilands' new venture for up to three years, subject to agreed thresholds and caps
Restraints prevent Sandilands engaging with ARN's direct competitors for up to nine months, expiring March 2027
Legal proceedings with Jacqueline Henderson remain ongoing
Company page: ARN Media (A1N)
Fletcher Building guides FY EBIT to NZ$375-380m, ahead of consensus
[9:01 am] Fletcher Building has flagged FY EBIT of NZ$375-380 million ex-items, well above consensus, while withdrawing its Moody's credit rating after a material reduction in net debt from divestments.
FY26 EBIT ex-items of NZ$375-380m vs $346.2m ests (9% beat at midpoint)
Net debt forecast to be marginally above the middle of the NZ$400-900m target range at 30 June 2026 following the Construction divestment settlement and property sales
Existing construction projects continue to progress, supporting ongoing materials demand
Rising fuel costs and broader cost inflation driving delays and some cancellations of new projects, particularly in commercial
If sustained, the trend is likely to weigh on group performance in 1H FY27
Company page: Fletcher Building (FBU)
SpaceX confirms $60bn all-stock acquisition of Cursor maker Anysphere
[8:59 am] SpaceX is exercising the option it secured in April to acquire AI coding company Anysphere for US$60 billion in stock, with the deal expected to close in Q3 pending regulatory approvals.
All-stock transaction follows April option that gave SpaceX the right to either pay ~$10bn for a partnership or acquire Cursor for $60bn later in the year
Cursor has scaled to ~$2.6bn in annualised revenue with rising enterprise sales, after being in talks to raise at a ~$50bn valuation in April
Brent tumbles below US$80
[8:53 am] Brent settled 4.8% lower overnight to US$79.33 a barrel, now down 16.5% in the last four sessions.
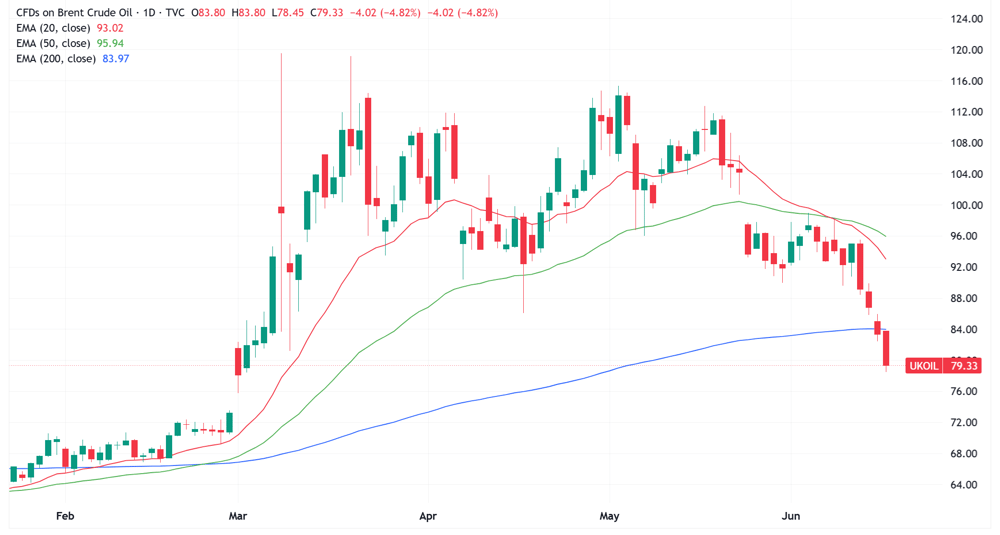
Brent daily price chart (Source: TradingView)
Goldman, Morgan Stanley cut oil forecasts on Hormuz reopening
[8:47 am] Both banks lowered their Brent forecasts after the US-Iran interim deal, with Goldman expecting Persian Gulf exports to normalise to pre-war levels by end-July and Morgan Stanley pencilling in a more gradual recovery into 2027.
Goldman cut Q4 Brent forecast to US$80 a barrel from US$90, assuming Persian Gulf exports normalise to pre-war levels by end of July
Morgan Stanley cut Dated Brent forecasts to US$90 in Q3 from US$100, and to US$80 in Q4
Morgan Stanley sees 50% of lost production back by September, 80% by December, with the rest following in early 2027
Tanker flows likely to take several weeks to restore as mines are cleared, insurer and shipowner confidence rebuilds, and relocated vessels return
Oil prices have slumped to the lowest since early March on the deal, with formal signing expected in Switzerland on Friday
Source: Bloomberg
Qatar plans rapid LNG restart with 80% capacity targeted within two months
[8:44 am] QatarEnergy has told buyers it can restore most of its LNG export capacity within two months of the Strait of Hormuz reopening, faster than analysts had expected, though full restoration will take years following Iranian missile damage in March.
QatarEnergy targeting 50% of capacity a month after safe passage is restored, scaling to roughly 80% within two months
Remaining capacity equivalent to two production trains will take years to fully restore following March missile strikes
Ras Laffan, which exported almost a fifth of global LNG supply last year, has been largely idle for more than three months, with Qatar laying groundwork for restart since April
Kayrros satellite data shows Train 3 back online as of Sunday, likely a "rotate and test" pattern rather than a full restart, with partial activity also seen at ADNOC's UAE plant
European and Asian LNG prices remain above pre-war levels despite the tentative US-Iran deal, with Qatar's return set to ease the global supply crunch
Source: Bloomeberg
Hormuz reopening no quick fix as analysts flag months-long return to normal
[8:42 am] Analysts warn the US-Iran deal will ease supply risks but rebuilding shipowner, insurer and refiner confidence will take time, with many buyers already locked into alternative routes and suppliers.
Karobaar Capital says reopening is a process not a switch, with buyers having spent months securing alternative routes, suppliers and inventories and unlikely to return to the strait immediately
Saxo Markets flags mine-clearing, insurance costs, port congestion and geopolitical spoilers as risks to barrels moving as quickly as headlines suggest
IG Australia sees limited downside for crude near term as nations replenish depleted stockpiles and refill strategic petroleum reserves, with prices already down sharply on deal anticipation
Oil Brokerage notes no big shipowners have changed stance yet, with Japanese, Korean and Chinese owners less risk-tolerant than Greek counterparts and most still seeking clarity on the agreement's terms
Pepperstone flags the deal as on shaky ground given Iran's demands around reconstruction, US capital and frozen funds
Societe Generale notes prices have reacted far less aggressively than historical precedent for a supply disruption of this scale, with the path higher dependent on the timing of any reopening
Source: Bloomberg
US companies rush $40bn of debt as Iran deal opens credit window
[8:41 am] US borrowers led by Nvidia and Qnity Electronics looked to raise more than $40 billion on Tuesday, capitalising on the rally across oil, equities and short-term Treasuries after the US-Iran Hormuz agreement.
Nvidia set to be the biggest investment-grade issuer in its first high-grade bond offering since 2021, with Qnity bringing one of the largest leveraged loan offerings as high-yield prices rose
High-grade funds have now recorded 13 consecutive months of inflows, with credit spreads near historical lows and yield-seeking demand intact through months of war
Acquisition financing also active, including a $2.5bn leveraged loan led by Santander to fund LS Power's $5bn purchase of Constellation Energy generation assets, and a $2.75bn loan backing Stonepeak's majority stake in BP's Castrol
BofA expects further spread tightening in US investment-grade as the war winds down, with lower oil prices supporting cyclicals and easing inflation concerns
Source: Bloomberg
Iran deal the easy part as equities still face Warsh, AI politics and record supply
[8:38 am] Bloomberg argues pricing out the Middle East war was the simple bit, with positioning driven by short covers rather than conviction, and a hawkish new Fed chair, the Fable export ban and the biggest IPO wave in history still to navigate.
US and Iran due to sign interim peace agreement on 19 June, with Brent crude having reversed roughly 80% of its post-war jump, though Strait of Hormuz reopening and Israel/Lebanon role still unresolved
Goldman Sachs prime book saw short covering outpace long buying by 4.7 to one last week, with hedge funds buying US equity risk for four straight weeks to cut beta shorts rather than add alpha
Kevin Warsh chairs his first FOMC on 17-18 June against sticky inflation and rising bets the Fed will need to hike by December, having flagged a "regime change" in communication
Commerce Department's order for Anthropic to block foreign access to Claude Fable 5 and Mythos 5 marks the first time Washington has restricted AI models themselves rather than training chips, politicising the AI trade
JPMorgan sees net equity issuance rising at its fastest pace since at least 1999, making the market's ability to absorb supply the key test over coming months
Source: Bloomberg
SpaceX extends gains, fades best levels
[8:36 am] SpaceX briefly rallied as much as 17.2% overnight, briefly overtook Amazon (US$2.6tn) and Microsoft (US$2.9tn) but finished the session 4.8% higher, with a market cap of US$2.6 trillion.
The stock has now gained 49% from the $135 IPO price.
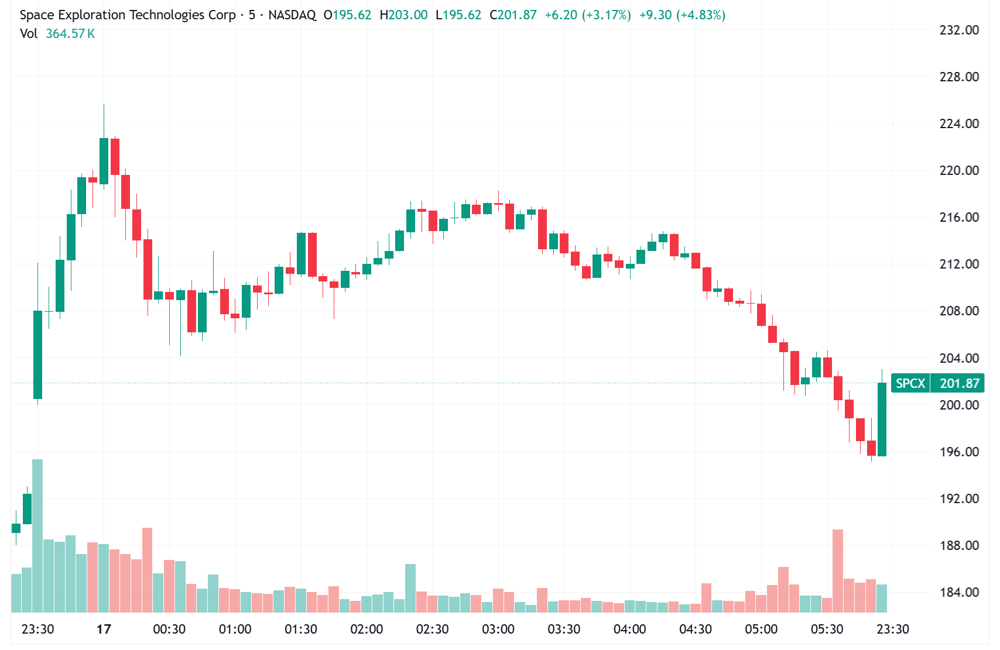
SpaceX intraday chart (Source: TradingView)
US equities mostly lower as profit-taking hits semis after three-day run
[8:33 am] The S&P 500, Nasdaq and Russell 2000 gave back some of Monday's rally as the semis cooled after a near-16% three-day surge, though the Dow eked out a fresh record close on rotation into financials and industrials.
Dow +0.64% closed at record highs, S&P 500 -0.57%, Nasdaq -1.15%, Russell 2000 -0.87%
Semis, memory and software among biggest drags after the SOX's near-16% three-day run, with profit-taking the likely motive and no specific catalyst
Mag 7 mostly lower, other laggards included energy, pharma/biotech, chemicals, retail-investor favourites and China tech
Outperformers were large-cap banks, investment banks, insurers, private equity, payments, machinery, multis, building products, hospitals, apparel and homebuilders
SpaceX briefly overtook Microsoft and Amazon by market cap following its record-breaking IPO, with positive investor sentiment bolstering the stock
Anthropic still working with US officials to resolve the Fable export ban, raising concerns of a shifting AI approach within the Trump administration
Good morning!
[8:24 am] ASX 200 futures are down 25 pts (-0.28%)
The overnight session in a nutshell:
Dow notched a record close while the Nasdaq fell and the S&P 500 slipped, as investors rotated out of chipmakers into cyclicals
Brent crude broke below US$80 for the first time since March as the US-Iran deal points to a Strait of Hormuz reopening, prompting Goldman, Morgan Stanley and Citi to slash forecasts
SpaceX higher (+4.8%) but faded from session highs of +17.2%, briefly overtook Microsoft on a ~US$2.9tn cap, and unveiled a US$60bn all-stock deal to buy Cursor-maker Anysphere