ASX 200 Live Today - Tuesday, 15th September
The ASX 200 continues its downward spiral as banks and miners tumble. Here are today's top stories.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Tuesday, September 15. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
Yields at 15-year highs as banks and miners drag the ASX 200 lower
[2:19 pm] That's a wrap! The ASX 200 is down 75 points (-0.87%) and trading around session lows. It's never a good sign when the banks and the miners are both off more than 1% at the same time.
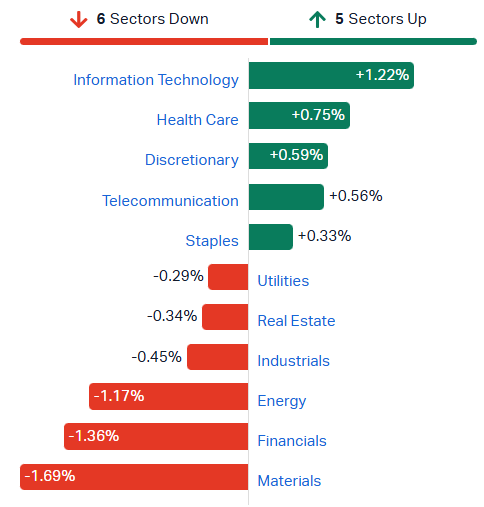
S&P/ASX 200 sectors (Source: Market Index)
Overall, the market narrative remains pretty much unchanged.
Aussie 10-year rose 4 bps to 5.40%, the highest since May 2011
Aussie 3-year yield up 3 bps to 5.0%, also the highest since May 2011
Brent up 0.6% to US$107.20 a barrel
As Macquarie noted on 14 Sep, Australia still has the largest inflation problem. Core inflation of 3.6% is the highest in the developed world
The most useful research I've seen in the past few days comes from UBS strategist Richard Schellbach, who mapped which parts of the market are actually exposed to all of this.
Most ASX sectors are negatively correlated with short-end rate moves on weekly data over the past three years, with equities selling off as yields rise and rallying as they fall
Energy is the only sector showing a visible positive correlation to higher policy rates
Real Estate and Consumer Discretionary screen as most exposed, underlining the vulnerability of the housing and consumer complex to RBA hike sentiment
Stockland, Mirvac, Wesfarmers, JB Hi-Fi and Seek are the top-100 names UBS identifies as most pressured by the prospect or reality of rate increases
Nickel Industries halts plant ramp-up on Indonesian drought
[1:34 pm] An El Niño-driven water shortage in Sulawesi has forced Nickel Industries to pause the ramp-up of its Excelsior Nickel Cobalt facility, with broader implications for Indonesian supply.
Excelsior Nickel Cobalt to run at 30% of nameplate capacity while water supply constraints persist, with the company's other plants unaffected to date
Just under 4mm of rain fell at the Hengjaya mine last month against a historical average of 222mm, illustrating the severity of the drought near the IMIP complex
IMIP flagged output cuts of 30% to 40% earlier this month if new water sources are not found, affecting the park where most of the group's operations sit
Producers also face high sulphur costs, a key reagent for high-pressure acid leaching plants such as Excelsior
Indonesia accounts for roughly 60% of global nickel supply, so a prolonged drought carries read-through well beyond a single operation
Company page: Nickel Industries (NIC) | Source: Bloomberg
Hancock takes 13.5% of White Cliff Minerals as early rally unwinds
[1:33 pm] Gina Rinehart's Hancock Prospecting agreed to a $8.8 million placement in the ASX-listed explorer this morning, though the share price spike on the announcement has been fully retraced.
Shares opened 23.5% higher at 2.1 cents before fading back to 1.7 cents, leaving anyone who bought the open down 19% and the stock flat on the day
Volume of 184m shares traded against a 20-day average of 18.7m, close to ten times the recent run rate
HPPL will invest $8,768,457 for 515,791,601 new shares at $0.017, struck at the previous day's close and subject to shareholder approval at an upcoming general meeting
White Cliff is a junior explorer whose flagship Rae Copper Project in Nunavut, Canada hosts vein-hosted copper at Danvers plus a sediment-hosted system across a roughly 6.3km² footprint
Maiden Danvers drilling returned 175m at 2.5% Cu and 8.66g/t Ag, 90m at 4% Cu and 58m at 3.08% Cu, with step-outs at Danvers 3 returning 20m at 6.64% Cu
Funds go toward expanded drilling, including resource definition at Danvers 1, step-outs at Danvers 2 and 3, and follow-up at regional targets Thor, Rocket, Vision and Stark
Company page: White Cliff Minerals (WCN)
ASX 200 slides as banks and resources fall more than 1%
[12:35 pm] The ASX 200 is down 78 pts (-0.90%) and trading at intraday lows. Most sectors have given back early gains, while the heavyweight Materials and Financials sectors have continued to push session lows.
The index has tumbled 6.5% since the 6 August record high, and down 3.7% in the last six sessions. At an RSI of just 26, the market is now at its most oversold level since late November (when the index fell around 7.5% between 22-Oct and 21-Nov).
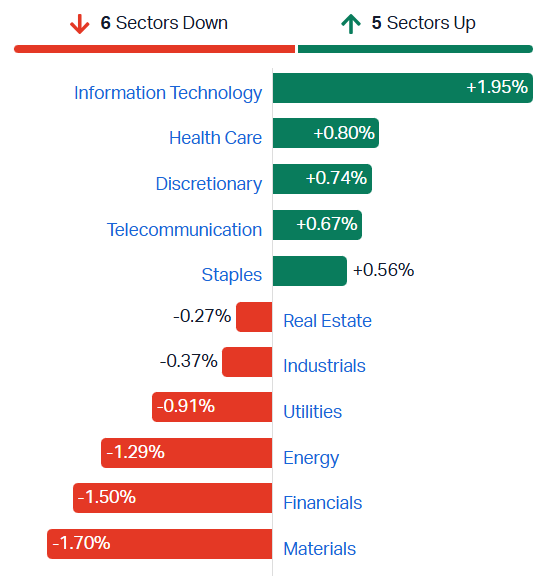
S&P/ASX 200 sectors (Source: Market Index)
Every stock in the top ten is trading lower, except for CSL.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
BHP | BHP Group | -2.2% | $59.27 | -6.0% | 30.2% |
CBA | Commonwealth Bank | -2.1% | $151.68 | -5.8% | -5.6% |
RIO | Rio Tinto | -2.3% | $164.37 | -7.2% | 12.0% |
NAB | NAB | -1.9% | $38.00 | -3.2% | -10.1% |
WBC | Westpac | -1.2% | $34.11 | -2.7% | -11.4% |
ANZ | ANZ | -1.7% | $36.90 | -2.6% | 1.2% |
MQG | Macquarie Group | -2.0% | $240.18 | -3.5% | 18.3% |
WES | Wesfarmers | -0.1% | $72.53 | -6.1% | -10.5% |
CSL | CSL | 0.4% | $172.18 | 0.1% | -0.8% |
WDS | Woodside Energy Group | -1.6% | $32.57 | 1.3% | 37.2% |
Chinese consumption stays weak as industrial output beats
[12:32 pm] August activity data showed factory output accelerating on export strength while retail sales and investment deteriorated further, adding to the case for more stimulus .
Retail sales up 0.4% year-on-year vs 0.8% ests, easing from 0.6% in July, with auto sales down 18.5% the biggest drag and ex-car retail sales holding at 2.5%
Industrial output up 5.2% in August, ahead of expectations and accelerating from July's 4.5% gain, supported by double-digit export growth tied to global AI electronics demand
Fixed-asset investment down 7.2% in the first eight months, slightly worse than expected, with property investment slumping 19.9% as the pre-sale model overhaul weighs on developers
Urban jobless rate rose to 5.3% from 5.2% in July, an unexpected increase that adds to the soft domestic demand picture
Growth risks undershooting the 4.5% to 5% target for a second straight quarter, with Beijing only starting to dial up fiscal spending after months of deep contraction
ANZ's Raymond Yeung said factory activity is holding up thanks toexports, but investment is falling faster and retail sales remain persistently weak, leaving momentum clearly uneven
Source: Bloomberg
China new home prices extend declines in August
[12:30 pm] New home prices fell again in August, though the annual pace of decline was the slowest so far this year.
New home prices down 0.1% month-on-month in August, matching the declines recorded in both July and June
Prices down 3.0% year-on-year, narrowing from a 3.2% fall in July and marking the slowest annual pace of decline this year
The data underscores the persistent drag from China's prolonged property downturn, with no sign yet of a turn in month-on-month momentum
Source: Reuters
A strong day for tech stocks
[12:28 pm] The S&P/ASX 200 Tech Index is up 1.88% and hovering around session highs, clawing back some ground after a brutal stretch that saw it tumble 17.5% between 26 August and 14 September, rising in only two of those fourteen sessions.
The bounce follows a historic overnight split in the US tech trade, where the iShares Expanded Tech-Software ETF rallied 5.0% while semis fell 5.8%, the best day software has ever had relative to semis over 25 years of data. Perhaps we've got a bit of a rotation on our hands?
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
360 | Life360 | 6.6% | $20.83 | 3.7% | -35.4% |
ZIP | Zip Co | 4.8% | $2.20 | -7.6% | -32.7% |
CAT | Catapult Sports | 4.7% | $3.04 | -4.9% | -27.0% |
BVS | Bravura Solutions | 4.4% | $3.18 | 1.8% | 23.5% |
WTC | Wisetech Global | 4.1% | $33.77 | -6.8% | -50.7% |
XRO | Xero | 2.8% | $69.55 | -8.4% | -38.9% |
MP1 | Megaport | 2.8% | $16.81 | -1.3% | 48.1% |
CDA | Codan | 2.3% | $45.73 | -0.6% | 60.9% |
SDR | Siteminder | 1.9% | $2.74 | -5.2% | -55.3% |
TNE | Technology One | 1.6% | $28.72 | -3.6% | 4.2% |
OCL | Objective Corporation | 1.4% | $6.04 | -5.4% | -63.5% |
HSN | Hansen Technologies | 1.4% | $3.36 | -0.4% | -36.5% |
PPS | Praemium | 0.9% | $0.59 | -4.1% | -26.4% |
AD8 | Audinate Group | 0.8% | $2.40 | -3.6% | -40.9% |
DDR | Dicker Data | 0.6% | $14.42 | -2.0% | 40.1% |
PME | Pro Medicus | 0.6% | $166.31 | -2.1% | -24.6% |
MAQ | Macquarie Technology Group | 0.2% | $51.84 | -6.8% | -22.6% |
IRE | Iress | 0.2% | $5.66 | 0.2% | -32.5% |
DTL | Data#3 | 0.1% | $10.57 | -3.0% | 17.8% |
DGT | Digico Infrastructure Reit | -1.4% | $2.55 | -6.4% | -8.8% |
IFT | Infratil | -2.6% | $10.99 | -8.4% | 14.7% |
NXT | NextDC | -2.8% | $11.38 | -10.3% | -7.6% |
Top ASX 200 gainers
[11:07 am] Telix continues to rally after yesterday's FDA approval announcement for Pixclara, the first FET-PET imaging agent cleared in the US for brain cancer. Meanwhile, a long list of beaten up software stocks catch a bid after a strong overnight lead for the broader sector.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
TLX | Telix Pharmaceuticals | 10.8% | $18.11 | 12.1% | 61.0% |
360 | Life360 | 7.3% | $20.97 | 4.4% | -34.9% |
WTC | Wisetech Global | 4.6% | $33.94 | -6.3% | -50.4% |
ZIP | Zip Co | 4.3% | $2.19 | -8.0% | -33.0% |
4DX | 4Dmedical | 3.9% | $3.58 | 4.2% | -10.6% |
NWS | News Corp | 3.7% | $47.43 | 0.9% | 6.6% |
SEK | Seek | 3.6% | $12.80 | -6.9% | -45.0% |
CAR | CAR Group | 3.6% | $24.55 | -5.4% | -20.2% |
XRO | Xero | 3.3% | $69.86 | -8.0% | -38.7% |
NHC | New Hope | 2.8% | $6.46 | 2.3% | 61.0% |
Top ASX 200 losers
[11:07 am] Seven of the ten top decliners are gold miners, while lithium and uranium names are also experiencing relatively broad-based weakness.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
SLX | Silex Systems | -6.2% | $4.27 | -17.1% | -49.3% |
EVN | Evolution Mining | -4.1% | $12.99 | -12.8% | 3.3% |
OBM | Ora Banda Mining | -3.9% | $1.46 | -6.7% | -4.6% |
WGX | Westgold Resources | -3.9% | $5.41 | -15.7% | -14.1% |
ELV | Elevra Lithium | -3.2% | $6.78 | -10.0% | -15.6% |
LLC | Lendlease Group | -2.9% | $2.69 | -6.3% | -48.3% |
WAF | West African Resources | -2.9% | $3.74 | -1.3% | 25.9% |
NST | Northern Star Resources | -2.8% | $22.00 | -5.5% | -10.4% |
MI6 | Minerals 260 | -2.8% | $0.88 | 8.6% | 109.5% |
RMS | Ramelius Resources | -2.6% | $3.68 | -5.6% | -10.0% |
Large caps drag the benchmark lower
[11:03 am] The S&P/ASX 20 is down 0.81% in early trade, reflecting weakness across large cap miners, banks and energy stocks. Things get better the broader you go, with the ASX 100 down 0.56%, ASX 300 down 0.49% and Small Ords trading around breakeven.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
BHP | BHP Group | -2.4% | $59.13 | -6.2% | 29.9% |
CBA | Commonwealth Bank | -1.4% | $152.83 | -5.1% | -4.8% |
RIO | Rio Tinto | -2.3% | $164.41 | -7.2% | 12.0% |
NAB | National Australia Bank | -0.9% | $38.36 | -2.3% | -9.3% |
WBC | Westpac | -0.4% | $34.38 | -1.9% | -10.7% |
ANZ | ANZ Group | -0.8% | $37.26 | -1.7% | 2.2% |
MQG | Macquarie Group | -1.5% | $241.25 | -3.1% | 18.8% |
WES | Wesfarmers | 0.6% | $73.02 | -5.5% | -9.9% |
CSL | CSL | 0.5% | $172.46 | 0.2% | -0.6% |
WDS | Woodside Energy Group | -1.6% | $32.56 | 1.3% | 37.2% |
ASX 200 hits a fresh three-month low
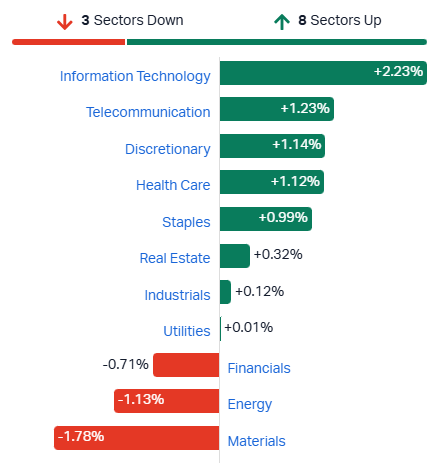
[10:58 am] Plenty of sectors trading higher, just not the important ones. The ASX 200 is down 50 pts (-0.58%) in early trade as Materials open lower for a fourth straight session and Financials snap a two-day bounce.
S&P/ASX 200 sectors (Source: Market Index)
New Hope's 30c final dividend more than doubles Bell Potter's forecast
[9:56 am] New Hope has declared a payout well ahead of expectations, funded off volumes and cash reserves rather than earnings, which fell sharply.
Final dividend of 30.0cps fully franked vs 14.0cps ests (114% beat), with that est already lifted from 10cps after the July quarterly, taking FY26 declared dividends to 40.0cps vs 24.0cps ests (67% beat)
The payout exceeds earnings, with 40.0cps declared against EPS of 19.1c, meaning roughly half the distribution is drawn from cash built up in prior years
Available cash up 10.1% to $778.5m and operating cash flow of $564.1m, comfortably covering the payment, though free cash flow of $371m came in well below the broker's expectation
The board tied the declaration to volumes and costs rather than profit, with coal sales up 11.8% to 11.8Mt against company guidance of 10.2Mt to 11.5Mt
Earnings held few surprises, with underlying EBITDA down 32.8% to $514.3m vs $514m ests (in line) and NPAT down 63.4% to $161.0m vs $183m ests (12% miss)
Company page: New Hope Corporation (NHC)
Explorer wrap: gold at depth, thick visual copper and a Timor-Leste expansion
[9:55 am] Here are some eye-catching explorer updates this morning.
Astral Resources returned 22m at 2.73g/t Au from 361m including 0.3m at 133g/t at the Theia deposit, with AMRCD424 delivering 49m at 1.23g/t from 252m and 2m at 12.8g/t from 390m, 15 holes into the 21-hole, 11,000m Theia Deeps program at Mandilla
American West Metals logged 140m of combined CRD-style copper and zinc sulphides plus 219m of visual molybdenite in WD26-07 at West Desert in Utah, drilled 350m along strike from the deposit, with assays expected in four to six weeks
Tivan secured approval from Timor-Leste's National Mineral Authority to add roughly 50km2 to its Baucau licence, capturing a 2.5km by 1km magnetic anomaly it will prioritise for copper-gold follow-up
McLaren drilling returned 24m at 7.54% HM from surface in MAC467, with 61 holes averaging 4.57% HM over 21.2m and every interval starting at surface with no HM cut-off applied
EQ Resources takes 10% of Nevada tungsten processing JV
[9:29 am] The tungsten producer has signed a binding framework agreement to restart the Springer APT plant alongside The Elmet Group and Blue Moon Metals, with funding support from the US Department of War.
EQR to hold 10% of the JV covering the 4,000tpa Springer ammonium paratungstate plant in Nevada, with Elmet on 70% as operator, Blue Moon on 20% and EQR entitled to one nominee director
Elmet funds the first US$75m of restart expenditure, with EQR's share of any costs between US$75m and US$100m capped at US$3.125m and costs above US$100m split pro rata
Eight-year spot-priced offtake under which the JV buys 4,000 tonnes of contained WO₃ from EQR, nominally 500tpa from commissioning, extendable by mutual agreement
Access to 1,000tpa of APT capacity for the first five years of operations, equal to 25% of Phase 1 capacity, plus a potential licence of EQR's ore-sorting technology to Blue Moon
EQR contributes technical expertise including engineering and project management oversight rather than upfront capital, with Blue Moon vending in the plant and granting the JV full offtake over Springer Mine concentrates
MD Craig Bradshaw called the deal transformational, saying it opens a strategic new market for the group's Australian and Spanish production
Company page: EQ Resources (EQR)
Software stocks set to rise
[9:23 am] Warnings from AI executives over the weekend hit chipmakers but drove a record rotation into software.
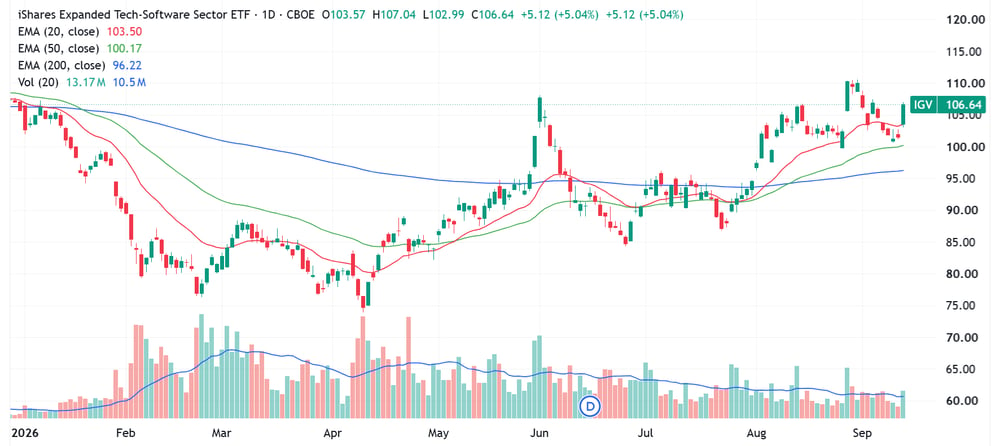
Software outperformed semiconductors by 10.7 percentage points, with the iShares Expanded Tech-Software ETF beating the iShares Semiconductor ETF by the widest single-day margin on record
CrowdStrike rose 13.8% to an all-time closing high, Palo Alto Networks gained 13% for its largest move since April 2025 and Fortinet closed up 9%
The iShares Expanded Tech-Software ETF is looking rather constructive, setting some higher highs, within 4% of the recent 27-Aug high and not far from breaking out to a near one-year high.
iShares Expanded Tech-Software ETF daily chart (Source: TradingView)
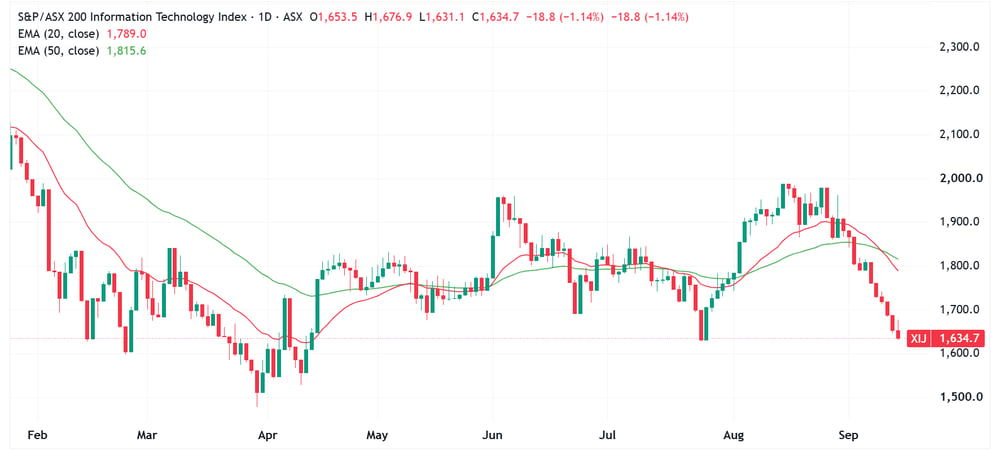
While US software names are on the mend, the local tech sector has fallen in pretty much a straight line, down 17.5% in the last three weeks.
S&P/ASX 200 Tech Index daily chart (Source: TradingView)
New Hope FY26 earnings fall on higher costs, final dividend well ahead
[9:06 am] New Hope delivered production and sales above the top of guidance, but higher overburden costs and depreciation drove earnings sharply lower, with the final dividend the standout.
Comparisons below are to Bell Potter ests only, not consensus.
Underlying EBITDA down 32.8% to $514.3m vs $514m ests (in line), with both saleable coal production and coal sales exceeding the upper end of guidance ranges
Statutory NPAT down 63.4% to $161.0m vs $183m ests (12% miss), on heightened costs from increased prime overburden movement and higher depreciation tied to the Bengalla Growth Project and New Acland ramp-up
Fully franked final dividend of 30.0cps vs 14cps ests (114% beat), with the Board pointing to increased production and disciplined cost control
Cash and fixed income investments of $778.5m, comprising $484.8m cash and $293.7m in other financial assets
Refinancing risk reduced through the issue of $300m of senior unsecured convertible notes due 2032 and repurchase of $293.3m of the existing 2029 notes, alongside a 3.00% lift in the Malabar stake to 25.97%
CEO Rob Bishop said the assets remain resilient and continue to generate solid margins through the cycle, with Bengalla back to its 13.4Mtpa ROM rate in the second half and New Acland Stage 3 still ramping
Company page: New Hope Corporation (NHC)
Netwealth acquires AI advice automation platform Paradino
[8:59 am] The platform provider is paying $20 million upfront for Paradino, extending its reach from platform administration into adviser workflow and document production.
Upfront consideration of $20m comprising $15m cash and $5m in Netwealth shares escrowed over four years, with up to a further $9m in earn-out and retention payments
Paradino generates ARR of $1.6m across more than 500 financial advisers, with churn below 1%, automating file notes, Records of Advice, Statements of Advice and client profiling
A further $10m will be invested in Paradino over the next two years to accelerate the product roadmap, reported separately from Netwealth's underlying results
Paradino is not yet break even, with FY27 EBITDA expected to be a loss of around $3m, and the deal not expected to materially affect near-term earnings
Existing guidance maintained on a pre-acquisition basis, with completion expected by the end of October 2026 subject to customary conditions
CEO Matt Heine said the combination can create Australia's leading AI-enabled wealth management and adviser productivity platform and unlock the full value of the Unify data platform
Company page: Netwealth (NWL)
Panther sells Mikado tenements to Brightstar for $350,000
[8:59 am] The junior explorer has agreed a binding tenement sale and a non-binding framework that could see Brightstar mine and process its Burtville East gold project.
Binding sale of five exploration licences comprising the Mikado Gold Project for $350,000 cash, payable at completion and providing non-dilutive working capital for Panther's remaining projects
Mikado sits adjacent to Brightstar's Beta operations, giving the buyer flexibility around future access and haulage routes as its Laverton footprint develops
Brightstar's 1.5Mtpa Laverton plant is under construction following a $193m equity raising, with first gold targeted for the June quarter of 2027
Non-binding HOA over Burtville East would see Brightstar fund and manage development, mining, haulage and processing, with net proceeds split 50:50 after recovery of project costs
The HOA also creates a framework for future discoveries across Panther's broader Laverton gold tenure to be considered as additional mill feed
MD Daniel Tuffin said the sale realises value from tenure worth more to Brightstar, while the HOA adds optionality for Burtville East and the wider Laverton portfolio
Company pages: Panther Metals (PNT), Brightstar Resources (BTR)
Hancock Prospecting takes 13.5% stake in White Cliff Minerals
[8:57 am] Gina Rinehart's Hancock Prospecting has agreed to a $8.8 million placement in the ASX-listed explorer, funding an accelerated drilling program at its Rae copper project.
White Cliff Minerals is a junior explorer whose flagship Rae Copper Project in Nunavut, Canada hosts both vein-hosted copper at Danvers and a sediment-hosted system across a roughly 6.3km² interpreted footprint
HPPL will invest $8,768,457 for 515,791,601 new shares at $0.017, struck at the previous day's close and subject to shareholder approval at an upcoming general meeting
Funds go toward expanded drilling, including resource definition at Danvers 1, step-outs at Danvers 2 and 3, and follow-up at regional targets Thor, Rocket, Vision and Stark
Maiden Danvers drilling returned 175m at 2.5% Cu and 8.66g/t Ag, 90m at 4% Cu and 58m at 3.08% Cu, with step-outs at Danvers 3 returning 20m at 6.64% Cu
All three 2026 sediment-hosted holes intersected visible chalcopyrite, extending mineralisation 3.7km east of the 2025 discovery hole
Managing Director Troy Whittaker said the timing could not be more compelling, with copper prices at record highs, supply tightening and demand still growing
Company page: White Cliff Minerals (WCN)
CurveBeam AI clears first FDA hurdle for CT-based bone density
[8:55 am] The imaging group has received 510(k) clearance for its CT-based bone mineral density technology, the first of two steps toward a SaaS revenue launch.
CurveBeam AI develops and manufactures point-of-care CT scanners for musculoskeletal conditions, led by its HiRise weight bearing CT platform, paired with AI-enabled SaaS clinical assessment tools
Clearance covers BMD measurement using multidetector CT supine scans, establishing a cleared regulatory foundation for broader BMD SaaS applications across the CT portfolio
The next step is HiRise, with the company to pursue a separate 510(k) for weight bearing standing CT BMD, which is the clearance required before SaaS revenue can launch
Commercial case rests on workflow, with a single CT examination potentially delivering anatomy, alignment and bone quality data and removing the need for a separate DXA appointment
CEO Greg Brown said this is the first of the two clearances necessary to take the SaaS-based bone health products to market
Longer-term optionality in surgical planning, with quantitative BMD data potentially becoming an additional layer in three-dimensional and robotic-assisted orthopaedic workflows, subject to clearance and validation
Company page: CurveBeam AI (CVB)
China's August credit rebound falls well short of expectations
[8:54 am] New yuan loans returned to positive territory after July's record contraction but badly missed forecasts, with household borrowing still shrinking.
New loans of 60bn yuan vs 400bn ests (85% miss), recovering from a 340bn yuan contraction in July but well down on 590bn a year earlier
January-August lending down to 10.44trn yuan from 13.46trn in the same period last year, underlining how tepid demand has become
Outstanding yuan loans up 4.9% year-on-year, slowing from 5.1% in July to the weakest pace on record
Household loans shrank 202.9bn yuan, a sixth straight month of contraction, while corporate loans rose 260bn after a 130bn fall in July
M2 up 7.5% year-on-year, a 17-month low and below ests of 7.6%, with total social financing growth easing to 7.2% from 7.4%
Capital Economics sees slim odds of a near-term rate cut, pointing to weak household appetite for debt-financed consumption rather than just mortgage demand
Source: Reuters
Macro Risk Advisors sees 8-10% S&P 500 pullback on Fed hikes
[8:48 am] Dean Curnutt has told clients a rate hike will trigger a correction, drawing a parallel with the 2018 tightening-driven selloff.
Curnutt expects an 8-10% pullback in the S&P 500 with a potential second leg lower in December as the Fed hikes into a K-shaped, low-churn economy
The S&P 500 is down nearly 1% so far in September, historically its weakest month, on elevated energy costs and inflation data that pushed 10-year yields above 5%
A quarter-point hike is now almost fully priced for Wednesday under Chairman Kevin Warsh, up from roughly 60% odds a week ago
Hikes will compress margins at companies unable to pass costs through, and deliver a volatility shock to a market not positioned for it
The 2018 analogue is central, with the S&P 500 peaking that September before falling 10% across October and November and eventually almost 20% from the peak
Curnutt argues a defensive posture is the correct approach given the setup
Source: Bloomberg
Saudi pipeline shutdown and Houthi gains squeeze oil's escape routes
[8:48 am] The closure of Saudi Arabia's East-West pipeline has collided with Houthi control of the Bab al-Mandeb, removing the two main workarounds that have kept crude flowing out of the Gulf through six months of the US-Iran war.
The East-West pipeline has averaged roughly 6m barrels a day during the war against full capacity of 7m, with Capital Economics estimating up to 4% of world supply could be taken offline and the AP reporting several weeks of outage
Yanbu inventories sit near 15m barrels, giving Kpler an estimated four days to depletion and Rystad five to seven, with Saudi Arabia now trying to push more volume through Hormuz having already lifted September exports toward 4m barrels a day
Freight is the binding constraint, with the cost of hauling crude from the Persian Gulf to China nearing US$1m a day on Friday for the first time, while August Saudi shipments of about 3m barrels a day were the lowest in at least nine years
Houthi forces captured Mocha and Perim island at the mouth of the Bab al-Mandeb, and MBS twice asked Trump for US air strikes on Houthi positions last week and was refused
Diplomacy stalled again with the Salalah summit on temporary Hormuz transit corridors postponed on Saudi objection, and Iran insisting it will only engage on ending the war if the US naval blockade is lifted
China rejects AI slowdown calls as Amodei pushes for tighter China curbs
[8:47 am] Beijing has dismissed calls from US AI executives to slow frontier model development, setting up a contested backdrop for US-China AI talks ahead of the Trump-Xi summit on 24 September.
AI stocks fell on Monday, with SoftBank down 10% in Japan, after Amodei, Sam Altman and Elon Musk backed a slower pace of capability development
Foreign Ministry spokesman Guo Jiakun said fearmongering and vicious competition would only disrupt global AI governance, with state media framing Amodei's essay as a containment playbook
Amodei's 3,800-word essay called for democracies to hold as large a lead as possible, continued curbs on advanced chip sales to China and a crackdown on distillation of US model outputs
The FBI, NSA and CISA issued a joint advisory alleging aggressive distillation of US frontier models by Chinese developers, which China's Commerce Ministry called groundless
Georgetown's Helen Toner estimated China's best models are six to nine months behind the US frontier, so a US slowdown risks letting Chinese labs simply close the gap
Beijing signalled no intention to slow, with its cyberspace regulator releasing an updated AI safety framework and state security minister Chen Yixin urging faster infrastructure buildout
BofA lifts S&P 500 target
[8:42 am] Bank of America strategists raised their year-end S&P 500 forecasts, with the forecast implying a 2.9% drop from where it closed overnight.
BofA's Savita Subramanian lifted her year-end target to 7,400 from 7,100, still the Street-low call, with a 12-month target of 7,800 or 2.4% above the latest level
Subramanian modelling EPS growth of 33% in 2026 and 12% in 2027 on AI capex, manufacturing and productivity, and Purves calling growth exceptional, durable and broad-based
Subramanian flagged pullback risk, noting only one 5% drawdown in 2026 against a typical three per year, with half of her bear-market signposts now triggered and any further rise in financing costs likely to hasten pain
Source: Bloomberg
Amodei's slowdown call collides with Anthropic's IPO window
[8:41 am] Anthropic's push toward a potentially record listing has been complicated by its own CEO calling for slower AI development, drawing a public attack from Donald Trump and raising questions over how investors price model-company growth.
Valued at US$965bn earlier this year, Anthropic filed its IPO prospectus confidentially in June, has selected the Nasdaq and could seek a US$2trn valuation, matching SpaceX's post-IPO mark
Annualised revenue reached US$65bn in July, roughly a sevenfold increase on the prior year, with the company telling some shareholders it will book a second consecutive quarter of operating profit
Amodei's weekend essay proposed third-party model evaluations, common safety standards among frontier labs and coordination between democratic and authoritarian governments, framed as achievable without sacrificing commercial advantage
Trump attacked Amodei on Truth Social, saying the only guardrail AI needs is a strong president, claiming criminal and regulatory power over the companies and calling opposition to AI data centres a conspiracy benefiting China
Analysts are split on valuation, with PitchBook arguing model companies deserve a discount and Deepwater's Gene Munster warning any perceived slowdown is a negative because the market underwrites uninterrupted model improvement
Read-through to AI infrastructure, given Anthropic's multibillion-dollar compute deals with Nscale, AMD, SpaceX and Google, heavy Nvidia GPU usage, and OpenAI targeting roughly US$600bn of compute spend by 2030
US 10-year yield breaches 5% as oil and supply pressures build
[8:39 am] US 10-year Treasury yields pushed above 5% for the first time since 2023 as energy-driven inflation fears collided with heavy government and corporate issuance, though equity weakness has so far stayed modest with the S&P 500 up more than 11% for the year.
The 10-year reached 5.01% on Monday, its highest since October 2023, before paring back to around 4.99% as dip buyers emerged, with the 30-year at 5.35% and the 2-year at 4.66%
Brent up 2.0% to US$106.47 a barrel, with the stalemated US-Israel war with Iran, continued obstruction of the Strait of Hormuz and Houthi movement toward Bab al-Mandeb keeping inflation risk elevated
Traders assign a 92.3% chance to a 25bp Fed hike on Wednesday, which would be the first increase since 2023 and comes after August CPI landed in line but well above the 2% target
Seventh straight monthly rise for the 10-year matches the longest run since 2011, leaving the yield roughly a full percentage point above pre-Iran war levels and Treasuries on course for their first annual loss since 2022
Bessent's expanded buyback of up to US$6bn of longer-dated debt has had little effect, with BMO noting it does not address the fundamental drivers of upward pressure on 10- and 30-year yields
Standard Bank's Steven Barrow lifted his 10-year forecast to 5.2% by year-end and 5.3% in Q1 2027, while CreditSights sees scope toward 5.5% on structural deficit, AI issuance and supply-chain pressures
Source: Bloomberg
Good morning!
[8:26 am] ASX 200 futures are down 14 pts (-0.15%). Here's what happened overnight:
Wall Street closed lower but well off its worst levels as a brutal chip selloff ran into a powerful bid for software and cybersecurity
S&P 500 (-0.48%), Equal-weight S&P 500 (+0.07%)
Nasdaq (-0.56%), Dow (-0.29%), Russell 2000 (-0.40%)
US 2-year yield up 3 bps to 4.66% (added 32 bps in the last six sessions)
US 10-year up 3 bps to 4.99% (up 22 bps in the last six sessions)
The AI trade split in two after the leaders of Anthropic, OpenAI and xAI called for a deliberate slowdown in frontier model development, hammering semiconductors while security and incumbent software names rallied
Rates and oil continue to weigh on markets, with the US 10-year briefly crossing 5% for the first time since 2023 and Brent up another ~2% to US$106 after Saudi Arabia shut its East-West pipeline
Commodities didn’t stand a chance against this higher rates and energy backdrop, with copper down ~2.3% to a fresh two-week low of US$6.4/lb