ASX 200 Live Today - Thursday, 24th September
The ASX 200 is set to tumble after the US 10-year yield surged back above 5.0% and oil spiked to US$103. Here are today's top stories.
Welcome to our live ASX coverage for Thursday, September 24. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
Macquarie trims Nufarm target after soft FY26 guidance
[12:52 pm] Nufarm's FY26 earnings guidance on Wednesday came in slightly below expectations ahead of next week's investor day, as strength in Seeds is offset by a weaker Crop Protection business. The stock dipped 6.2% on the day.
FY26 EBITDA guidance of $370–380m, with the $375m midpoint 2% below $384m ests
Crop Protection implied 2H26 EBITDA growth of -4.5%, slowing from +3% in 1H, on weaker North American volumes, adverse FX and outages at Wyke and Laverton
Seeds strength led by Hybrid Seeds and higher fish oil prices, with Macquarie forecasting emerging platforms EBITDA up $47m vs company guidance of $40m
Leverage is on track for about 2.0x at the end of FY26, though Macquarie expects it to rise seasonally to 3.0x in 1H27
Earnings cuts of 8% to FY26 EPS and 6% to FY27, with Macquarie's FY27 EBITDA now 8% below consensus
Target price down 3.3% to $2.90, with the Neutral rating retained ahead of the investor day on 28–29 September
Nufarm has been a rather extraordinary turnaround play. Heading into yesterday's guidance announcement, the stock was up around 76% since 24 March.
Company page: Nufarm (NUF)
UBS cuts KMD Brands target 27% but sticks with Buy
[12:50 pm] UBS has sharply cut its KMD Brands earnings forecasts on higher operating costs, but still sees value in the stock, particularly after the retailer disclosed takeover approaches (comparisons are to UBS ests only).
Target price down 27% to $2.55 from $3.50, with the Buy rating retained mainly on valuation grounds
Takeover interest KMD has received several indicative, non-binding approaches and is engaging with a limited number of parties
FY26 underlying EBITDA up 133% to $42m vs $41m ests (2% beat), including $8m in tariff refunds
Kathmandu sales up 11%, with 2H26 about 7% ahead of ests on stronger direct-to-consumer sales in NZ and Australia
Underlying opex up 4% to $565m vs $545m ests (4% miss), as $28m in cost savings was swamped by inflation, growth spending and FX
Earnings cuts of 20–29% to underlying EBITDA for FY27–29, with UBS's FY28 EBITDA margin of 6.3% well short of KMD's 10% target
Company page: KMD Brands (KMD)
Australian unemployment rises to 4.6%
[12:49 pm] Australia's jobless rate rose more than expected in August as more people looked for work, days before the RBA meets to consider resuming rate hikes.
Unemployment rate up to 4.6% from 4.5% vs 4.5% ests, with the trend rate also edging up to 4.6%
Employment up 39,500 vs 20,000 ests, almost double what economists expected
Participation rate up 0.2ppt to 67.1%, as more people previously outside the labour force began looking for work
Full-time jobs down 6,300, with part-time roles up 45,800 driving the headline gain
Hours worked up 0.7%, recovering the 14 million hours lost in July
Tuas bounces on still-solid growth and cash pile
[11:59 am] Tuas is one of today's standout movers, up 8.1% to $1.93. The rebound follows a sharp 23.3% selloff on Wednesday, when regulatory concerns overshadowed an otherwise better-than-expected FY26 result.
Here's what the Blog noted yesterday (comparisons are to Morgan Stanley ests as of 14 September, not consensus):
Revenue up 24% to S$187.6m vs S$185.7m ests (1% beat), driven by a growing subscriber base
Underlying EBITDA up 22% to S$83.7m vs S$83.0m ests (1% beat), with the underlying margin steady at 45%, while statutory EBITDA of S$80.1m includes pre-acquisition costs
Underlying NPAT of S$29.6m vs S$22.7m ests (30% beat), up from S$6.9m in FY25, with statutory NPAT of S$26.0m against ests of S$17.5m
Mobile subscribers up 16% to 1.458m vs 1.505m ests (3% miss), implying net adds of around 204k against the 251k modelled, with gross mobile ARPU of S$9.42
The M1 acquisition lapsed after the sale and purchase agreement hit its 21 May long-stop date without IMDA clearance, the regulator having suspended its review on 17 May pending an investigation into intermittent use of spectrum SIMBA had previously been authorised to use for specific purposes
What stands out is Tuas' cash pile of S$498.8m (A$554m). Most of that (S$359.8m) came from an August 2025 raise at $5.51 per share, a nil discount, to fund the M1 acquisition. That leaves the stock with net cash backing of roughly $1.00 per share, on top of a solid and growing Singaporean telco business. After what looked like forced selling on regulatory concerns yesterday, a bounce is understandable.
Banks at a fresh three-month low
[11:43 am] The S&P/ASX 200 Financials Index has undercut the recent low to trade at the lowest since 12 June and now down 2.95% year-to-date.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
WBC | Westpac | -1.9% | $34.10 | -3.5% | -11.4% |
ANZ | ANZ Group | -1.7% | $37.18 | -1.1% | 2.0% |
NAB | National Australia Bank | -1.6% | $38.04 | -1.9% | -10.0% |
CBA | Commonwealth Bank | -1.6% | $148.69 | -3.3% | -7.4% |
JDO | Judo Capital | -1.0% | $0.95 | -4.0% | -46.6% |
BEN | Bendigo & Adelaide Bank | -0.9% | $10.23 | -2.5% | -3.4% |
BOQ | Bank Of Queensland | -0.9% | $6.49 | -2.4% | -1.1% |
MQG | Macquarie Group | -0.7% | $240.68 | -0.9% | 18.6% |
A broad-based tumble for miners
[11:43 am] The ASX 200 Materials index is down 1.96%, wiping out its gains from the past two sessions. It has been a familiar pattern for the sector this year, with sharp runs to record highs followed by equally sharp pullbacks. After rallying almost 20% between 20 July and 26 August, the index had fallen as much as 11% by 15 September. A brief bounce over the past few days has now faded, leaving the sector back on the back foot.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
LTR | Liontown | -5.7% | $0.99 | -2.9% | -36.9% |
LYC | Lynas Rare Earths | -4.9% | $13.96 | 1.9% | 12.4% |
CRN | Coronado Global | -4.8% | $0.20 | -4.8% | -37.5% |
PLS | PLS Group | -4.7% | $3.99 | -4.7% | -5.1% |
IGO | IGO | -3.1% | $6.73 | -3.7% | -17.9% |
NIC | Nickel Industries | -2.7% | $0.82 | 0.2% | -6.6% |
MIN | Mineral Resources | -2.6% | $53.33 | -3.7% | -2.0% |
CMM | Capricorn Metals | -2.6% | $15.23 | 7.0% | 8.8% |
PRU | Perseus Mining | -2.6% | $6.67 | 3.5% | 21.0% |
BHP | BHP Group | -2.4% | $60.55 | -0.7% | 33.0% |
Oil eases as Hormuz flows back in focus
[11:38 am] Oil tumbled in Asian trade after a near 5% jump on Wednesday, as US officials again suggested large volumes of crude are still getting through the Strait of Hormuz.
Brent down 5.7% to US$97.41 a barrel
Hormuz flows Bessent said 17m barrels a day "sometimes" transit the strait, though Clarksons Research put the figure nearer 8m earlier this month
Saudi pipeline traders are waiting for details on restarting exports via the East-West pipeline, which was damaged in attacks earlier this month
US diesel futures up 0.3% to US$4.79 a gallon, steadying after Wednesday's slump on export ban speculation
Diplomacy fades Macquarie's Walt Chancellor said "optimism around speedy diplomatic solutions" to the war "seems to have been greatly diminished"
Source: Bloomberg
ASX 200 dips to a fresh three-month low
[10:36 am] The ASX 200 never stood a chance after a weak overnight lead. Brent spiked back above US$100 (though it has since pulled back 5% to US$97 this morning), US bond yields surged to fresh highs, and key commodities like gold and copper tumbled. The index is down 104 points or 1.19%, erasing the past six sessions of gains to trade at its lowest level since 12 June. That leaves the benchmark slightly negative for the year, down 0.6%. Yield and US dollar-sensitive sectors are leading the declines, headed by Materials, Real Estate and Financials.
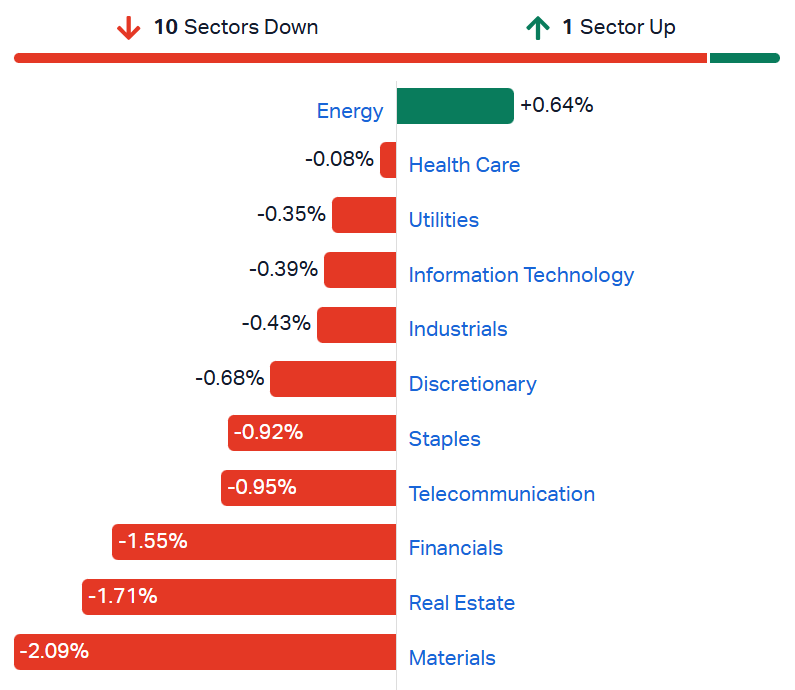
S&P/ASX 200 sectors (Source: Market Index)
Top ASX 200 gainers
[10:30 am] Tuas is bouncing back after Wednesday's 23% results-driven selloff, while Premier Investments is higher on a solid FY26 result. Soul Patts is also catching a bid after extending its dividend growth streak to 28 years.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
TUA | Tuas | 6.7% | $1.91 | -10.6% | -73.0% |
PMV | Premier Investments | 4.3% | $11.64 | 1.8% | -16.0% |
MSB | Mesoblast | 2.8% | $2.24 | 9.8% | -17.9% |
SOL | Washington H. Soul Pattinson | 2.7% | $46.72 | 3.6% | 25.6% |
NWH | NRW | 2.3% | $8.31 | 6.5% | 66.2% |
ALD | Ampol | 1.4% | $44.70 | 2.1% | 40.0% |
TNE | Technology One | 1.4% | $29.44 | 1.0% | 6.8% |
STO | Santos | 1.2% | $8.50 | -2.3% | 37.5% |
FPH | Fisher & Paykel | 0.8% | $36.24 | 1.9% | 9.8% |
360 | Life360 | 0.7% | $19.37 | 1.1% | -39.9% |
Top ASX 200 losers
[10:30 am] Zip tumbles amid a broad-based pullback for BNPL names (Affirm and Sezzle down 5.1% and 2.8% overnight), while copper, gold and lithium names open broadly lower.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
ZIP | Zip Co | -6.0% | $2.11 | -5.6% | -35.6% |
NEC | Nine Entertainment Co | -5.9% | $0.68 | -15.3% | -38.6% |
CYL | Catalyst Metals | -5.5% | $5.82 | -10.9% | -21.1% |
IPX | Iperionx | -5.5% | $2.77 | 7.8% | -49.7% |
ALK | Alkane Resources | -5.2% | $1.89 | -4.0% | 42.3% |
FFM | Firefly Metals | -5.0% | $1.71 | -1.2% | -17.0% |
KCN | Kingsgate Consolidated | -4.8% | $5.16 | -2.1% | -7.9% |
LTR | Liontown | -4.6% | $1.00 | -1.8% | -36.2% |
ELV | Elevra Lithium | -4.3% | $6.06 | -6.0% | -24.5% |
SLX | Silex Systems | -4.2% | $4.32 | -0.5% | -48.8% |
Lindian stockpiles 125,000t ahead of Kangankunde start-up
[9:47 am] Lindian Resources has built up ore stockpiles at its Kangankunde rare earths project in Malawi ahead of schedule, and remains on track for first concentrate by the end of 2026.
ROM stockpile of about 125,000t of ore is already in place, ahead of schedule, providing feed for a controlled ramp-up
Mining underway in the Stage 1 pit, with 14 production blasts completed
Plant construction is running 24 hours a day, now focused on mechanical, piping, electrical and instrumentation works
First production of monazite concentrate targeted by end-2026, with practical completion on track
Power connection of 33kV infrastructure is substantially advanced, with site energisation planned for October 2026
Tailings facility bulk earthworks are complete, with toe dam lining and piping works progressing
Company page: Lindian Resources (LIN)
Wia builds 7Mtpa expansion option into Kokoseb plant
[9:46 am] Wia Gold will build design provisions into its Kokoseb process plant so throughput can later be lifted by a third without costly retrofits.
Expansion capacity of about 7.0Mtpa, up from the DFS design basis of 5.25Mtpa
Provisions cost US$9.3m, about 2% on top of the DFS pre-production capex estimate of US$475m
Scope covers equipment sizing, plant layout, structural allowances and supporting infrastructure
DFS unchanged with no change to the mine plan, Ore Reserve, production profile or development strategy
Ore supply the DFS mine schedule already generates enough ore movements and stockpiles to support an expansion
Next step SENET has been instructed to include the selected provisions in front-end engineering
Company page: Wia Gold (WIA)
Premier Investments dividend beats as retail EBIT lands in line
[9:43 am] Premier Investments delivered FY26 retail earnings in line with its August guidance, as record Peter Alexander sales offset a weaker Smiggle.
For context, PMV lowered its FY26 guidance in August, with retail EBIT down to $176m (from $183m). This drove an 11% selloff on the day, to $11.96.
The below ets refer to UBS, not consensus.
Premier Retail sales down 2% to $795.5m vs $796.7m ests (in line)
Peter Alexander sales up 3.2% to a record $565.3m
Smiggle sales down 12.9% to $230.2m, with store numbers down 13% to 268 since the start of FY25
Premier Retail EBIT of $175.9m vs $175.2m ests (in line), matching August guidance
Margins held up, with a 22.1% EBIT margin and 65.2% gross margin
Statutory NPAT of $129.2m (unclear if comparable to UBS est of $144.0m ests)
Full-year dividend up 62% to 81cps fully franked vs 73.6cps ests (10% beat), including a 36cps final
Loyalty program Peter's Dreamers drew over 1.4 million members in its first 10 months and contributed more than 60% of Peter Alexander sales
1H27 trading Premier Retail sales and gross profit for the first seven weeks were both within 1% of the pcp on a like-for-like constant currency basis
Company page: Premier Investments (PMV)
Soul Patts NAV up 31% as dividend streak hits 28 years
[9:29 am] Washington H. Soul Pattinson grew net asset value and cash generation in FY26, its first full year since the Brickworks merger.
Net cash flow from investments up 11.5% to $572m, driven by Credit, Private Companies and industrial property, and up 8.3% per share
Post-tax NAV up 31.4% to $14.5bn, or 27.2% per share, helped by the tax position reset through the Brickworks merger
Pre-tax NAV up 10.4% to $13.7bn, a 10.2% return vs 6.0% for the ASX200 Total Return Index
Operating NPAT of $319m, the core earnings line excluding portfolio gains and one-off items
Statutory NPAT up 502% to $2.19bn, inflated by a $1.3bn day-one accounting gain and tax reset from the Brickworks merger
Final dividend up 6.8% to 63 cps fully franked, the 28th consecutive year of dividend growth
Outlook FY27 conditions are expected to stay uncertain around rates and bond yields, with $3.8bn in available liquidity to deploy
Company page: Soul Patts (SOL)
OFX drops FY27 growth outlook as Equals deal progresses
[9:26 am] OFX has extended exclusivity with UK-based Equals on its proposed takeover, but warned trading in FY27 has been tougher than expected.
OFX shares tumbled 22.7% to 57.5 cents on Wednesday on concerns that the Equals takeover bid was collapsing or stalling.
Offer reconfirmed at $1.00 cash per share, valuing OFX's equity at $247m, adjustable by up to 4c either way depending on OFX's cash balance
Due diligence substantively complete, with Equals still finalising its debt financing
Exclusivity extended to 30 October 2026 to allow the financing to be finalised
Board intention to unanimously recommend the scheme, subject to financing, an acceptable SID, no superior proposal and a supportive independent expert
FY27 outlook cut OFX no longer expects to grow group NOI or corporate active clients this year
2Q27 NOI is expected to be around 5% higher than 1Q27, with the company still targeting positive operating leverage
Company page: OFX Group (OFX)
ACCC clears I Squared's oOh!media takeover
[9:25 am] oOh!media's proposed acquisition by I Squared Capital has cleared a key hurdle, with the ACCC determining the scheme may proceed.
ACCC clearance received under the Competition and Consumer Act, satisfying a key condition of the Scheme Implementation Agreement
Remaining approvals from FIRB and New Zealand's Overseas Investment Office are still progressing
Timetable has the scheme booklet due in early October 2026 and the shareholder vote in early November
Board recommendation remains unanimous, absent a superior proposal and subject to the independent expert's conclusion
Company page: oOh!media (OML)
Kaoko expands Chalkos drilling to 15,000m
[9:25 am] Kaoko Metals has expanded drilling at its Chalkos copper-silver project in Namibia after visual copper hits at Otniel and a new surface discovery at Donkey Hill East.
Drill program expanded to at least 15,000m on the strength of visual copper mineralisation in DDOT001 and DDOT002
Otniel drilling five diamond holes completed with a sixth underway, and assays for the first two holes due in 2–3 weeks
Donkey Hill East rock chip sample Z2516 graded over 50% Cu, extending the known surface trend by more than 700m
Donkey Hill trend mapped surface expression now exceeds 1.5km, making it a high-priority target alongside Otniel
Second rig mobilised, with drilling at Donkey Hill starting this week
Company page: Kaoko Metals (KAO)
Genus wins $135m WA wind farm contract
[9:24 am] GenusPlus has won a design and construct contract from Atmos Renewables to build grid connection works for a 470MW wind farm in Western Australia.
Contract value of about $135m, including early works already done on detailed design, long-lead procurement and bulk earthworks
Scope covers a 330kV terminal, 330kV transmission lines and ancillary works at the Parron Maam Marang Farm substation in Badgingarra
Conditions precedent remain for the construction phase, including Atmos reaching financial close, signing connection agreements an
Completion is expected in 2028, with the project backed by the Federal Government's Capacity Investment Scheme as WA exits coal by 2030
Repeat client Riches said the award builds on Genus' work with Atmos on the Merredin BESS Project
Company page: GenusPlus Group (GNP)
Bond yields break out as market breadth thins
[9:07 am] Here's my little rambling about the overnight session and the state of play.
Headline resilience Markets have held up well in recent weeks, all things considered. The S&P 500 suffered a mere ~2.5% drawdown before V-shaping back towards record highs, while the ASX 200 endured a sharper ~6.5% pullback and has steadied in recent days
Under the hood, the picture is far less convincing. The S&P 500's rebound has been narrow and tech-led, with the equal-weight index still 3.7% below its 13 August record on Monday, even as the headline index traded within 0.5% of all-time highs
Laggards include the Russell 2000, which barely bounced, while the Dow, a better gauge of the economy and cyclicals, continues to trend lower
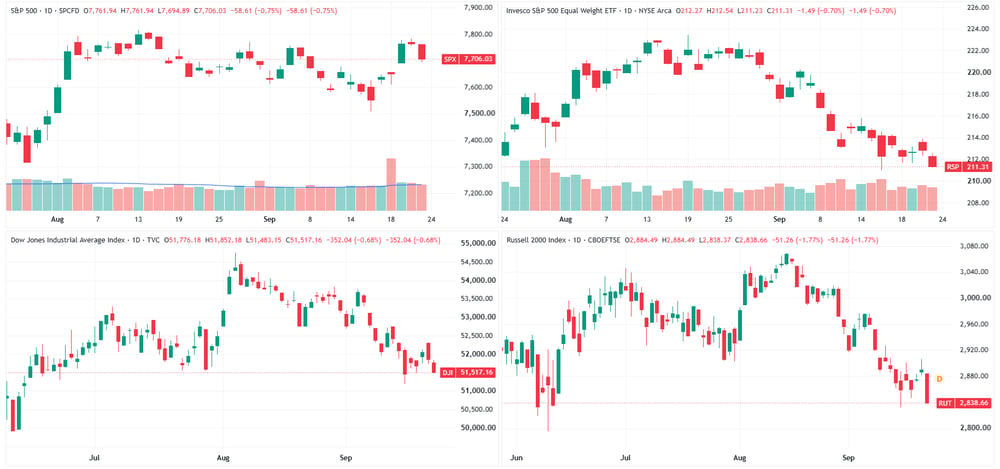
Major US benchmarks daily charts (Source: TradingView)
Then there are bond yields. After stalling or slipping in recent days, they made a massive move overnight. The 2-year jumped 12bps to 4.89% as traders ramped up bets on further hikes, while the 10-year surged 14bps to 5.11%, yet another "highest since 2007".
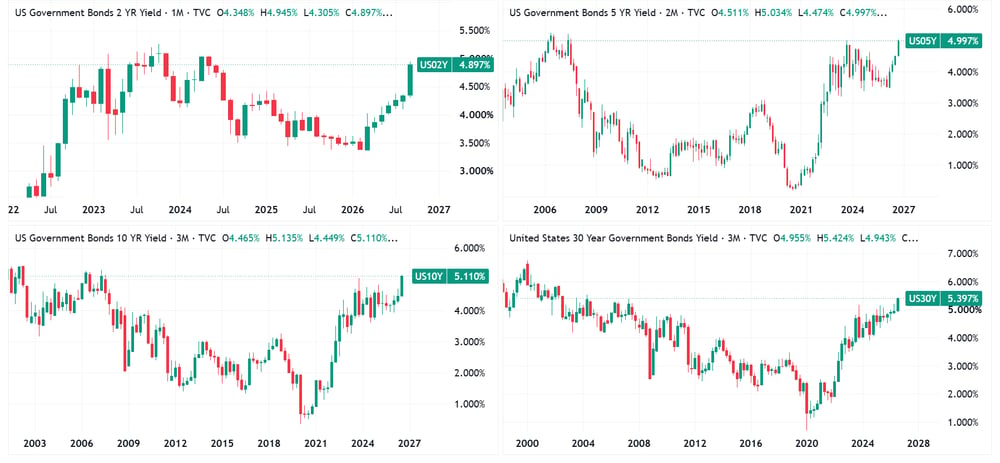
US bond yield charts (Source: TradingView)
Brent also snapped a six-day losing streak, up 4.8% overnight to US$103.30 a barrel.
In a nutshell: Markets are back on the back foot, and the path of least resistance looks choppy at best. The past few days offered some reprieve, but markets are still in "show me" mode, waiting for more evidence of the 10-year below 5.0% and inflationary inputs heading in the right direction.
US flash PMI hits five-year high
[8:47 am] US business activity grew at its fastest pace in more than five years in September, with S&P Global saying the data point to annualised GDP growth of around 5%.
Composite PMI up to 58.4 from 56.0 in August, the fastest expansion since July 2021 and a fourth straight month of acceleration
Services activity index up to 58.7 from 56.5, a 59-month high, with new orders growing at the fastest pace since March 2022
Manufacturing PMI up to 57.0 from 53.9, the strongest improvement in conditions since May 2022
Input cost inflation hit its highest since October 2022 on higher fuel and transport costs, with wage pressures also picking up
Employment rose at the fastest rate since June 2022, with factory payrolls growing at the quickest pace since February 2021
Capacity strain backlogs rose at the sharpest rate since May 2022, which Williamson said signals "companies are developing more pricing power"
Source: S&P Global
Eurozone flash PMI hits 41-month high
[8:45 am] Eurozone private sector growth sped up in September, with S&P Global saying the survey points to quarterly GDP growth of 0.4%.
Composite PMI up to 53.1 from 52.0 in August, the fastest expansion since April 2023
Services activity index up to 53.0 from 51.6, a 10-month high
Manufacturing output index up to 53.4, a 55-month high, with Germany leading on AI and defence spending
France returns to growth with activity up for the first time in 10 months, while Germany grew at its fastest pace in just under a year
Input costs and output prices rose at the sharpest rates in four months on higher energy prices from the Middle East conflict
ECB hike risk as resilient growth will likely embolden the ECB to hike before year-end, putting "an October hike very much on the table"
Source: S&P Global
US open to extending China trade truce
[8:42 am] Bessent said the US is open to extending the Busan truce or pursuing a bigger deal ahead of Trump-Xi talks at the White House on Thursday.
Truce expiry the deal lapses on 10 November, and Bessent said the US is "fine with both" an extension or a bigger deal floated by Beijing on Sunday
Board of Trade the process for tariff cuts on non-strategic goods could cover Chinese consumer and low-tech exports, and US energy, agriculture and medical devices
Soybeans China has bought almost half of its 25mt annual commitment, with purchases tending to cluster around leader meetings
Boeing orders Greer said about 140 of the 200 pledged aircraft are in a "good state", but customers and delivery timelines haven't been disclosed
Rare earth magnet shipments down 20% to 512t in August from July, and down 13% year on year, with US officials saying deliveries are "not up to par"
Uneven delivery CMC Markets' Eric Xiao said "the truce is moving fastest where it costs least"
Source: CNBC
Disney+ ad-free price rises 13%
[8:41 am] Disney is lifting US streaming prices for the sixth year in a row as it pushes to grow profits in its direct-to-consumer business.
Disney+ ad-free up 13% to US$21.49 a month, still below Netflix's US$26.99 premium plan
Ad-free Disney+ and Hulu bundle up US$2 to US$21.99, just 50c more than a single standalone service
Ad-supported standalone plans up 50c to US$12.49, while the ad-supported bundle holds at US$12.99
Entertainment operating income up 64% in the third quarter, driven by subscriber growth and a double-digit streaming margin
Platform push CEO Josh D'Amaro says Disney+ will add merchandise, games and experiences from spring 2027
Source: Bloomberg
Diesel export ban talk rattles fuel markets
[8:40 am] Trump's backing for a US diesel export ban jolted futures and refiner stocks, while industry and analysts warn the move would backfire.
US diesel futures down 3.4% to US$4.78 a gallon after sliding as much as 7.5% on a Politico report of a 90-day ban, which a White House official disputed
Voluntary curbs Energy Secretary Chris Wright said the administration is working with refiners to cut exports voluntarily rather than use "a blunt hammer"
Refiners sold off Valero, Marathon Petroleum and Phillips 66 fell after the Politico report
Export exposure US diesel exports hit a record near 2m barrels a day this summer, with Brazil the top buyer in September, followed by Chile, Mexico, the UK and the Netherlands
Retail diesel at US$6.52 a gallon, nearly US$3 higher than a year ago, raising political pressure ahead of November's midterms
Backfire risk Rapidan's Bob McNally expects brief Gulf Coast relief before prices "soar globally", with a risk Europe retaliates by curbing gasoline exports to the US
Source: Bloomberg
Iran sets hard line on Hormuz as talks stall
[8:40 am] Iran's president used his UN address to rule out reopening the Strait of Hormuz while the US blockade remains, undercutting tentative signs of progress in New York.
Hormuz stance Pezeshkian said Iran won't allow freedom of navigation through the strait while sanctions and the US naval blockade stay in place
Tehran's conditions include the US immediately lifting the blockade, unfreezing Iranian assets and ending the war "on all fronts", a likely reference to Lebanon
Talks yield little Rubio said there was no major breakthrough, while Trump called the meetings "very good" despite threatening to "annihilate" Iran
Toll dispute Iran is in talks with Oman on a Hormuz arrangement, but its push to charge ships fees is opposed by the US and Gulf states
UK bank sanctions Britain will automatically reject new licence applications from designated Iranian banks and won't renew a general licence next month
Airline sanctions Iranian carriers kept flying to Thailand, China and Turkey despite a US deadline, with Airports of Thailand saying it needs government direction to act
Houthi escalation the Iran-backed group now controls all of Yemen's Red Sea coast, threatening a route that carries about 12% of the world's seaborne goods
US 10-year yield hits highest since 2007
[8:38 am] Treasuries sold off sharply as hot activity data, a hawkish Fed governor, a weak auction and elevated oil prices all hit on the same day.
10-year yield up 15 bps to 5.10%, its highest since July 2007 and the biggest one-day move since April 2025
2-year yield up 15 bp to 4.89%, the highest since May 2024, as traders added to bets on an October hike
Five-year auction US$70bn sale cleared at 5.033% vs a 4.186% six-auction average, with indirect bidders taking 54% vs a 65% average
Treasury buyback of up to US$6bn in 20 to 30-year debt on Thursday failed to stem the selloff, with the 30-year yield hitting a session high of 5.38%
IIF warning the Institute of International Finance said buybacks may give temporary relief but cannot resolve the structural drivers of rising debt
Re-tightening cycle Wells Fargo Investment Institute's Tony Miano said the entire curve is repricing at once, lifting discount rates for equities and borrowing costs
Wall Street slides as oil and yields climb
[8:37 am] US stocks fell from near-record levels as Brent settled around US$103 and hot activity data stoked inflation fears.
S&P 500 down 0.8% from near-record levels, with the Nasdaq 100 off 0.9% and the Dow down 0.7%
Bloomberg Dollar Spot Index up 0.6% as the greenback gained against all major currencies, with the yen easing to 158.32
Overheating risk FHN Financial's Will Compernolle said an economy strong enough to add to price pressures "necessitates a more aggressive and urgent approach to tightening"
Microsoft upgraded to buy at Stifel, one of the few cautious Wall Street firms after the stock's lagging run this year
Nvidia credit default swaps are now among the most traded in the US CDS market as investors hedge after June's US$25bn bond sale
Source: Bloomberg
Good morning!
[8:27 am] ASX 200 futures are down 104 pts (-1.19%). Here's what happened overnight:
Major US benchmarks finished broadly lower after yields surged and Brent snapped a five-day win streak, surging 5% to US$103.45
S&P 500 (-0.75%), Equal-weight S&P 500 (-0.70%)
Nasdaq (-1.13%), Dow (-0.68%), Russell 2000 (-1.77%)
Bond rout deepens as red-hot US PMIs and a hawkish Barr pushed the US 10-year yield 15 bps higher to 5.11%, the highest since 2007
October hike bets build after a weak five-year auction and Barr's call for more tightening, while Eurozone activity surprises to the upside
Oil snaps its losing streak as Iran's Pezeshkian vows no surrender at the UN, with Bessent open to extending the China trade truce ahead of the Trump-Xi summit