ASX 200 Live Today - Thursday, 17th September
The S&P/ASX 200 is trading higher off the back of bank and healthcare gains. Here are today's top stories.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Thursday, September 17. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
ASX 200 higher, but off best levels
[2:30 pm] That's a wrap! The ASX 200 is up 23 pts (+0.27%), well off an early rally of 1.0%. The bounce looks like relief after a widely expected and hawkish Fed hike, with most of that hawkishness arguably priced in already.
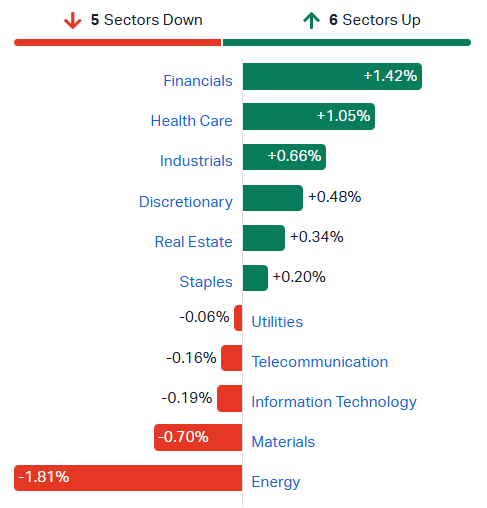
Financials (+1.3%) bouncing off three-month lows, most bank stocks up around 1.5%
Healthcare (+0.9%) on a four-day win streak after the 9-11 Sep pullback, back near highs last seen in Feb-26
Real estate (+0.8%) rebounding after closing at its lowest since Jan-24 on Tuesday
Materials (-0.7%) giving back part of Tuesday's 1.2% bounce. The sector sits 10.5% below its 26-Aug record high and around 2.2% above the 200-day moving average
Energy (-1.6%) broadly lower after Brent fell 2.6% overnight to US$105.86
Overall, a bounce but nothing much has changed underneath. The US 10-year still trades with a five handle, breadth is choppy at best, and former leaders like the miners have pulled back hard. Brent is holding triple digits. So perhaps more of a wait-and-see how the dust settles moment.
Aurelia Metals director Franklyn Brazil adds $1.7m of stock on market
[1:39 pm] The change of director's interest notice shows an on-market purchase made on 14 September, which was announced on Tuesday, 3:42 pm AEST.
Brazil acquired 4,000,000 ordinary shares at an average price of $0.429, for total consideration of $1,717,082
The purchase was made indirectly through registered holder Brazil Farming Pty Ltd, with no securities disposed of
The indirect holding rises by 1% 409,357,179 ordinary shares from 405,357,179 prior to the transaction
The stock is up 4.6% to 45 cents, despite the broader All Ords Gold Index trading 2.1% lower.
Company page: Aurelia Metals (AMI)
Copper steadies as traders look past the Fed's hawkish signals
[1:37 pm] The metal held its ground despite a stronger dollar and the prospect of another US rate increase this year.
Copper was 0.2% lower at $14,202.50 a ton on the LME at 10:30am in Singapore, little changed after the Fed's widely expected hike
The metal is still consolidating after last week's record, driven by bets the US would apply tariffs to refined copper and pull vast quantities into American stockpiles
Washington has so far held off on new trade measures, with RBC's Sam Crittenden noting reports of no US copper tariffs unwound some physical market speculation while fundamentals remain constructive
Data centre and renewables demand plus supply disruptions at key mines continue to provide support
Other metals were mixed, with aluminium down 0.5%, nickel up 0.4% and iron ore futures 0.2% higher at $96 a ton in Singapore
Source: Bloomberg
Top ASX 200 gainers
[12:18 pm] Defence stocks top the leaderboard, while an add mix of speculative growth names, Telix and Dyno Nobel also trade notably higher.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
DRO | Droneshield | 7.2% | $1.74 | 0.7% | -43.4% |
EOS | Electro Optic Systems | 5.8% | $9.80 | 5.0% | 3.8% |
4DX | 4DMedical | 5.6% | $3.74 | 9.4% | -6.5% |
ASB | Austal | 4.6% | $4.54 | 0.0% | -32.4% |
TLX | Telix Pharmaceuticals | 4.6% | $17.64 | 5.0% | 56.8% |
DNL | Dyno Nobel | 4.3% | $4.03 | 1.4% | 25.8% |
ASX | ASX | 4.2% | $55.33 | 1.1% | 7.4% |
IPX | Iperionx | 4.1% | $2.67 | -10.3% | -51.6% |
JDO | Judo Capital | 2.8% | $1.00 | 0.7% | -44.0% |
Top ASX 200 losers
[12:18 pm] Gold, lithium and energy stocks are trading sharply lower at noon.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
WAF | West African Resources | -7.6% | $3.51 | -11.6% | 18.2% |
PNR | Pantoro Gold | -7.1% | $2.62 | -3.0% | -46.5% |
ELV | Elevra Lithium | -6.6% | $6.11 | -23.6% | -23.9% |
LNW | Light & Wonder | -4.9% | $117.57 | -5.1% | -24.2% |
KCN | Kingsgate Consolidated | -4.8% | $5.11 | -7.0% | -8.8% |
S32 | South32 | -4.4% | $4.79 | -8.1% | 34.9% |
BPT | Beach Energy | -4.2% | $0.86 | -3.1% | -26.3% |
KAR | Karoon Energy | -4.0% | $1.82 | -0.5% | 18.2% |
IGO | IGO | -3.8% | $6.77 | -15.0% | -17.4% |
RMS | Ramelius Resources | -3.6% | $3.49 | -8.6% | -14.7% |
Guangdong power reform clouds China's gas demand outlook
[12:17 pm] Wood Mackenzie says gas plants in the province have shifted from baseload to peaking duty, with implications for global LNG demand growth.
Guangdong holds about one-third of China's gas-fired capacity and switched last year from guaranteed operating hours and regulated tariffs to purely economic dispatch
Generators must now compete to recover fuel costs, with standby payments to support the grid increased, according to WoodMac principal analyst Kai Dong
Gas plants are increasingly balancing intermittent renewables rather than delivering baseload, with imported LNG needing to fall to around $6/MMBtu to displace coal against spot prices near $30
Dong said the key question for global LNG is how much less demand growth this implies, with other provinces following similar frameworks
China was the largest LNG importer last year but has slowed purchases and re-routed cargoes after the near-closure of the Strait of Hormuz lifted prices to three-year highs
LNG is the segment most exposed to price spikes, with cheaper gas sourced domestically or via pipelines from Russia and Central Asia
Source: Bloomberg
What outperformed during the last Fed hike cycle?
[11:19 am] The previous major Fed rate hike cycle ran from March 2022 to July 2023. The first hike landed on 16 March 2022, a 25 bp move that lifted rates from 0-0.25% to 0.25-0.50%.
This was widely expected, as the US 2-year yield had already surged from 0.72% at the start of the year to 2.0% by the time the Fed moved. The ASX 200 rallied in the weeks that followed, up around 5.8% between 16 March and 21 April 2022. The unwind was pretty aggressive as yields continued to surge and inflation prints were hot, very hot. The ASX 200 fell 15% from that 21 April high to the 21 June low, then chopped sideways until yields finally peaked in October 2023.
The table below shows the ASX 200 stocks that outperformed during the initial leg down, from 16 March to 21 June. Most were already running hot on the fallout from Russia-Ukraine.
Ticker | Company Name | 16-Mar to 21-Jun 2022 | 1 Year | Close Price (21-Jun) |
|---|---|---|---|---|
SLX | Silex Systems | 56.0% | 105.3% | $1.95 |
YAL | Yancoal | 20.3% | 149.0% | $5.03 |
ALX | Atlas Arteria | 19.9% | 27.5% | $7.59 |
VEA | Viva Energy | 18.7% | 33.8% | $2.73 |
AGL | AGL Energy | 15.1% | -9.7% | $8.32 |
WHC | Whitehaven Coal | 14.9% | 135.2% | $4.54 |
NHC | New Hope | 13.4% | 72.1% | $3.21 |
RHC | Ramsay Health Care | 12.3% | 10.4% | $71.41 |
ALD | Ampol | 11.7% | 10.0% | $32.01 |
APA | APA Group | 10.0% | 19.1% | $11.16 |
EMR | Emerald Resources | 9.8% | 31.1% | $1.18 |
MIN | Mineral Resources | 9.2% | -0.5% | $48.31 |
AZJ | Aurizon | 7.8% | 3.5% | $3.87 |
TCL | Transurban | 7.6% | -5.4% | $13.93 |
WOR | Worley | 7.6% | 10.5% | $13.39 |
DRO | Droneshield | 5.9% | 12.5% | $0.18 |
AMP | AMP | 5.9% | -15.7% | $1.00 |
BXB | Brambles | 5.9% | -7.5% | $10.49 |
NHF | NIB Holdings | 5.5% | 13.2% | $7.12 |
GNC | Graincorp | 4.6% | 76.5% | $9.09 |
Banks lift the ASX 200 higher
[10:58 am] The ASX 200 is currently up 32 pts (+0.38%), as gains from healthcare and banks offset softness across resources.
S&P/ASX 200 sectors (Source: Market Index)
Some sizable gains across banks today, though most names are trading around breakeven for the year.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
JDO | Judo Capital | 2.6% | $1.00 | 0.5% | -44.1% |
BEN | Bendigo & Adelaide Bank | 2.3% | $10.49 | 3.2% | -0.9% |
NAB | NAB | 2.1% | $38.82 | 2.1% | -8.2% |
WBC | Westpac | 1.9% | $35.09 | 2.4% | -8.9% |
BOQ | Bank Of Queensland | 1.7% | $6.66 | 2.5% | 1.5% |
CBA | Commonwealth Bank | 1.6% | $153.97 | -0.1% | -4.1% |
ANZ | ANZ Group | 1.6% | $37.60 | 2.7% | 3.2% |
MQG | Macquarie Group | 0.6% | $241.33 | -2.1% | 18.9% |
Morgan Stanley sees limited direct major bank risk from Bathla collapse
[10:19 am] The investment bank says the residential developer's voluntary administration is unlikely to hit the majors directly, but flags second-order stress across construction and property development.
Morgan Stanley holds a cautious industry view on Australia banks and sees second-order effects emerging through SME stress, tighter funding conditions and weaker property valuations rather than direct exposure
Construction exposures total around A$58bn across the majors, at roughly 1.5% of non-mortgage exposures at ANZ, 2% at CBA and 2.5% at NAB and Westpac, with bank disclosures suggesting around 20% is unsecured and a further 35% partially secured
Commercial property exposures total around A$393bn, at about 7% of total group exposures and 13.5% of non-mortgage exposures, with CBA largest at around A$119bn, NAB A$99bn, Westpac A$98bn and ANZ least exposed at A$77bn
Residential-related loans of around A$69bn account for about 21% of commercial property loans, split roughly CBA A$20.5bn, Westpac A$18bn, ANZ A$15.5bn and NAB A$15bn
Disclosure of sector overlays is limited to NAB, where commercial property and construction forward looking adjustments rose to a combined A$110m in 1H26 from A$66m in 2H25, still below the A$220m average held over 2022-24
The 2009 experience offers a stress guide, with around 12.5% of Westpac's commercial property exposures stressed including 26% for developers, against just 2% of the CP portfolio stressed at 1H26 and 5% of construction exposures
Company pages: ANZ (ANZ), Commonwealth Bank (CBA), National Australia Bank (NAB), Westpac (WBC)
Omega wins Taroom Trough acreage, lifting operated area 63%
[9:58 am] The Queensland Government has named the Omega-led joint venture as preferred tenderer for a 1,138km2 land release block adjoining its existing Canyon acreage.
Omega Oil & Gas is an ASX-listed explorer targeting unconventional oil and gas in the Taroom Trough in southern Queensland, where its Canyon Project Area is the core asset
The joint venture comprises Omega at 45% and operator, Tri-Star E&P at 30% and Beach Energy at 25%, selected as preferred tenderer for PLR2026-1-10 following a competitive tender
Operated acreage expands 63% to 2,947km2 from 1,809km2, with the new area covering the eastern flank and southernmost part of the trough adjoining the southern portion of the 100% owned Canyon PCA Area, being PCA 342 and PCA 343
The new ground sits on trend with the Canyon Project Area, where oil and gas flows have been proven and current drilling is demonstrating a resource base the company describes as vast
Tenure grant remains subject to completion of the Queensland Government's processes
The 2026/27 appraisal campaign remains on schedule, comprising four vertical wells and one or two horizontal wells, with Canyon-4 progressing toward the primary objective Canyon Sandstone interval and further rig contract options available
Company page: Omega Oil & Gas (OMA)
Echo IQ maps path back to FDA clearance for EchoSolv HF after NSE knockback
[9:56 am] The medtech says the issues behind the FDA's Not Substantially Equivalent determination are confined to clinical validation statistics rather than the device itself.
The company received a Not Substantially Equivalent determination on its initial 510(k) application, disclosed on 8 September 2026, and is now working with regulatory consultants and legal counsel to advance clearance
The stock tumbled 50% the following trading session (9-Sep) from $1.28 to 64 cents
Matters cited by the FDA relate to aspects of statistical analysis supporting clinical validation, with the company saying its assessment identified no concerns regarding the underlying technology or core functionality
Three pathways are under assessment, being an administrative appeal, review through the FDA Ombudsman, or a new 510(k) submission, with the company confident clearance remains achievable under the 510(k) route
An appeal could see the NSE determination overturned, the FDA reopening its review, or a request to resubmit with clarity on what must be addressed, with timelines not strictly defined and potentially shorter than 90 days
Clearance could potentially be achieved over the coming quarters, with no material impact to strategic partner agreements following the regulatory activity
Company page: Echo IQ (EIQ)
Stakk completes US$63m ParaScript acquisition, tripling revenue base
[9:55 am] The microcap has closed its cash and scrip purchase of the US document intelligence business, funded in part by a A$27 million institutional placement.
Stakk is an ASX-listed AI-native Digital Trust business focused on pre-execution fraud prevention, and acquired ParaScript for US$63.0m (A$88.7m) in cash and scrip
The combined group is positioned to deliver A$55.2m revenue and A$18.5m EBITDA in FY27, representing a 34% EBITDA margin, following 1,098% revenue growth in FY26
A substantial majority of FY27 revenue is already supported by contracted customer commitments, giving forward revenue visibility
The enlarged group serves more than 300 enterprise customers and handles 110 billion digital interactions annually across the US, Europe, the Middle East and Australia, combining ParaScript's 30-plus years of document intelligence with Stakk's fraud prevention
ParaScript CEO Emiliano Giacchetti has been appointed CEO of Stakk IQ, with a proposed Group CEO appointment to be considered at the AGM, and has become a top 20 shareholder
Giacchetti and non-executive director Arthur Lo led director and management participation in the A$27.0m institutional placement, with several new contract wins and extensions flagged in coming weeks
Company page: Stakk (SKK)
Transurban August traffic lifts 3.4%, led by North America
[9:32 am] The monthly update shows group average daily traffic growth accelerating from July, with West Gate Tunnel still doing much of the domestic heavy lifting.
Group ADT up 3.4% on the prior corresponding period, ahead of July's 4.0% pace on a comparable basis and up from 0.1% in May
North America ADT up 12.3%, with the 95 Express Lanes growing 3.8% and the 495 Express Lanes 26.1%, aided by capacity from the recently opened 495 Northern Extension
Average dynamic toll prices rose 5.8% on the 95 Express Lanes and 36.0% on the 495 Express Lanes
Melbourne ADT up 3.5% driven by West Gate Tunnel, though excluding WGT Melbourne traffic fell 0.8% and group ex-WGT growth was 1.9%
Sydney traffic up 3.3%, supported by M7 growth of 11.8% following the opening of the M7-M12 Integration Project, while Brisbane rose 1.0% on large vehicle growth of 3.7%
Management flagged the macro environment as a watchpoint including renewed conflict in energy-producing regions, noting more than 90% of revenue is CPI-linked or subject to fixed escalators with inflation flowing through over up to 18 months
Company page: Transurban (TCL)
Contact Energy August operating update shows cheaper generation and stronger hydro storage
[9:31 am] The monthly update points to a sharp fall in generation costs alongside well above average South Island storage and Clutha inflows.
Mass market electricity and gas sales up 21% to 550GWh, with mass market netback broadly flat at $148.57/MWh against $148.36/MWh a year earlier
Unit generation cost down 29% to $40.90/MWh including acquired generation, while own generation cost fell 35% to $27.38/MWh
Contracted wholesale electricity sales down 0.3% to 1,087GWh and electricity and steam net revenue up 0.2% to $164.59/MWh, with electricity generated or acquired down 4% to 1,125GWh
South Island controlled storage sat at 166% of mean as at 13 September and total Clutha scheme storage at 138%, though North Island controlled storage was below average at 84% of mean
Clutha catchment inflows ran at 164% of mean in August, up from 132% in July and against 89% in May
Otahuhu Q4 2026 futures settled at $45.50/MWh as at 15 September, up from $39.50/MWh at the end of August but below the $51/MWh at the end of July, with contracted gas volume including swaps of 8.2PJ for the next 12 months
Company page: Contact Energy (CEN)
Iran conflict escalates on multiple fronts as Saudi supply risk builds
[9:20 am] Attacks on Saudi energy infrastructure, a contested IAEA vote and downed aircraft point to a widening conflict with direct consequences for crude supply.
Houthi spokesman Yahya Saree claimed attacks on Aramco facilities at Yanbu and an airbase at Khamis Mushait, days after a strike on the East-West pipeline forced Saudi Arabia to suspend Yanbu loadings
The pipeline carries about 4 million barrels a day, roughly 4% of global supply, to the Red Sea, with the US energy secretary expecting flows to resume within days while sources told Reuters repairs could take five to six weeks
Brent fell 2.6% to US$105.61 a barrel, after Saudi Arabia offered additional cargoes via Oman, though passage through the Strait of Hormuz remains constrained
Saudi air defences intercepted a drone near Makkah, with coalition spokesman Turki al-Malki calling the security of the Two Holy Mosques a "red line" and vowing deterrent measures
Iran secured a seat on the IAEA conference organising committee by 44 votes to 35 with 42 abstentions, overriding US objections, with inspectors unable to verify Iran's uranium stockpile since June 2025
US Vice President JD Vance said Washington cannot let its Middle East policy be "subservient to the state of Israel", signalling some daylight between the allies as the war runs into its seventh month
BOJ set to lift rates to a 31-year high on Friday
[9:14 am] The Bank of Japan is expected to hike for the first time in three months, joining the Fed and ECB in leaning against oil-driven inflation.
The policy rate is set to rise to 1.25% from 1%, a 31-year high, with board member Toichiro Asada seen as a possible dissenter after opposing the June hike
A move to 1.25% would bring policy inside the BOJ's estimated 1.1% to 2.5% nominal neutral range, raising questions on how much further it can go, with hawkish board member Naoki Tamura putting neutral around 2%
Reuters-polled analysts expect 1.5% by end-March next year and 1.75% in the second quarter of 2027, with most seeing the terminal rate at 1.75% or higher
Ueda said earlier this month that with underlying inflation "quite close" to the 2% target, the BOJ must pay particular attention to inflationary risks, having warned in July of an overshoot from fuel costs, a weak yen and strong AI demand
Source: Reuters
Trump demands 1% rates hours after the Fed hikes
[9:12 am] The President resumed his pressure campaign on the central bank after Wednesday's quarter-point increase, without naming Warsh directly.
Trump posted on Truth Social that US rates "should be 1%, or less, because we are the Best Credit in the World", adding "LOWER THE INTEREST RATES FOR THE UNITED STATES OF AMERICA, AND FAST!"
The Fed lifted its benchmark a quarter point to a 3.75%-4% target range in a unanimous 12-member FOMC vote, with the statement noting inflation remains elevated and updated projections showing a strong majority expect another increase
Trump had threatened less than two weeks ago to cut off trade with countries running surpluses with the US if the Fed did not cut, a group covering most of its major trading partners
Trump and his aides have so far avoided attacking Warsh personally, despite the chairman being his own pick to replace Jerome Powell
White House spokesman Kush Desai said Trump "absolutely" still believes in Fed independence, while defending his right to speak out
History says the first hike of a cycle stings before it pays
[9:11 am] With the Fed lifting rates 25bp on Wednesday, strategists are pointing investors to what has happened after previous first hikes.
The Kobeissi Letter found the S&P 500 has fallen an average of 4.0% over the six weeks following the first hike of a cycle across seven episodes since 1988, before recovering all of those losses over the next five to six weeks on average
Returns turn positive further out, with the index up an average 4% six months after a first hike and 9% after 12 months, positive in every episode bar 2022
Goldman Sachs research points the same way, showing an average 2% decline in the months immediately after a hike followed by an average 9% gain over the following year
Cross-asset moves were mixed, with the 10-year Treasury yield up to 5.02%, gold off 0.67% to $4,263.91 and Brent crude down 2.69% to $105.83 a barrel after Saudi Arabia offered extra cargoes via Oman
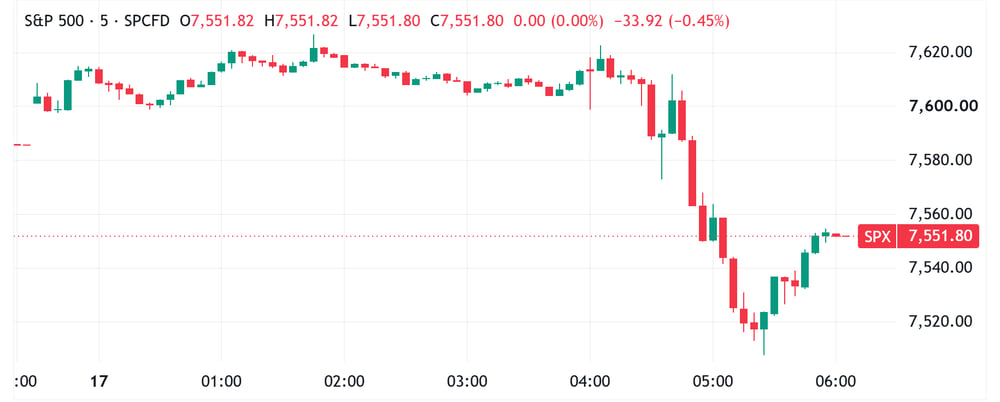
S&P 500 tanks on the Fed Press Conference
[8:46 am] The S&P 500 was trading around 0.30% higher heading into the press conference. By 5:25 am AEST, it was down as much as 1.0%, but bounced strongly in the last 30 minutes of trade.
S&P 500 intraday chart (Source: TradingView)
Bond market signals growing faith in Warsh after first Fed hike since 2023
[8:44 am] The Fed lifted rates on Wednesday and flagged further tightening, prompting traders to reprice the path higher.
Traders are now pricing three additional Fed increases by the middle of next year, one more than before the decision, with swaps indicating the first could land as soon as next month
Two-year Treasury yields climbed to 4.74% from 4.6% before the announcement, the highest since 2024, while long-term inflation expectations tumbled
Longer-dated Treasuries trailed the move, flattening the gap between two- and 30-year yields to the tightest since March 2025 on a closing basis
Warsh said recent inflation data "do not tell me that underlying trends have meaningfully improved", with the Fed framing the hike as support for a faster return to its 2% target
10- and 30-year yields hit their highest since 2007 ahead of the decision, driven by the energy supply shock since February and heavy corporate borrowing to fund AI spending
Source: Bloomberg
Fed hikes for the first time since 2023 and signals more to come
[8:43 am] The FOMC lifted rates a quarter point and its new projections point to further tightening, sending US stocks and bonds lower.
The federal funds target was raised 25bp to 3.75%-4% on a unanimous 12-0 vote, the first increase since July 2023 and a shift from July, when officials held steady with three dissents in favour of a hike
The dot plot turned hawkish, with 16 of 18 officials seeing at least one more quarter-point increase this year, up from six in June, and the median end-2026 outlook lifting to 4.1% from 3.8%
Forecasts were revised with 2026 headline inflation at 3.7% from 3.6%, core at 3.4% from 3.3%, GDP at 2.3% from 2.2% and unemployment at 4.1% from 4.3%, while the return to 2% inflation was pushed out to 2029
Warsh said the Fed "removed a dose of accommodation" and that this summer's readings "do not tell me that underlying trends have meaningfully improved", with Morgan Stanley's Michael Gapen reading the accommodation line as hawkish
Swaps now imply three further increases by the middle of next year, one more than before the meeting, running ahead of even the most hawkish FOMC dots
Good morning!
[8:24 am] ASX 200 futures are down 63 pts (-0.72%). Here's what happened overnight:
The Fed hiked for the first time since 2023 and in-line with market expectations
Markets were trading slightly higher heading into the Fed decision but tanked on Fed Chair Kevin Warsh's press conference
S&P 500 (-0.45%), Nasdaq (-0.01%), Dow (-1.21%) and Russell 2000 (-0.40%)
The dot plot median showed two 25 bp hikes in 2026 and nine in 2027, vs. the June forecast of just one hike in 2026 and a cut in 2027, but dovish compared to market pricing for four straight hikes by June 2027
Warsh refused to guide on what comes next, leaving the two-year yield at its highest since 2024 and the US dollar at a six-week high
Oil retreated below US$103 on a surprise industry inventory build and signs Saudi Arabia's East-West pipeline could restart within days