ASX 200 Live Today - Monday, 5th October
The S&P/ASX 200 is trading slightly higher, well-off session highs of 0.62%. Here are today's top stories.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Monday, October 5. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
ASX 200 fades from early highs in quiet holiday session
[2:15 pm] That's a wrap! It was a fairly uneventful session, with the NSW public holiday keeping a lid on activity despite Friday's tech-led bounce on Wall Street. The ASX 200 is up 9 points or 0.10%, well off its session high of 0.62%. Most sectors faded through the day. Materials rose as much as 0.99% in early trade before easing to a 0.37% gain, Financials slipped back to 0.22% from a session high of 0.85%, and Staples swung from a 0.70% gain to a 0.45% decline. It was a quiet start to the week after a volatile one, which featured a post-RBA and CPI rally followed by a Thursday selloff. Elsewhere, Brent is down 1.2% to US$101 a barrel, Aussie bond yields are fractionally higher after their recent pullback and US futures are broadly flat. The economic calendar is light this week, with the FOMC minutes on Thursday the main event.
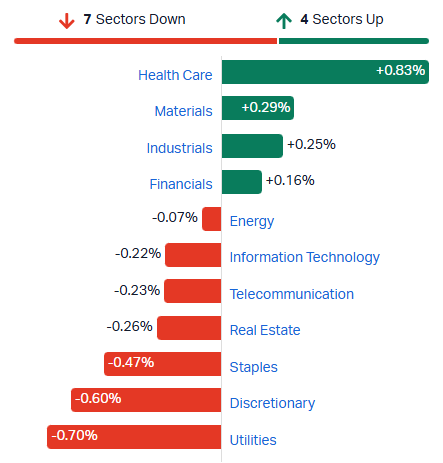
S&P/ASX 200 sectors (Source: Market Index)
Firmus to allocate half of IPO to existing investors including Nvidia
[2:00 pm] Firmus has priced its IPO at $11 a share, valuing the AI data centre operator at about $43.7bn, with investor demand well in excess of the offer size.
IPO priced at $11 a share, implying a valuation of about $43.7bn, short of earlier expectations
About half of the shares will go to existing shareholders, putting Nvidia and Blackstone in a position to increase their stakes, according to people familiar with the matter
Raising up to US$5.5bn including a greenshoe, on par with Medibank's 2014 float as one of Australia's largest IPOs
Bookbuild close brought forward to Thursday from Friday
Proceeds will fund GPU purchases for its first data centre in Batam, Indonesia, as part of an eight-year partnership with Nvidia
MAAS Group's 3.2% stake is worth about $1.4bn at the IPO price, according to Macquarie
Source: Bloomberg
Emerging market stocks rally as Fed hike bets cool
[2:00 pm] Emerging market stocks and currencies rose after soft US jobs data and lower oil prices eased concerns about aggressive Fed rate hikes.
MSCI's emerging market equities gauge rose as much as 1.1%, the most in about two weeks, while an index of EM currencies gained 0.3%
TSMC jumped more than 3%, leading tech gains on optimism about a potential collaboration with Elon Musk's Terafab
Brazilian assets gained after Flávio Bolsonaro unexpectedly finished ahead of President Lula in the first round of the presidential election
Chinese EV makers including BYD fell in Hong Kong on a report the UK plans to impose levies on imports
Lombard Odier's Homin Lee remains tactically bullish on EM equities and hard currency bonds, citing the broadening global capex boom
Source: Bloomberg
Housing slump could cost states $30bn as higher yields lift interest bills, says UBS
[1:40 pm] UBS warns that falling property tax revenue and rising borrowing costs could leave Australian government deficits larger than budgeted, potentially complicating the RBA's task.
State revenues could fall ~$30bn below May and June budget updates over the forward estimates, under a scenario where stamp duty drops 20% in FY27
Revenue hit of $5.5bn in FY27, rising to $8.75bn in FY28, with Victoria and Queensland the most exposed
Higher-priced homes are falling faster, with the upper quartile down 2.1% year-on-year vs the bottom quartile up 9.2% in August, so the near-term hit could be larger
Higher yields could add $7bn to $12bn to government interest costs over four years, with 10-year yields of ~5.4% well above the 4.8% borrowing cost assumed in the budget
Planned FY27 fiscal tightening may not happen if deficits widen, partly offsetting tighter financial conditions and adding to bond issuance
UBS expects home prices to fall almost 10% peak-to-trough, around the largest downturn since at least 1980, and still sees a 25bp RBA hike, most likely in November
Macquarie lifts MAAS Group target 21% on Firmus stake
[1:22 pm] Macquarie has started valuing MAAS Group's 3.2% stake in Firmus, and sees material upside if the AI infrastructure company's IPO prices in line with media reports.
Outperform retained, with the target lifted to $8.15 from $6.75, mainly on a conservative $1.42ps for the Firmus stake based on its last raise at a ~$15.5bn equity value
Firmus IPO could price at a ~$43.7bn market cap according to media reports, implying ~$1.4bn or $4.00ps for MAAS's stake
Construction Materials sale to Heidelberg Materials has completed, with $1.61bn received and up to $120m in contingent consideration still to come
Buyback of up to 20% of issued capital was approved at the AGM, with ~14m shares bought back recently
EPS estimates lifted by 5%, 6% and 11% for FY27 to FY29 on lower D&A and interest costs and the buyback
Company page: MAAS Group (MGH)
Saudi Arabia cuts Asia oil price to six-year low as Hormuz flows recover
[12:34 pm] Aramco has unexpectedly cut its flagship crude price to Asia for November, as oil flows through the Strait of Hormuz continue to rebound.
Arab Light for November set at a US$5 a barrel discount to the regional benchmark, from a US$2 discount in October
Traders and refiners surveyed by Bloomberg had expected a US$5 increase
Middle East crude exports are at 98% of prewar levels, according to JPMorgan, with Saudi Arabia restoring much of the flow through its damaged East-West pipeline
Shipping costs remain high, with many buyers avoiding Hormuz and producers transferring cargoes to tankers waiting in the Gulf of Oman
Source: Bloomberg
Fortescue hits a 14-month low
[12:30 pm] Fortescue has been in a steady grind lower since June, now down 26.5% year-to-date and trading at its lowest since 22 July 2025. This largely mirrors recent weakness in iron ore prices, with have tumbled 13% since mid-May to US$90.90 a tonne.
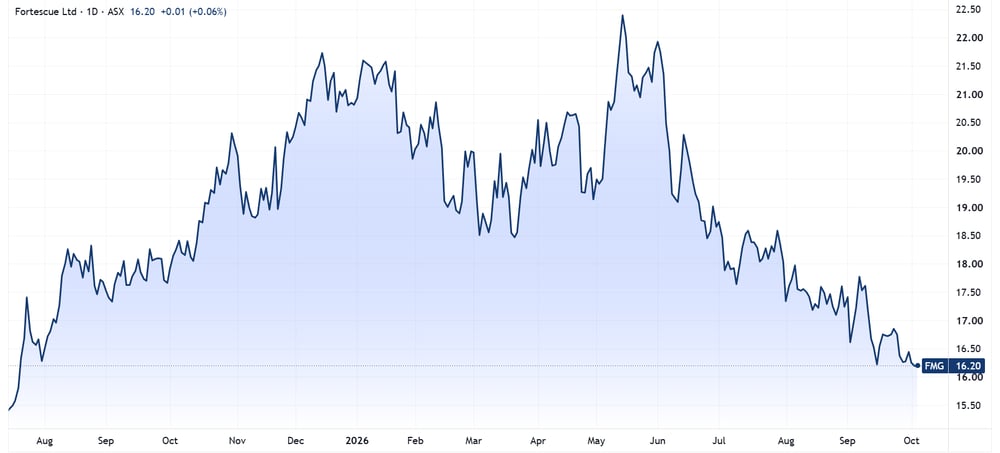
Fortescue price chart (Source: TradingView)
Interestingly, two brokers have turned constructive on iron ore last week, just as the steelmaking ingredient heads into its seasonally strongest stretch, with November and December historically averaging gains of about 4-6%.
UBS lifts its long-term iron ore forecast to US$93/t from US$85/t
Global South demand, led by India, is expected to offset China's construction decline through 2035 as China pivots to manufacturing and exports, according to UBS
About 800Mt of depletion and falling grades will offset 120Mtpa of new Simandou supply, tightening iron units more than ore tonnes suggest, according to UBS
Cost curve support is rising, with spot at ~US$95/t sitting around the 93rd percentile and 100Mt to 150Mt of supply at breakeven or cash negative, according to UBS
Benchmark prices are down more than 10% year-to-date and higher shipping costs are forcing marginal supply cuts, though Simandou and softer Chinese steel demand cap the upside, according to Macquarie
Fortescue remains Macquarie's counter-consensus pick for a near-term recovery, with any weakness tied to CMRG at the upcoming quarterly seen as a buying opportunity
Codan hits another record high
[11:24 am] Codan is up another 1.7% to a record $68.63, building on last week's 28.6% rally after a trading update (29-Sep) flagged a sharp lift in first half earnings on conflict-driven Communications demand.
Communications H1 revenue guided to $400m to $410m, up 80% to 85%, with conflict regions making up about 50% of revenue vs about 20% in the pcp
Minelab's H1 revenue run-rate is slightly above H2 FY26 levels, helped by new detector launches and a favourable gold price
Communications EBIT margin of about 40% vs 26% in the pcp and 31% in FY26
H1 NPAT of at least $160m, up at least 125% and already 91% of FY26's $175.2m
FY27 Communications revenue growth target lifted to 30% to 40% from about 20%, implying H2 revenue of $248m to $309m vs $284.4m in H2 FY26
On Thursday, UBS retained a Neutral rating and lifted its target to $68.50 from $47.90, saying the H2 guide assumes no new conflict-related wins and looks conservative
Company page: Codan (CDA)
Engineering stocks ride the data centre boom to record highs
[11:21 am] Engineering stocks are arguably one of the strongest pockets of the market right now. Most names are trading at or near record highs, pullbacks have been shallow and quickly bought, and the sector remains one of the clearest ways to play the data centre buildout.
Southern Cross Electrical leads the pack today, after Macquarie initiated coverage with an Outperform and $5.60 target price.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
SXE | Southern Cross Electrical Engineering | 8.0% | $5.24 | 10.3% | 108.8% |
GNP | Genusplus Group | 4.2% | $9.84 | 6.7% | 55.0% |
TEA | Tasmea | 2.5% | $11.00 | 2.8% | 160.7% |
NWH | NRW | 1.4% | $8.14 | 1.7% | 62.7% |
SKS | Sks Technologies Group | 1.4% | $11.03 | 8.3% | 175.1% |
GNG | GR Engineering Services | 1.1% | $7.53 | -0.9% | 69.5% |
SRG | SRG Global | 0.5% | $3.95 | -1.5% | 32.6% |
Macquarie initiates on Southern Cross Electrical at outperform
[11:17 am] Macquarie has initiated coverage of Southern Cross Electrical Engineering, backing its exposure to the data centre construction cycle.
Outperform rating with a $5.60 price target, implying 15% upside to Friday's close of $4.85
FY27 EBITDA guidance of at least $100m is supported by recent contract wins, with data centres driving the next leg of growth, according to Macquarie
More than $60bn of data centre construction is underway or likely to proceed, according to Macquarie
Data centre pipeline of $1bn for Southern Cross Electrical
Credible path for FY27 data centre revenue to triple from $120m in FY26, according to Macquarie
The stock is up 26% in the past month and up 110% year-to-date. Its FY26 result on 19 August reported:
Revenue fell 10.3% to $718.7m as the CBESS and Western Sydney Airport terminal projects wrapped up
Gross margin rose to 19.0% from 13.2%, driving underlying EBITDA up 40.5% to $77.0m
Underlying NPAT rose 24.3% to $39.4m, while statutory NPAT fell 77.6% to $7.1m on $46.1m of WestConnex dispute costs
Dividends rose 33.3% to 10.0cps, with a record $261.5m cash balance and no debt.
The order book hit a record $810m
FY27 EBITDA guidance was at least $100m, with data centre revenue forecast to triple from $120m.
Company page: Southern Cross Electrical Engineering (SXE)
Top ASX 200 gainers
[10:34 am] Not too many high-profile gainers this morning, with Ingenia creeping higher on sweetened deal from Warburg Pincus, while gold and copper miners are on the mend.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
INA | Ingenia Communities Group | 2.7% | $4.91 | 4.5% | -5.6% |
CDA | Codan | 1.9% | $68.70 | 30.7% | 141.7% |
MND | Monadelphous Group | 1.8% | $31.79 | 4.3% | 20.2% |
SOL | Washington H. Soul Pattinson | 1.7% | $46.02 | -1.8% | 23.7% |
MI6 | Minerals 260 | 1.7% | $0.88 | -3.8% | 109.5% |
NWH | NRW | 1.5% | $8.14 | 1.8% | 62.8% |
REH | Reece | 1.5% | $16.99 | 6.1% | 27.4% |
CSC | Capstone Copper Corp | 1.5% | $14.33 | -1.0% | -5.5% |
EVT | EVT | 1.4% | $14.15 | 3.2% | 10.6% |
OBM | Ora Banda Mining | 1.4% | $1.50 | -3.2% | -2.3% |
Top ASX 200 losers
[10:34 am] Droneshield pulls back after a 13% gain in the last three sessions and tech stocks take a breather after last Friday's broad-based rally.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
DRO | Droneshield | -3.3% | $1.77 | 10.0% | -42.7% |
WTC | Wisetech Global | -2.8% | $32.51 | 3.8% | -52.5% |
DYL | Deep Yellow | -2.7% | $1.09 | -12.1% | -40.8% |
XRO | Xero | -2.2% | $56.58 | -1.4% | -50.3% |
4DX | 4DMedical | -2.1% | $4.25 | 6.3% | 6.3% |
GDG | Generation Development Group | -1.7% | $2.68 | -1.7% | -54.6% |
QBE | QBE Insurance | -1.5% | $23.45 | 1.7% | 19.0% |
MIN | Mineral Resources | -1.5% | $50.23 | -3.0% | -7.7% |
EOS | Electro Optic Systems | -1.4% | $11.33 | 1.5% | 20.0% |
VUL | Vulcan Energy Resources | -1.3% | $1.71 | -10.2% | -61.3% |
ASX 200 stocks making 52-week highs and lows
[9:53 am] Here's a quick look at the S&P/ASX 200 stocks that hit fresh 52-week highs or lows last week.
Real Estate: 0 Highs, 11 Lows
Industrials: 1 High, 5 Lows
Materials: 0 Highs, 4 Lows
Financials: 0 Highs, 4 Lows
Technology: 2 Highs, 3 Lows
Telecommunications: 0 Highs, 3 Lows
Energy: 0 Highs, 2 Lows
Discretionary: 0 Highs, 1 Low
Health Care: 2 Highs, 0 Lows
Utilities: 0 Highs, 0 Lows
Staples: 0 Highs, 0 Lows
Aspen Group lifts 1Q EBITDA 38% as rental margins expand
[9:39 am] Aspen's 1Q FY27 result came in above management's expectations, led by the rental pool, with long stay accommodation essentially full and rents estimated at ~10% below market.
Rental revenue up 10% to $21.7m
Net rental income up 16% to $12.7m, with the margin expanding to 58% from 55%
Realised development profit up 96% to $7.9m
EBITDA up 38% to $17.8m
Pre-tax EPS up 34% to 7.1c
FY27 underlying EPS growth of at least 20% reaffirmed
Company page: Aspen Group (APZ)
Dimerix hits four-year patient milestone in DMX-200 program
[9:37 am] Dimerix's first patient has completed four years of continuous treatment across its DMX-200 kidney disease program, adding to the long-term safety and efficacy data for the FSGS candidate.
First patient completes four years, made up of the two-year blinded ACTION3 Phase 3 trial and the two-year open label extension
Over 90% of eligible patients who completed ACTION3 have elected to continue into the open label extension
Open label completers will be offered continued access through a post-trial access scheme, pending ethics approval
ACTION3 Phase 3 trial remains ongoing, with the adult cohort fully recruited
Company page: Dimerix (DXB)
Ingenia opens books to Warburg Pincus
[9:19 am] Ingenia has agreed to grant Warburg Pincus initial due diligence on its $5.25 cash per security proposal, while keeping its Peet acquisition on track.
Initial due diligence granted on a non-exclusive basis, subject to agreeing a confidentiality arrangement
$5.25 cash per security proposal via a scheme of arrangement, less any distributions paid before implementation, is a 10% premium to Friday's close of $4.78
Board has not determined the proposal is a superior proposal under the Peet scheme deed and has not indicated it intends to recommend it
Peet acquisition continues to progress in line with the scheme implementation deed signed on 26 August
Company page: Ingenia Communities (INA)
Metrics Master Income Trust audit reveals freeze on underlying fund redemptions
[9:15 am] Metrics Master Income Trust's audited FY26 accounts received an unqualified opinion from KPMG, but show a $47 million revaluation hit and a halt to applications and redemptions across its underlying loan funds. The stock has been halted since Monday, 28 September and set to resume trading today.
Net fair value loss of $47.1m vs $0.8m in FY25, with the $2.35bn investment reclassified to Level 3 (unobservable inputs) from Level 2
Net profit down 15% to $144.9m
FY26 distributions of 15.69cpu vs 15.77cpu, with $191.9m paid out exceeding profit of $144.9m
NTA per unit down 2% to $1.9617 from $2.0000
Underlying funds have temporarily ceased accepting applications and redemptions since year end, so the trust cannot redeem units while the halt is in place
Monthly distribution cut to 1.30cpu for September from 1.46cpu in August
Company page: Metrics Master Income Trust (MXT)
CSL pays US$355m upfront for rare kidney disease drug
[9:13 am] CSL has struck a co-development deal with Alentis Therapeutics for lixudebart, a potential first-in-class treatment for rare kidney and liver diseases.
Upfront payment of US$355m to Alentis, with up to US$1.2bn more in commercial milestone payments
CSL to fully fund the Phase 2 RENAL trial, a planned Phase 3 in AAV-RPGN, and Phase 2 trials in FSGS and PSC, a liver disease with no current therapy
Global profits split 55% to CSL and 45% to Alentis once commercialised
Lixudebart is in Phase 2 for AAV-RPGN, a rare autoimmune disease that can cause end-stage kidney disease, and targets both inflammation and fibrosis
R&D head Bill Mezzanotte said the deal reflects CSL's commitment to "building a leading global nephrology franchise" through high-value external partnerships
Company page: CSL (CSL)
Capricorn lifts Q1 output to 31koz as Karlawinda expansion completed
[9:12 am] Capricorn delivered a steady September quarter at Karlawinda, with the newly commissioned expansion set to lift production from Q2 onwards.
Gold production up 3% to 31,218 ounces quarter-on-quarter, in line with the FY27 mine plan
Head grade up to 0.94g/t from 0.91g/t, with recovery improving to 91.7% from 91.2%
Cash and gold up 6% to $535.0m, after a $62.2m underlying cash build (down 9%) and $42.7m in capex
Karlawinda Expansion Project completed on schedule and budget, lifting capacity to 6.5Mtpa and expected production to 150,000ozpa
Mt Gibson secured federal EPBC approval, with the WA Part IV public review closed and Part V approvals progressing
FY27 guidance reaffirmed at 137,000 to 147,000oz at an AISC of $1,900 to $2,100/oz
Company page: Capricorn Metals (CMM)
HealthCo reinstates distributions after re-leasing Healthscope hospitals
[8:59 am] HealthCo has resolved its Healthscope exposure by re-leasing the remaining hospitals to three new operators, clearing the way for distributions to resume.
1Q FY27 distribution of 1.5cpu declared, consistent with FY27 guidance of 6.0cpu
Remaining 10 Healthscope hospitals re-leased to Healthe Care (VIC), Acurio (NSW) and KnG Group (QLD), with transition targeted by 30 November
20-year leases with face rents maintained, annual escalations at CPI or +3% and a ~12% incentive funded from existing liquidity
Largest tenant concentration down to 31% from 57%
Portfolio WALE up 2.9 years to 13.5 years, with the $1.35bn valuation expected to remain stable
Board evaluating a range of strategic and capital management initiatives aimed at maximising unitholder value
Company page: HealthCo Healthcare & Wellness REIT (HCW)
Brightstar hits 167m @ 2.07g/t gold at Bull Oak
[8:56 am] Infill drilling at Brightstar's Bull Oak deposit has returned thick, high-grade intercepts that will feed into an upcoming resource update for its 3.6Moz Sandstone Gold Project.
167m @ 2.07g/t Au from 104m in BORC26042, including 10m @ 25.0g/t from 120m
14.5m @ 10.8g/t Au from 300m in BODD26010, including 0.5m @ 265g/t
14m @ 9.13g/t Au from 209m in BORC26045, within a broader 124m @ 1.45g/t
Bull Oak resource of 10.5Mt @ 1.0g/t for 322koz, up ~4x since acquisition and open at depth
Infill program aims to upgrade the resource to Indicated for the Pre-Feasibility Study, with Bull Oak assessed as a significant open pit operation
Company page: Brightstar Resources (BTR)
Turners Automotive holds Q1 dividend steady at 7 cps
[8:55 am] Turners Automotive Group has kept its first quarter dividend unchanged from a year earlier.
Q1 FY27 dividend of 7cps fully imputed, in line with 7cps in the prior corresponding period
Record date of 13 October, with payment on 29 October
ASX-listed shares down 1.1% year-to-date, NZX-listed shares down 8.1% year-to-date
ASX-listed Turners shares are extremely illiquid, with daily average volumes (4-week average) sitting at just 380 shares (approx ~$2,600).
Company page: Turners Automotive Group (TRA)
Warburg Pincus closes in on Ingenia due diligence
[8:54 am] Ingenia's board is expected to shortly grant Warburg Pincus limited due diligence after its third bid, bowing to shareholder pressure to engage.
$5.25 per share bid is a 10% premium to Friday's close of $4.78, after earlier offers of $4.75 and $5.05 were rejected
Warburg Pincus has been pushing the board to back its bid over the unpopular $1bn proposal to buy Peet, so far without success
At least 30% of the register reportedly supports Warburg Pincus, despite no formal campaign for votes
HMC Capital, which owns just under 5%, is among shareholders backing the approach
Board recommendation remains unclear, with the bid not yet declared final
Source: AFR
GIC and Ares join race for Rio Tinto's $7bn power assets
[8:53 am] The bidder field for Rio Tinto's Pilbara and Canadian power infrastructure is growing, with Singapore's GIC and Ares Management the latest suitors.
GIC has mandated JPMorgan to prepare a bid for both the Pilbara and Canadian assets, expected to be worth about $7bn combined
Ares Management is working on an indicative offer and is self-advised
Existing bidders include IFM with Macquarie Capital, KKR with RBC, and GIP, which bought BHP's WA power assets for US$2bn last year
Non-binding indicative bids are due mid-October, with Rio yet to decide how large a stake it will retain
Pilbara assets include about 510MW of power plants and transmission, offering stable multi-year revenue that suits debt-funded buyers
Source: AFR
Iran rules out reopening Hormuz as more tankers struck
[8:45 am] Tehran says the Strait of Hormuz will stay shut until its conditions are met, even as its grip on the waterway weakens and a US blockade chokes off its oil revenue.
Two tankers struck over the weekend off Oman and in the Strait of Hormuz, according to UKMTO
Iran's Parliament Speaker Ghalibaf said the strait will not open until Iran's seven conditions under the Islamabad Memorandum are met
Houthis claimed a missile and drone attack on an Aramco facility in Riyadh, which Saudi authorities have not confirmed
Saudi crude exports jumped to about 6.1m barrels a day in September from 3.4m in August, according to Bloomberg tanker tracking
Middle East crude shipments have recovered to 17.5m barrels a day, or 98% of prewar levels, according to JPMorgan
Iran shipped no crude on tankers in September for the first time since the war began, per preliminary Bloomberg estimates
Iranian inflation is almost 90% and the rial has lost about 25% against the US dollar in two months
Third US carrier group is heading to the region, with Trump saying heavier strikes are "possible" after the 3 November midterms
Trump drops diesel export ban threat after G7 reserve release
[8:44 am] G7 nations agreed to release emergency fuel stocks after weeks of US pressure, prompting Trump to shelve a threatened ban on US diesel exports.
Up to 100m barrels of oil and diesel to be released over four months, coordinated by the IEA, with diesel front-loaded in the first 20 days
Trump said "we're not going to be doing the export ban", despite earlier encouraging advisers to support it
US diesel averaged about US$6.40 a gallon on Friday, according to AAA, after topping US$6 for the first time last month
Kpler's Matt Stanley warned that drawing inventories indefinitely while disruption continues risks creating "a much bigger supply problem"
Source: Bloomberg
OPEC+ holds November output targets steady
[8:43 am] Seven core OPEC+ members kept production ceilings unchanged for November, with Gulf output still well below quota due to Iran war disruptions.
Core members pumped 25m bpd in August, up 630,000 bpd from July but still about 5m bpd below prewar February levels
Gulf exports have fluctuated at 60% to 80% of normal levels in recent months
Capacity review to set 2027 quotas has been delayed, with output changes unlikely before next year
UBS's Giovanni Staunovo said output remains well below quota despite rising Hormuz flows, adding "the oil market remains tight"
Source: Reuters
Eurozone inflation jumps to three-year high of 3.8%
[8:43 am] Euro area inflation rose more than expected in September, putting pressure on the ECB ahead of its 29 October meeting.
Headline inflation up to 3.8% from 3.2% in August vs 3.6% ests, the highest since September 2023
Core inflation of 2.5%, in line with ests
Energy inflation of 18.8%, the highest since January 2023
Source: CNBC
Tesla rallies as Q3 deliveries beat ests
[8:42 am] Tesla's third quarter deliveries topped ests despite weakness in China and the US, with shares closing 4.7% higher at US$370.59.
Deliveries down 2% to 486,532 vs 463,000 ests (5% beat)
Production of 464,391 vehicles
Energy storage deployments of 13.7 GWh, with William Blair expecting deployment growth to accelerate into the second half
China domestic retail sales estimated down 21% year-on-year in July to August, offset by a 92% jump in exports, according to JPMorgan
US payrolls miss takes October Fed hike off the table
[8:41 am] US employers added just 29,000 jobs in September, prompting traders to push back the timing of the Fed's next rate hike to December.
Nonfarm payrolls of 29,000 vs 90,000 ests, with July and August revised lower by a combined 60,000
Unemployment rate up to 4.2% from 4.1%, driven by new workforce entrants rather than a rise in layoffs
Average hourly earnings up 0.1% month-on-month and 3% year-on-year, below the Fed's preferred inflation gauge of 3.4%
October hike odds below 25% according to swaps, down from about 70% on Monday before NY Fed President Williams flagged "no need for urgency"
JPMorgan's Michael Feroli said "it would now take a very strong CPI to make the October meeting live" and still expects a December hike
TD Securities now forecasts hikes in December and March, rather than October and January
Source: Bloomberg
Treasury yields rebound after jobs data as Europe contagion fears build
[8:39 am] Treasuries erased their post-payrolls rally to close higher on Friday, while traders turned their attention to signs of contagion across euro-area bond markets.
US 10-year yield hit 5.34% this week, the highest since 2002, before closing at 5.28% on Friday
Two-year yield fell as much as 10 basis points after the jobs data before closing four basis points higher near 4.84%
Treasury Secretary Bessent said the rise in yields was in line with global trends and not an idiosyncratic US selloff
French, Italian, Belgian and Greek bonds posted some of their biggest spread moves in years on Thursday as Germany drew haven demand
ECB pricing pared to three hikes by end-2027 from four earlier in the week, with Citi flagging a possible pause to quantitative tightening
UK 30-year gilt yield hit 6% for the first time since 1998
Good morning!
[8:28 am] ASX 200 futures are up 26 pts (+0.29%). Here's what happened overnight:
A weak September payrolls print took an October Fed hike off the table, with tech leading and the Nasdaq scoring an intraday all-time high
S&P 500 (+0.73%), Equal-weight S&P 500 (+0.35%)
Nasdaq (+1.19%), up as much as 1.79% intraday
Dow (+0.49%), Russell 2000 (+0.94%)
Iran hardened its stance on Hormuz over the weekend as more tankers were struck and Washington sent a third carrier to the region
Oil supply relief came from two fronts as the G7 agreed to tap 100 million barrels of reserves and OPEC+ held November output steady