ASX 200 Live Today - Monday, 28th September
The S&P/ASX 200 is set for a flattish open after Trump rejected Iran's Hormuz deal over the weekend. Here are today's top stories.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Monday, September 28. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
Defensives lift ASX 200 as small caps slide
[2:30 pm] That's a wrap! The ASX 200 is up 30 points (+0.35%) and trading near session highs, with defensive sectors doing the heavy lifting. Healthcare and Financials, both up around 0.4% in early trade, have extended their gains to more than 1%. Utilities opened flat and is now also up more than 1%, while Staples has reversed a 0.4% early loss into a 0.4% gain. The main offset is Materials, where small early gains have flipped into a 0.8% decline.
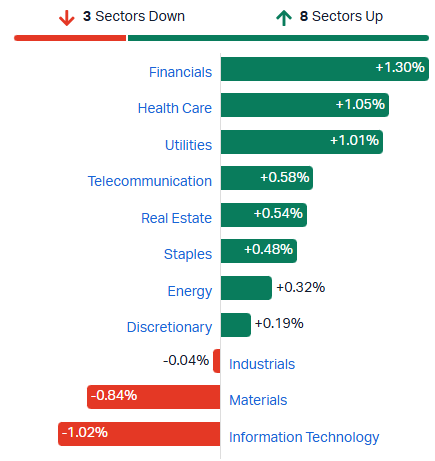
S&P/ASX 200 sectors (Source: Market Index)
Commodities are under pressure, notably:
Gold down 2.0% to US$4,198/oz
Copper down 1.55% to US$6.70/lb
Aluminium down 0.6% to US$3,240/t
The backdrop is bearish for commodities. China's industrial profit growth slowed to 4.2% year on year in August from 11.2% in July, as strength in AI-linked tech manufacturing was outweighed by weak domestic demand. Meanwhile, Brent is up 1.3% to US$103.20 a barrel, global bond yields have rebounded after Friday's slight pullback and the US dollar index is edging higher. That's everything that tends to weigh on commodities moving in the wrong direction.
Overall, not much has changed, with oil and yields still trading at uncomfortable levels. Large cap banks and healthcare names are catching a bid, but the Small Ords and Emerging Companies indices are down 1.3% and 2.3% respectively. The market remains bifurcated at best. All eyes turn to tomorrow's RBA decision, where a 25 bp hike to 4.60% is widely expected.
Australia's FY26 budget deficit comes in better than expected
[2:20 pm] Australia posted a final FY26 budget deficit of $22.3 billion, beating earlier forecasts on the back of lower spending and stronger tax receipts.
Deficit of $22.3bn or about 0.8% of GDP, smaller than the $28.3bn forecast earlier this year
Wider than FY25's $10bn deficit which ended two consecutive years of surpluses
Improvement driven by lower payments across welfare programs and stronger tax receipts from businesses and superannuation fund investment income
Chalmers warns that budget pressures are intensifying rather than easing, despite the better-than-expected result
FY27 deficit forecast at $31.5bn earlier in the year, though the outlook has darkened as the global bond selloff pushes up government borrowing costs
Global funds end four-year underweight on China
[2:19 pm] Global fund managers have stopped cutting their exposure to Chinese stocks, drawn in by AI prospects and cheap valuations.
Active long-only funds moved to benchmark neutral on China from June, ending a four-year underweight, according to BofA's analysis of nearly 2,800 global funds with US$562bn in Chinese stocks
ETF flows stabilising as China and Hong Kong-focused ETFs drew US$19m in August after US$1.94bn of outflows in July, according to Bloomberg Intelligence
MSCI China trading at 10.2x 12-month forward earnings, below its 10-year average of 11.7x
Shanghai-listed first-half net income up 17.6% led by tech hardware and new-economy names, while property and consumer lagged
Recovery still uneven with the CSI 300 down about 11% this quarter, as HSBC favours hardware tech and biopharma over consumer and real estate
Source: Bloomberg
MRE cuts NTA by 12% after audit review
[1:36 pm] The Metrics Real Estate Multi-Strategy Fund will report a 12% lower NTA than it flagged in August, after KPMG's audit put more weight on downside scenarios for its unlisted property investments.
Audited NTA of $2.22 per unit down 31c, or 12.16%, from the $2.53 in the unaudited Appendix 4E, with the audited report due on 30 September
Fair value down 30c per unit (11.68% of NTA) on unlisted CRE equity and equity-like investments, reflecting revised cash flows, cap rates, development timeframes and costs
Credit provisions up 1c per unit with individually assessed provisions accounting for 0.43% of NTA and collective provisions 0.06%
Units at a 24% discount to audited NTA, based on the pre-announcement close of $1.68
Watchlist unchanged at 3.5% of the Passive Trust look-through portfolio, with an unmodified audit opinion expected
Fee impact under review by the responsible entity and Metrics, with further announcements to follow if required
Company page: Metrics Real Estate Multi-Strategy Fund (MRE)
MXT trims NTA by 2% after audit review
[1:35 pm] The Metrics Master Income Trust will report a slightly lower NTA than it flagged in August, after KPMG's audit led to higher credit loss provisions on loan exposures.
Audited NTA of $1.96 per unit down 4c, or 1.99%, from the $2.00 in the unaudited Appendix 4E, with the audited report due on 30 September
Individually assessed provisions up 4c per unit (2.00% of NTA), reflecting a more risk-weighted view of interest rates, macro conditions and heightened regulatory expectations
Other adjustments broadly offset as a 0.07% fall in collective provisions was largely cancelled out by a 0.06% prior period adjustment for capital raising costs
Units at an 11% discount to audited NTA, based on the pre-announcement close of $1.76
Watchlist unchanged at 3.9% of the look-through portfolio, with an unmodified audit opinion expected
Fee impact under review by the responsible entity and Metrics, with further announcements to follow if required
Company page: Metrics Master Income Trust (MXT)
Copper and gold dip as yields, US dollar and oil rise
[12:52 pm] Copper is down 1.67% to US$6.69/lb, extending its pullback from last Tuesday's record of US$6.95/lb to 3.3% and weighing on copper names across the board.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
AIS | Aeris Resources | -3.6% | $0.48 | -3.6% | -20.5% |
CYM | Cyprium Metals | -2.2% | $0.46 | -7.1% | -14.0% |
CSC | Capstone Copper | -2.1% | $14.19 | -1.3% | -6.4% |
29M | 29Metals | -2.1% | $0.37 | 0.5% | -29.4% |
KAN | Kantra Copper | -1.9% | $1.17 | 0.2% | 62.1% |
HCH | Hot Chili | -1.9% | $1.57 | 3.3% | 12.6% |
FFM | Firefly Metals | -1.6% | $1.69 | -3.9% | -17.9% |
AR1 | Austral Resources Australia | -1.3% | $0.08 | 2.6% | 38.6% |
SFR | Sandfire Resources | -1.0% | $22.15 | 2.2% | 23.3% |
RIO | Rio Tinto | -1.0% | $163.20 | -1.4% | 11.2% |
S32 | South32 | -0.9% | $4.92 | -0.3% | 38.5% |
MC2 | Marimaca Copper | -0.6% | $8.44 | -2.8% | -32.5% |
BHP | BHP Group | -0.6% | $60.37 | -0.4% | 32.6% |
Gold is under even heavier pressure, down 2.0% to US$4,197/oz. That's its lowest level since 5 August and leaves the precious metal 10% below its 25 August peak.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
MEK | Meeka Metals | -6.0% | $0.09 | -21.7% | -65.2% |
RSG | Resolute Mining | -4.5% | $1.17 | -2.9% | -4.9% |
AMI | Aurelia Metals | -4.4% | $0.50 | 3.5% | 104.9% |
OBM | Ora Banda Mining | -3.9% | $1.49 | -2.9% | -2.9% |
GMD | Genesis Minerals | -3.7% | $7.37 | -2.2% | 2.9% |
VAU | Vault Minerals | -3.6% | $6.12 | -2.4% | 12.5% |
BC8 | Black Cat Syndicate | -3.0% | $0.98 | -5.3% | -19.8% |
CYL | Catalyst Metals | -2.6% | $5.74 | -16.3% | -22.3% |
BGL | Bellevue Gold | -2.5% | $1.56 | -2.2% | -8.0% |
PNR | Pantoro Gold | -2.4% | $2.87 | 2.9% | -41.4% |
RMS | Ramelius Resources | -2.3% | $3.78 | 5.6% | -7.6% |
CMM | Capricorn Metals | -2.0% | $15.09 | -0.1% | 7.8% |
RRL | Regis Resources | -1.7% | $7.59 | -2.1% | 0.9% |
WGX | Westgold Resources | -1.6% | $5.37 | -2.7% | -14.8% |
NEM | Newmont | -1.6% | $168.26 | -3.0% | 12.1% |
ALK | Alkane Resources | -1.5% | $1.87 | -4.3% | 40.4% |
EVN | Evolution Mining | -1.4% | $13.52 | -1.1% | 7.5% |
EMR | Emerald Resources | -1.2% | $6.87 | -2.9% | 9.3% |
PRU | Perseus Mining | -1.1% | $6.56 | 1.4% | 19.1% |
SBM | St. Barbara | 1.2% | $0.83 | -9.8% | 44.3% |
NST | Northern Star Resources | 7.8% | $23.83 | 8.8% | -3.0% |
Morgan Stanley stays cautious on iron ore as China's K-shaped economy deepens
[12:50 pm] Morgan Stanley says strong exports are masking weaker domestic demand in China, keeping the broker cautious on iron ore but positive on coal and base metals.
China 3Q GDP tracking 4.3-4.4% with export-led production strong but investment and consumption weak, while Beijing has begun deploying part of its Rmb800bn policy financing instrument
August industrial production up 5.2% (July 4.5%), with the PMI at 49.8 (July 49.2) and CPI at 0.8% (July 0.5%)
New property starts down 30.5% in August and floor area sold down 15.4%, with fixed asset investment down 11.0% as home prices soften
Steel exports up 7% to 10.2Mt while crude steel output fell 3.7% and apparent consumption fell 5.6%, though iron ore imports rose 3% to 109Mt
Cautious on iron ore as elevated freight props up CFR prices but squeezes miner netbacks, with a preference order of BHP (OW), RIO (UW), FMG (UW) and DRR (UW)
Overweight WHC and S32 on met coal supply constraints and Hermosa and Sierra Gorda growth, while in lithium PLS (EW) is preferred over IGO (EW) on inventory and ESS cap sentiment
Treasury selloff resumes as oil climbs
[12:46 pm] US Treasuries extended their slide on Monday as oil edged higher after Trump rejected Iran's latest proposal to reopen the Strait of Hormuz, stoking inflation concerns.
US two-year yield up 5 bps to 4.90% while the 10-year rose 4 bps to 5.20%, building on last week's surge to multiyear highs across the curve
Selloff spreads to Japanese and Australian government bonds
Brent up 0.8% to US$102.69 in early Asian trade after Iran refused to soften its Hormuz conditions, adding pressure on the Fed to keep hiking
Westpac's head of fixed income research Damien McColough pointed to ongoing hawkish Fed messaging and oil above US$100 as the key drivers of the bearish momentum
Bessent urges Fed to keep an "open mind" on rates, arguing that AI productivity gains and deregulation will help keep US inflation in check
Source: Bloomberg
Top ASX 200 gainers
[11:27 am] Both Northern Star and Ingenia top the leaderboard on takeover news, with Northern Star rejecting a $27.00 bid from Gold Fields and Ingenia's bidding war heading up, with the offer raised to $5.25 per share, from earlier bids of $5.05 and $4.75.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
NST | Northern Star Resources | 8.7% | $24.0 | 9.7% | -2.2% |
INA | Ingenia Communities Group | 8.2% | $4.9 | 10.7% | -6.3% |
NEC | Nine Entertainment | 3.8% | $0.7 | -10.5% | -38.7% |
A2M | A2 Milk Company | 3.2% | $6.9 | 3.6% | -25.4% |
BXB | Brambles | 2.2% | $19.0 | 1.1% | -17.6% |
TLX | Telix Pharmaceuticals | 2.2% | $16.3 | -5.0% | 44.4% |
WTC | Wisetech Global | 2.0% | $32.0 | 0.2% | -53.3% |
ORI | Orica | 1.9% | $23.3 | 3.1% | -4.0% |
GQG | GQG Partners | 1.8% | $1.1 | 3.7% | -36.6% |
SOL | Soul Patts | 1.8% | $47.3 | 5.3% | 27.2% |
Top ASX 200 losers
[11:27 am] Karoon is top of the losers after downgrading production guidance again after a cable fault at its Baúna, while gold miners including Minerals 260, Genesis, Ora Banda and Vault trade lower after a 1.5% slide in the gold price to US$4219.2/oz in early trade.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
KAR | Karoon Energy | -12.5% | $1.6 | 9.7% | -2.2% |
MI6 | Minerals 260 | -5.9% | $0.9 | 10.7% | -6.3% |
EOS | Electro Optic Systems | -5.8% | $10.7 | -10.5% | -38.7% |
VUL | Vulcan Energy Resources | -4.5% | $1.9 | 3.6% | -25.4% |
MSB | Mesoblast | -3.2% | $2.1 | 1.1% | -17.6% |
ALX | Atlas Arteria | -2.8% | $3.8 | -5.0% | 44.4% |
MP1 | Megaport | -2.3% | $19.2 | 0.2% | -53.3% |
GMD | Genesis Minerals | -2.3% | $7.5 | 3.1% | -4.0% |
OBM | Ora Banda Mining | -2.3% | $1.5 | 3.7% | -36.6% |
VAU | Vault Minerals | -2.2% | $6.2 | 5.3% | 27.2% |
ASX 200 edges higher
[10:49 am] The ASX 200 is up 21 points (+0.24%) in early trade, recovering slightly after Friday's close at its lowest level since 12 June. There's a defensive tilt to sector performance, with Healthcare, Financials, Utilities and Real Estate leading gains, while Materials is also modestly higher after a small decline on Friday. The large caps are holding up relatively well, with the ASX 20 and ASX 50 outperforming, but the small end of town is lagging, as the Small Ords and Emerging Companies indices both trade around 0.5% lower. Elsewhere, the Aussie 10-year yield is up 2 bps to 5.40%, still hovering at its highest level since May 2011.
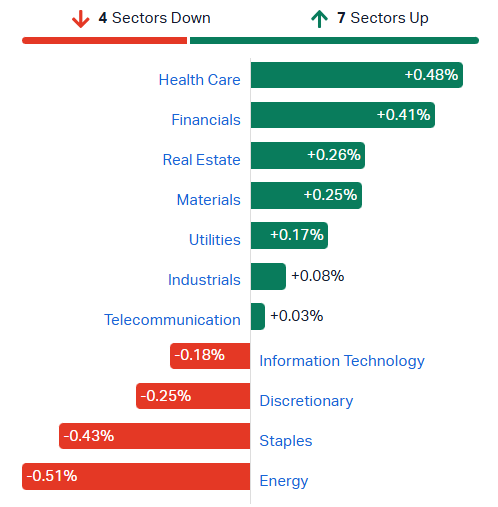
S&P/ASX 200 sectors (Source: Market Index)
Oil rises as Iran holds firm on Hormuz
[10:48 am] Oil climbed after Iran refused to soften its conditions for reopening the Strait of Hormuz, following President Trump's rejection of its proposal.
Trump says Iran has overplayed its hand and told Axios that Washington might have accepted Tehran's terms a year ago, though he expects talks to resume this week
Gains likely muted according to DBS energy research head Suvro Sarkar, who says the market wasn't expecting the strait to reopen within a week
Iranian supply to China winding down with Treasury Secretary Bessent saying final deliveries are likely within two weeks and only about 15m barrels remain on the water
Brent up about 75% this year as the conflict enters its eighth month, with Trump also weighing curbs on US diesel exports as diesel prices hit records
Regional tensions elevated after Saudi-led coalition forces intercepted Houthi drones headed for Riyadh, with alerts issued at Aramco-linked sites in Abha and Jazan
Source: Bloomberg
US yield curve edges toward inversion
[10:47 am] The US 2s10s Treasury curve has flattened to its narrowest since early 2025 as Fed rate hikes shift the market's focus toward the risk of a stalling economy.
2s10s spread narrowed to 17bp last week, with the two-year and 10-year starting this week at about 4.9% and 5.2%, and the 10-year near its highest since 2007
Fed hiked in September for the first time in three years and flagged more to come, with traders pricing at least three quarter-point hikes over the next year
Views split on inversion with TD Securities expecting the curve to steepen as hikes are already priced, while Columbia Threadneedle is positioning for 2s10s and 5s30s inversion within six months
Inversion has preceded the last eight recessions with a lead time of about 15 months on average since 1978, though the 2022 inversion proved a false alarm
Bank stocks under pressure as the KBW Bank Index fell into a technical correction, down 10% from its recent highs, with a flatter curve squeezing net interest margins
Policy mistake risk flagged by TCW's Jamie Patton, who says an inversion would signal the Fed is hiking too far and will need to cut hard later
Source: Bloomberg
Metrics funds suspended ahead of material audit changes
[10:14 am] Metrics Master Income Trust has entered a voluntary suspension after warning its audited FY26 accounts will differ materially from the preliminary result, with two sister funds also paused.
MXT suspension requested by responsible entity The Trust Company (RE Services), pending the audited FY26 financial report expected on 30 September
Material differences expected versus the unaudited Appendix 4E released on 31 August, which was prepared using information from manager Metrics Credit Partners
Disorderly trading risk cited by the responsible entity, with the suspension to remain in place until the final report is released
MOT and MRE also paused with the Metrics Income Opportunities Trust and Metrics Real Estate Multi-Strategy Fund in a temporary trading pause pending a further announcement
Pinnacle owns about 35% of Metrics' holding company, which contributed about $12.6m, or 7%, of Pinnacle's FY26 NPAT of $176.7m
Pinnacle shares are down 3.7% to $12.68 at the time of writing.
Edit: Pinnacle was briefly suspended, and resumed trading at 10:21 am. The stock is currently down 6.9% to $12.32.
Company pages: Metrics Master Income Trust (MXT), Metrics Income Opportunities Trust (MOT), Metrics Real Estate Multi-Strategy Fund (MRE), Pinnacle Investment Management (PNI)
US government backs Dateline bid to restart Colosseum
[9:49 am] The US Department of Justice has filed its own motion to lift the injunction halting Dateline's Colosseum project, backed by a Department of War declaration citing national security.
Dateline is developing the Colosseum gold and rare earths project in California, located near MP Materials' Mountain Pass mine and processing facility
Stay motion filed by the DOJ on 25 September to suspend the 10 August preliminary injunction pending appeal, asking that operations resume under the approved Plan of Operations
Government argues it will win on appeal, saying the court erred in finding the "valid existing rights" clause of the California Desert Protection Act does not protect an approved Plan of Operations
Department of War declaration says continued rare earths exploration at Colosseum is in the US national security interest given overreliance on foreign supply
Hearing set for 26 October before Judge Snyder, with the Ninth Circuit an option if a stay is refused, while the National Parks Conservation Association opposes both motions
Appeal already lodged with the Ninth Circuit on 22 September by both the Government and Dateline
Company page: Dateline Resources (DTR)
OD6 joins US defence industrial base consortium
[9:48 am] OD6 Metals has been accepted into the US Defense Industrial Base Consortium (DIBC), opening a pathway to US Government critical minerals funding for its Nevada fluorspar project.
OD6 is an explorer advancing the Quinn Fluorspar Project in Nevada, with current work focused on permitting, exploration and metallurgical testwork
DIBC membership gives OD6 a pathway to US Government funding opportunities and partnerships across government, industry and academia
Strategic and Critical Materials is a specifically identified DIBC sector covering mining, refining and processing, and the DIBC has dedicated solicitations for domestic critical mineral processing
US 100% net import reliant on fluorspar, underscoring the strategic case for new domestic supply
Builds on SAM.gov registration which the company already holds, further positioning Quinn for US Government funding and supply chain engagement
Company page: OD6 Metals (OD6)
Synlait swings to 2H profit as operations stabilise
[9:44 am] Synlait's operational recovery lifted second-half earnings back into the black, though a weak first half still left the dairy processor with a reported FY26 loss.
NZX-listed Synlait shares are up 8.7% to NZ$0.43 at the time of writing.
Revenue of NZ$1.94bn with gross profit of NZ$37.7m
Underlying EBITDA of NZ$46.3m with reported EBITDA of NZ$8.1m, both slightly outside the August guidance range after milk price finalisation
Underlying net loss of NZ$21.6m with a reported net loss of NZ$75.4m
Second half turnaround with reported EBITDA swinging from a NZ$34.7m 1H loss to NZ$42.8m, and NPAT from a NZ$80.6m loss to a NZ$5.2m profit
Manufactured in spec lifted from 91% in 1H to 95% in 2H and averaged 99% in August, with plan attainment up from 90% to 103%
Net debt of NZ$215m
Final 2025/26 base milk price of NZ$9.69/kgMS the second highest in Synlait's history, with a 2026/27 forecast of NZ$9.50/kgMS
Company page: Synlait Milk (SM1)
Karoon cuts 2026 production guidance after SPS-92 cable fault
[9:39 am] A newly installed downhole cable has failed at the SPS-92 well at Baúna, forcing a rig-based repair and a cut to full year production guidance.
Baúna 2026 production guidance cut to 5.4–5.7 MMbbl from 6.0–6.7 MMbbl, a 13% reduction at the midpoint
Total CY26 production guidance cut to 6.6–7.2 MMboe from 7.2–8.2 MMboe, a 10% reduction at the midpoint, with Who Dat guidance unchanged
Unit production cost guidance raised to US$15–16/boe from US$12–15/boe on lower output against a fixed cost base
Production deferral of approximately 3,500 bopd until the faulty cable system is replaced via a rig-based intervention
Insurance recovery may partially offset lost production revenue and reimburse substantially all repair costs, subject to policy terms and insurer confirmation
Karoon's revised guidance midpoints sit 10% below Macquarie's (14-Sep) estimate of 7.7MMboe
The last time Karoon announced a major production downgrade, on 16 June, its shares fell as much as 15% on the day and a further 13.3% the next day to $1.42. The company cut CY26 production guidance to 7.2–8.2 MMboe from 8.1–9.2 MMboe after repair delays at the Who Dat E manifold in the US Gulf of Mexico pushed its return to service out to the second half of 2027. Macquarie downgraded Karoon to Underperform and cut its price target 25% to $1.50.
St Barbara lifts 15-Mile reserve 17% as NPV jumps 21%
[9:24 am] St Barbara's updated PFS for its 15-Mile Processing Hub in Nova Scotia delivers a bigger reserve, longer mine life and stronger economics for broadly unchanged capex.
Ore Reserve up 17% to 1.44Moz at a US$2,000/oz reserve price, with mine life extended to 13 years based on Proved and Probable reserves alone
LOM production up 203koz to 1.4Moz averaging 106koz a year and peaking above 120koz in FY31 and FY32
Initial capex of C$289m ($315m) broadly in line with C$283m in the previous PFS, funded from $427m cash, Touquoy cashflow and, if needed, the $453m Simberi sale
LOM AISC of US$1,098/oz ($1,685/oz) underpinned by a low 2.8:1 strip ratio, free-milling ores and costs shared across three mining areas
Post-tax NPV5 of $1,705m and IRR of 81.6% at US$3,000/oz, rising to $2,721m and 121.4% at US$4,000/oz
Feasibility Study brought forward to the March quarter FY27 (previously June quarter), with FID still targeted for the June quarter FY27
Company page: St Barbara (SBM)
St Barbara targets underground upside at Old Austen
[9:24 am] St Barbara is prioritising drill testing of high-grade mineralisation below the Old Austen open pit reserve, flagging further resource growth potential at 15-Mile.
Drilling planned for the June quarter FY27 to September quarter FY28, targeting the Old Austen Down-Plunge and Mill Shaft West prospects
Mineralisation left outside the pit after the Old Austen pit depth was constrained to limit surface disturbance and maintain setbacks from waterways
Historic intercepts confirmed include 1.84m @ 163.7g/t Au from 123.6m, 3.70m @ 66.1g/t Au from 298.4m and 1.89m @ 50.1g/t Au from 141.7m
High-grade domain of ≥30 gram-metres has an interpreted down-plunge extent of about 450m and remains open
UAV magnetic survey across 22km² to be completed in early October, with a structural review in H2 FY27 to refine drill targets
Company page: St Barbara (SBM)
Capral steps up buy-back pace
[9:23 am] Capral will sharply lift the rate of its on-market buy-back through to mid-December, a move that points to confidence in its balance sheet and to the Board seeing value at current prices.
Buy-back rate lifted with Capral now targeting 40% to 50% of shares traded over the preceding 20 business days, running through to 17 December 2026
Volume cap of 60% of that measured trading applies, other than for a single large parcel, and daily purchases may run higher or lower than the target range
Existing terms unchanged with the buy-back, first announced on 2 March 2026, still capped at 10% of issued shares in any 12-month period and no change to its duration
Purchases remain on market at prevailing prices under ASX Listing Rule 7.33, with timing and volume left to Capral's broker based on market conditions
Board retains discretion over whether the buy-back continues and how quickly shares are bought
Company page: Capral (CAA)
Nufarm details 'Evolving Ag' strategy at investor day
[9:12 am] Nufarm used a two-day investor event to outline a shift toward a narrower, higher-returning portfolio in crop protection and seed technologies, while reaffirming previously flagged FY26 guidance.
FY26 underlying EBITDA guidance reaffirmed at $370–380m, as flagged on 23 September 2026
Group revenue tracking around $3bn under that guidance, across 3,100 employees
Crop protection delivered a 4% revenue CAGR and 6% underlying EBITDA CAGR over FY20 to FY25
Seed Technologies generated FY25 revenue of $252m from seeds and $84m from renewable oils
Portfolio focus narrows crop protection investment to three crop systems, cereals, soybean and trees/nuts/vines, representing 46% of the US$80bn global market
Nufarm reaffirmed its FY26 underlying EBITDA guidance on 23 September, but the stock still fell 6.2% to $3.00 on the day. The guidance sat below the $384m consensus, a disappointment for a stock that had already rallied 37% year to date heading into the update. Macquarie trimmed its price target 3.3% to $2.90. The broker expects earnings growth to slow into FY27 as crop protection headwinds persist and Seeds laps a higher base, particularly in its emerging platforms. It also noted the stock had run hard since the May result, in line with the broader agriculture sector rally.
Company page: Nufarm (NUF)
Orica secures FY27 North American supply, delays Deer Park land sale
[9:12 am] Orica has locked in FY27 ammonium nitrate supply for its North American customers and does not expect a material margin hit, while pushing back the timing of its Deer Park land sale.
FY27 supply secured for contracted North American customers from US producers, increased Carseland plant volumes and its global network
Margin impact from higher sourcing costs is not expected to be material in FY27, helped by logistics optimisation and cost-out initiatives
Deer Park land sale contract exchange will extend beyond the previously flagged FY26 timing due to changed market conditions
Management said "the broader business continues to perform strongly, in line with our expectations", with a full FY27 outlook due at November's full year results
Nelson Brothers acquisition in the US has added new manufacturing and supply infrastructure to the North American network
Company page: Orica (ORI)
Northern Star rejects Gold Fields' $38.7bn takeover approach
[9:11 am] Northern Star has confirmed it received and unanimously rejected a confidential, non-binding proposal from Gold Fields that valued the company at $27.00 per share.
Implied offer price of $27.00 per Northern Star share, based on Gold Fields' closing price on 11 September, comprising 0.3125 new Gold Fields shares plus $7.25 cash
Implied equity value of $38.7bn, a 22% premium to Northern Star's closing price and 15% premium to its 30-day VWAP on 11 September
Deal structure would have seen Northern Star shareholders take about 73% of consideration in Gold Fields scrip, holding roughly 33% of the combined entity
Board rejected the proposal as materially undervaluing Northern Star's asset base and being subject to onerous conditions including hard exclusivity and no fiduciary out
Management said "Gold Fields has sought to acquire one of the world's premier gold portfolios at a price that falls well short of what the Board considers to be its fundamental value and at a highly opportunistic time"
Proposal lapsed after Northern Star told Gold Fields on 25 September it would not engage further, with the implied price now reduced to $25.19 based on Gold Fields' latest close
Company page: Northern Star Resources (NST)
Ingenia's Warburg Pincus offer raised to $5.25 per security
[9:05 am] Warburg Pincus has lifted its non-binding takeover proposal for Ingenia Communities for a third time, now conditional on the group ditching its existing Peet Scheme Implementation Deed.
Offer price raised to $5.25 cash per stapled security, up from earlier proposals of $5.05 and $4.75, less any future distributions before implementation
Board response required by 2 October 2026, including confirming in writing an intention to recommend the offer subject to due diligence and an independent expert opinion
Deal requires termination of Ingenia's existing Peet Scheme Implementation Deed before entry into a Warburg Pincus scheme
Due diligence period expected to take 6-8 weeks under an exclusivity arrangement including four weeks of initial hard exclusivity
Other conditions include securing binding acquisition debt finance, final investment committee approval and regulatory sign-off
Board position has not formed a view on the proposal and is making no recommendation to securityholders at this time
Company page: Ingenia Communities Group (INA)
US consumer sentiment sinks to four-month low as inflation fears deepen
[8:41 am] Year-ahead inflation expectations jumped to their highest since June as households grew more anxious about the economic outlook.
University of Michigan Consumer Sentiment fell to 48.1 in September, down 7% from August and a four-month low, though it topped both the 47.8 preliminary estimate and 47.6 consensus
One-year inflation expectations climbed to 4.6% from 4.0% in August, the highest since June and sharply above the 3.4% seen in February before the Iran conflict began
Five-year inflation expectations rose to 3.4%, breaking a three-month run at 3.3% and remaining above the 2.8-3.2% range that held through 2024
The Index of Consumer Expectations dropped 10.1% to 46.3, while Current Economic Conditions eased 1.9% to 50.9
Sentiment deterioration was bipartisan, survey director Joanne Hsu said, with Republican sentiment down 20% and Democrat sentiment down 13% since January
Every one of the index's four worst readings on record has come in the past six months, with an all-time low of 44.8 hit in May
Rising bond market volatility flashes a warning sign for corporate credit
[8:39 am] A historically reliable stress gauge for company debt is climbing even as corporate bonds have so far shrugged off a broader government bond selloff.
The MOVE index, a gauge of Treasury market volatility, surged to about 105bp last week, its highest since March and well above its ~80bp decade average, a signal that has historically preceded trouble for corporate credit
US high-grade spreads held at 77bp Thursday, actually 2bp tighter than the start of the month, even as five-year Treasury yields topped 5% for the first time since 2007
JPMorgan strategists estimate high-grade spreads should be running about 7bp wider than current levels based on historical bond and equity volatility relationships
US companies sold about $33bn of bonds this week, short of a ~$40bn dealer forecast, with some issuers paying ~6bp extra yield and at least one standing down mid-week
The CDX Investment Grade default-protection index rose to about 58bp on a roll-adjusted basis, from ~55bp at end of August
Key data this week: 2 October nonfarm payrolls, forecast at 80,000 jobs versus a 100,000 consensus, and eurozone September inflation, forecast to rise to 3.5% from 3.2%
Source: Bloomberg
RBA tipped for fourth rate hike this year as markets brace for more
[8:38 am] Economists are all but unanimous a rate rise is coming tomorrow, with attention turning to whether the RBA signals further tightening into November.
RBA board is tipped to lift the cash rate 25bp to 4.6% tomorrow, its fourth hike this year and the highest level since November 2011
Markets are pricing a ~90% probability of a hike, with all 29 economists surveyed by Bloomberg, including all four majors, forecasting the move
Most economists expect this to be the final hike for now, though ANZ, HSBC and UBS are tipping a fifth hike in November
Money markets are more aggressive, pricing at least two more hikes and better-than-even odds of a third, which would take the cash rate above 5% by mid-2027
Lenders are already front-running the decision, Macquarie Bank has lifted fixed rates twice in three weeks and 18 lenders have raised at least one fixed rate this month per Canstar
A 25bp hike would add $91 a month to repayments on a $600k loan, with the cumulative hit from four hikes this year reaching $364 a month
US and China extend trade truce with tariff cuts, coal deal from Xi summit
[8:37 am] Xi Jinping's three-day state visit delivered a raft of trade concessions and a truce extension, though decisions on Taiwan and AI risk remain deliberately vague.
US and China agree to cut tariffs on $30bn of goods in each direction, covering categories like agricultural products, timber and cosmetics from the US and toys, appliances and decorations from China
China commits to importing at least 10m tonnes of US coal in 2027, and again in 2028, as part of the wider package
The two countries extend their trade truce by two months to 10 January, a shorter extension than markets had expected, with further talks set for APEC in November and the G20 in December
Washington and Beijing agree to continue AI dialogue with a further round in November and a new incident-communication channel, alongside new working groups on agriculture market access and investment
Neither side's readout mentions Taiwan despite Xi pressing Trump to oppose Taiwan independence, with the US ambassador to China saying Washington's position is unchanged
Both leaders agree no country should impose tolls on international waterways and that Iran should not develop nuclear weapons, an indirect nod to the Hormuz standoff
Trump rejects Iran's Hormuz reopening offer as Houthi strikes hit Riyadh
[8:36 am] Tehran's mediated proposal to reopen the Strait of Hormuz has stalled even as Washington keeps up economic pressure and the conflict's regional spillover intensifies.
Trump says he's rejected Iran's proposal to reopen the Strait of Hormuz, calling it a sign Tehran is losing badly
Iran's foreign ministry says no rejection has been conveyed through official channels yet, with Tehran still awaiting a definitive US response via mediators Qatar and Pakistan
A US official says nearly 40m barrels of oil transited the strait in the past 48 hours under the current blockade, a corridor that carried about 20% of global oil supply before the conflict
Treasury secretary Bessent says China's oil purchases from Iran are set to end within two weeks, adding to economic pressure on Tehran to strike a deal
New US sanctions targeting companies doing business with Iranian airlines aim to ground the country's civil fleet, with Iraq seeking exemptions for humanitarian flights
Houthi forces target Riyadh with drones and a missile over the weekend, intercepted by Saudi-led air defences in the first such alert since March
Akamai shares surge on multi-year cloud deal with Anthropic
[8:35 am] The infrastructure provider locked in a seven-year AI compute commitment that could hand its new partner a meaningful equity stake.
Akamai signed a seven-year, $11.6bn cloud infrastructure agreement to support Anthropic's compute workload requirements
The deal adds to more than $2.8bn in multi-year cloud commitments Akamai had already announced this year
Anthropic received a warrant for non-voting convertible preferred stock representing about 5% of Akamai's shares on an as-converted basis, at a $111.33 exercise price
About 2% of that stake vests against the $11.6bn already committed, with the remaining 3% vesting only if the deal expands by up to a further $9bn, in roughly 1% increments per additional $3bn
Akamai estimates total capex tied to the commitment at about $5.5bn, and expects a $1.7bn increase to 2026 capex to secure supply chain components including memory
The company said it expects no impact to 2026 revenue guidance
Source: Investing.com
Good morning!
[8:31 am] ASX 200 futures are up 3 pts (+0.03%). Here's what happened overnight:
Wall Street closed a volatile week higher, with the S&P 500 and Nasdaq notching weekly gains as the market looked past a bond selloff that lifted the 10-year yield to its highest level since the global financial crisis
Daily: S&P 500 (+0.51%), Nasdaq (+0.48%), Dow (+0.93%) and Russelll 2000 (+0.07%)
Weekly: S&P 500 (+1.21%), Nasdaq (+2.06%), Dow (+0.28%) and Russell 2000 (-0.80%)
Trump rejected Iran's latest Hormuz proposal on the weekend, after negotiators had explored a deal where Tehran reopens the strait and Washington lifts its blockade of Iranian ports
The Trump-Xi summit wrapped with a pledge from China to buy US coal and plans to pursue more favourable tariffs on $30bn of non-sensitive goods from each side