ASX 200 Live Today - Monday, 14th September
The ASX 200 is set to snap a four-day losing streak, US stocks bounced as oil retreats and CPI landed in line. Here are today's top stories.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Monday, September 14. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
ASX 200 back at breakeven
[2:15 pm] The ASX 200 is currently up 4 pts (+0.05%) despite being up as much as 0.31% in early trade. The flattish performance at the index level largely reflects softness across heavyweight names like BHP, Rio Tinto, NAB, Goodman Group and Fortescue.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
BHP | BHP Group | -1.0% | $60.25 | -4.0% | 32.3% |
CBA | Commonwealth Bank | 0.2% | $154.50 | -4.0% | -3.8% |
RIO | Rio Tinto | -0.1% | $168.10 | -4.8% | 14.5% |
NAB | National Australia Bank | -0.3% | $38.62 | -2.4% | -8.6% |
WBC | Westpac | 0.6% | $34.42 | -1.5% | -10.6% |
ANZ | ANZ Group | 0.4% | $37.41 | -1.8% | 2.6% |
MQG | Macquarie Group | 0.1% | $245.39 | -2.6% | 20.9% |
WES | Wesfarmers | -0.1% | $72.78 | -7.7% | -10.2% |
CSL | CSL | 2.4% | $171.15 | -2.1% | -1.4% |
WDS | Woodside Energy Group | 1.0% | $33.19 | 3.6% | 39.8% |
GMG | Goodman Group | -1.6% | $26.49 | -4.0% | -14.6% |
TLS | Telstra Group | 0.4% | $4.85 | 1.0% | -0.4% |
FMG | Fortescue | -0.3% | $16.62 | -4.3% | -24.5% |
WOW | Woolworths Group | 0.8% | $38.82 | -3.0% | 32.2% |
TCL | Transurban Group | -0.2% | $13.69 | -0.5% | -3.9% |
Breadth is relatively positive, with 106 constituents (53%) trading higher and only Tech (-0.36%) and Materials (-0.79%) in the red. Defensives and consumer-facing sectors like Healthcare (+1.3%), Staples (+0.8%), Telcos (+0.45%) and Discretionary (+0.4%) are catching a bid today.
Overall, not a whole lot has changed. Brent has clawed back some of last Friday's pullback, up 3.3% to US$107.79 a barrel. The Aussie 10-year is down 3 bps to 5.35%, though that's cold comfort after a 20 bp surge across the prior three sessions. The policy-sensitive 3-year has slipped 4 bps to 4.98%, following a monster 25 bp move over the prior five.
UBS says rate worries cap the equity outlook down under
[1:44 pm] UBS argues that with inflation fears now dominating, further upside in bond yields threatens to cap the market and favours price makers over price takers.
Australian 10 year yield near 4.4%, the highest since May 2011, with rising oil prices, soft fiscal backdrops and heavy corporate bond issuance driving the back up
RBA expected to hike 25bp this month with the prospect of another 25bp before year end, keeping upward pressure on the short end as well
Equities are now selling off as yields rise, the inverse pattern that forms when inflation rather than deflation fears dominate, and a further move up in long end yields threatens both index upside and a profit outlook already showing broad based downgrades through the August reporting season
Mining and Energy preferred as late cycle capacity constraints favour price makers, while consumer and housing related names face intensifying debt servicing, affordability and cost of living headwinds
Energy is the only sector with a visible positive correlation to higher policy rates on three years of weekly data, with Real Estate and Consumer Discretionary the most negatively impacted
Stockland, Mirvac, Wesfarmers, JB Hi-Fi and Seek flagged as likely underperformers on rising policy rate concerns, while Transurban, APA, Wesfarmers and CBA screen as most exposed to higher long end yields given high PEs and long duration
Funds bet New Zealand bonds keep beating global peers
[1:42 pm] Investors are buying New Zealand debt on the view that sluggish growth will keep the RBNZ cautious, extending an outperformance that has already left the market ahead of most major peers this year.
A Bloomberg gauge of NZ bonds was down 0.3% for the year as of Friday's close, against losses of more than 1% for Canadian and US debt, almost 3% for UK gilts and more than 4% for Japanese bonds
Insight Investment favours two to five year maturities, with head of global rates Harvey Bradley saying the RBNZ will not deliver the hikes priced and that returns look compelling given a steeper curve than developed market peers
Traders are pricing four more hikes by August next year on top of the two delivered in 2026, after yields jumped to multiyear highs on Friday as the oil rally fuelled October hike wagers
The RBNZ is split on timing, with Assistant Governor Karen Silk saying the next hike may not come until December while board member Prasanna Gai has suggested the policy rate is already at neutral
Second quarter GDP due Thursday is expected to show the economy grew 2.2% year on year before slowing into year end
Source: Bloomberg
Core Lithium surges on no news
[1:38 pm] A very odd session for Core Lithium. The stock is up 15% to 39.5 cents, the highest since October 2023. Chinese lithium futures are trading flattish at 134,380 yuan a tonne, while a lithium bellwether like PLS is current down 2.2%.
The latest market sensitive announcement from Core was from last Friday, where it produced its first lithium spodumene concentrate from its Finniss Lithium Operation.
Approximately 80.4 million shares have traded hands today, well-above its 20-day average of just 27.1 million shares.
Copper slips as hot US inflation lifts Fed hike bets
[12:37 pm] Copper is trading 1.0% lower on Monday to US$6.50/lb, and down 5.3% in the last three sessions.
The spot over 3-month copper premium narrowed to US$4.50 a ton, down sharply in recent weeks and a signal that prompt supply tightness is easing
The pullback follows last week's record high, driven by bets on US tariffs on refined metal that prompted pre-emptive shipments into America
Last Thursday, Reuters reported that the White House has stalled its decision on imposing new tariffs on refined copper imports due to rising manufacturing costs and consumer affordability concerns. This drove a sharp unwind for copper, with prices down 4.8% on the day
Chevron sees LNG prices staying elevated for six months
[12:33 pm] Chevron's Australia president Balaji Krishnamurthy told Bloomberg TV that LNG prices, which have surged since the start of the US-Iran war, are unlikely to fall in the near term.
Krishnamurthy said he has a hard time seeing prices come down in the next six months or so, speaking on the sidelines of the Gastech conference in Bangkok
Australian LNG is trading at a premium given its geographic proximity to Asia, a read-through for domestic producers as well as Chevron's Gorgon and Wheatstone projects
The loss of Qatari exports is the driver, with the country having previously supplied around a fifth of global LNG
Demand destruction is already showing up in the short term, with a longer-term risk that buyers switch to alternatives to insulate themselves from future supply shocks
Long-term contracting has picked up as energy security moves front of mind, with AI and data centre growth flagged as a key source of future demand, including opportunities in Australia
Source: Bloomberg
China data due Tuesday shapes the stimulus call
[12:32 pm] August activity data out Tuesday is expected to show industrial production rebounding while investment worsens and consumption stays weak, leaving September as the decisive month for further stimulus.
Industrial production forecast up 4.8% year on year, ahead of July's 4.5% gain, with the official manufacturing PMI showing new orders and output both expanding in August and producer prices rising for the first time in three months
Fixed-asset investment expected down 7.1% for the first eight months, worsening from a 6.7% decline over January to July, with the property investment contraction likely deepening beyond 20%
Retail sales forecast up just 0.8%, versus the 3.6% average pace across 2024 to 2025, with passenger vehicle sales down 24% in August, the sharpest fall since February
Bloomberg Economics said stronger government spending flagged by the Politburo in late July did not materialise, and that a buoyant tech sector is failing to cushion the domestic slide
Policy banks have begun deploying funding from a program that can unlock 800 billion yuan (US$119bn) for projects in 2026, up 60% on 2025, which could seed a fresh infrastructure wave in coming months
ANZ economists said September is an important policy window to revive business confidence ahead of October's Golden Week, arguing more fiscal support is needed while a policy rate cut looks unlikely
Source: Bloomberg
Genus wins $160m Victorian battery contract
[12:30 pm] GenusPlus Group has been awarded the balance of plant contract for the 400 MW / 1.86 GWh Birdwood Energy Reserve battery at Wodonga in Victoria.
Contract value of approximately $160m, awarded by an unnamed renewable energy investment manager, with construction scheduled for completion in late 2028
Scope covers balance of plant works including civil, structural and electrical infrastructure, high-voltage connection assets, communications and control systems, plus testing and commissioning
At 400 MW / 1.86 GWh the project sits at the larger end of Australia's BESS pipeline, with a 4.65 hour duration that suits firming rather than short-duration frequency support
Company page: GenusPlus Group (GNP)
ASX 200 bounces but miners extend losses
[11:37 am] The ASX 200 is up 24 pts (+0.28%) in early trade, with consumer-facing sectors like Staples and Discretionary both up more than 1%. Materials is the only sector that has failed to participate, down 1.0% (and now down 6.0% in the last three sessions).
Despite the index trading slightly higher, breadth is still relatively weak, with the ASX Small Ords and ASX Emerging Companies indices down 0.15% and 0.14% respectively.
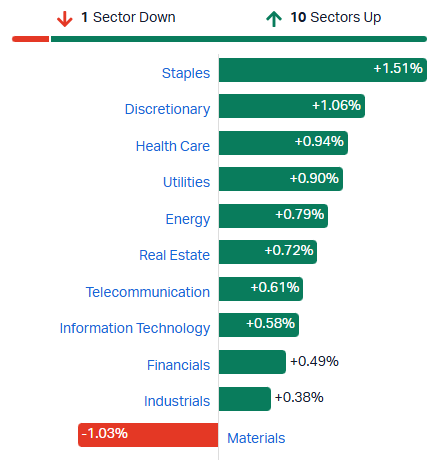
S&P/ASX 200 sectors (Source: Market Index)
Top ASX 200 gainers
[10:50 am] Catalyst Metals tops the leaderboard on a resource upgrade at its Trident deposit, Cleanaway ticks higher as its EQT bid remains ongoing and a few beaten up names like Lovisa, Xero and REA catch a bid.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
CYL | Catalyst Metals | 3.8% | $6.63 | -1.9% | -10.2% |
NEC | Nine Entertainment Co | 3.5% | $0.80 | -12.4% | -28.2% |
CWY | Cleanaway Waste Management | 3.5% | $2.66 | 2.7% | 3.1% |
EOS | Electro Optic Systems | 3.3% | $9.45 | -1.0% | 0.1% |
A2M | A2 Milk Company | 3.1% | $6.86 | 2.6% | -25.5% |
LOV | Lovisa | 3.0% | $22.29 | -3.4% | -24.0% |
XRO | Xero | 2.3% | $68.61 | -12.2% | -39.8% |
REA | REA Group | 2.2% | $157.89 | -4.3% | -14.8% |
ALD | Ampol | 2.2% | $42.13 | 2.2% | 31.9% |
TLX | Telix Pharmaceuticals | 2.2% | $16.01 | -1.2% | 42.3% |
Top ASX 200 losers
[10:50 am] Uranium, lithium and rare earth stocks open broadly lower, while the broader S&P/ASX 200 Materials Index slips 0.55% to the lowest since 5 August.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
PDN | Paladin Energy | -7.1% | $9.56 | -18.3% | -0.8% |
DYL | Deep Yellow | -5.5% | $1.34 | -18.7% | -27.3% |
SLX | Silex Systems | -4.4% | $4.45 | -12.0% | -47.3% |
CNU | Chorus | -4.1% | $6.86 | -6.0% | -16.7% |
NXG | Nexgen Energy | -3.7% | $13.62 | -7.4% | -2.6% |
LYC | Lynas Rare Earths | -3.4% | $13.88 | -8.4% | 11.8% |
MP1 | Megaport | -3.1% | $17.27 | 2.5% | 52.2% |
VUL | Vulcan Energy Resources | -3.0% | $2.30 | -12.5% | -47.8% |
ILU | Iluka Resources | -2.9% | $6.06 | -10.4% | 4.7% |
EVN | Evolution Mining | -2.8% | $13.61 | -9.7% | 8.3% |
Minerals 260 lands $200m Franco-Nevada package
[9:54 am] Franco-Nevada has committed a further $200 million to Minerals 260 to help fund the Bullabulling gold project, lifting its total investment to $420 million.
Franco-Nevada Australia will pay $170m to increase its royalty by 1.45% over the project area, structured as non-dilutive funding for Minerals 260
A further $30m will be subscribed in a future equity raising, with the royalty and equity components together taking total investment to $420m since the initial $220m in February 2026
The commitment is Franco-Nevada's largest ever in Australia and ranks among its ten largest globally, following due diligence on the 6.2Moz resource and the Pre-Feasibility Study
Bullabulling sits 65km from Kalgoorlie in Western Australia and hosts a 6.2Moz gold Mineral Resource
Franco-Nevada will also contribute up to $100,000 a year for three years toward local community, education and environment initiatives
Franco-Nevada CEO Paul Brink said the company is ahead of schedule on project development and financing and has rapidly grown its resource endowment
Company page: Minerals 260 (MI6)
Developing Asia sours on LNG after $7bn spot bill
[9:46 am] The loss of Qatari supply through Hormuz has more than doubled gas costs for emerging Asian buyers and is prompting a structural rethink of the fuel's role in the region.
India, Pakistan, Bangladesh, Thailand and Vietnam have spent US$7.4bn on spot LNG since the war began in late February, against about US$3.1bn for a similar volume under long-term contracts in the same period last year
Qatari shipments through the Strait of Hormuz have all but stopped, stripping out roughly a fifth of global supply and pushing Asian prices to their highest since late 2022
Around 80% of LNG buyers expect to change procurement strategy and prioritise geographical diversification over coming years per a McKinsey survey, lifting the appeal of projects with direct Asian access such as TotalEnergies and Exxon's Papua LNG, which faces an FID later this year
Substitution is already underway, with BNEF expecting Pakistan to lean on solar and hydro, Bangladesh rolling out household solar incentives after spending over US$2bn replacing Qatari volumes, and Vietnam and the Philippines potentially shifting back to coal
47 proposed gas-fired power plants totalling US$52bn have been cancelled, withdrawn or stalled over the past five years across the Philippines, Thailand and Vietnam per IEEFA, against Shell's August forecast for 65% LNG demand growth by 2050
Source: Bloomberg
Drilling wrap: niobium, tungsten, gold and copper hits
[9:45 am] A run of exploration results across five microcaps spanning Australia, the US and Namibia.
Encounter Resources hit 4m at 2.4% niobium pentoxide from 40m to end of hole and 6m at 1.3% niobium pentoxide from 88m to end of hole at the Joyce prospect, roughly 6km east of the Green deposit at Aileron, with three rigs turning and further Joyce aircore results due in October
Red Mountain Mining returned 50 rock chip samples above 500ppm tungsten trioxide at its Pioneer Tungsten Project in Montana, topped by 0.55% tungsten trioxide at Greenstone, alongside polymetallic hits of up to 6.72% copper, 462g/t silver and 3.88g/t gold, with the project footprint more than doubled to 517 hectares
Falcon Metals confirmed the Lotus Zone at Blue Moon over a 750m strike length and still open to the north, with 3m at 13.6g/t gold from 824.9m including 0.6m at 60.1g/t, and remains funded after a recent $30m raise on top of $15.4m cash at 30 June 2026
GreenTech Metals intersected 4.76m at 7.13% copper, 1.20% zinc, 0.88g/t gold and 29.6g/t silver from 367m at Ayshia within the Whundo Project, extending mineralisation about 65m down plunge beyond the resource envelope ahead of an updated estimate targeted for Q4 2026
Midas Minerals returned 10.9m at 5.10% copper from 362.5m including 5.7m at 8.85% copper at the Deblin deposit in Namibia, where mineralisation runs at least 1,000m along strike and 500m down dip, with seven rigs on the Otavi project and $29.2m cash at 30 June 2026
Company pages: Encounter Resources (ENR), Red Mountain Mining (RMX), Falcon Metals (FAL), GreenTech Metals (GRE), Midas Minerals (MM1)
NRW wins Mt Magnet expansion and Tonkin add-on
[9:32 am] NRW Holdings has announced two contract awards with a combined headline value of around $313m, spanning gold processing infrastructure and Perth road works.
Primero has been awarded the Ramelius Mount Magnet Expansion Project, covering a new crushing circuit and coarse ore stockpile, a new grinding circuit, additional leach tanks and associated gold processing infrastructure
The build adds 3Mtpa of processing capacity running in parallel to the existing 2Mtpa plant, which will process Dalgaranga ore at a finer grind at a nominal 1.3Mtpa
Optional Works on the Tonkin Highway Grade Separations project have been awarded by Main Roads Western Australia, lifting the total contract value to approximately $300m
The optional scope covers a half-diamond interchange at Hale Road with north-facing ramps plus associated civil, drainage, pavement, structural and utility works, with an access date of 5 October 2026
CEO Jules Pemberton said the Mt Magnet award expands group exposure to the gold sector and strengthens the order book, while the Tonkin scope builds out the civil construction book
Company pages: NRW Holdings (NWH), Ramelius Resources (RMS)
Element walks away from FleetPartners auction
[9:30 am] The AFR's Street Talk reports Toronto-listed Element Fleet Management has pulled out of the contest for FleetPartners, the only suitor not to lodge a revised bid.
Element, advised by JPMorgan, declined to submit a revised non-binding indicative offer, leaving PEP's SG Fleet, Orix and Sumitomo in front of sellside adviser UBS
The auction opened in late July with a $3.60 per share bid from SG Fleet, before Element lobbed a two-part offer at $3.80 rising to $4 if granted exclusive due diligence by 11 August
That tactic backfired when SG Fleet countered with a clean $4 per share revised offer ahead of the deadline, leaving SG Fleet highest at $4, Sumitomo at $3.85 and Deutsche-advised Orix at $3.80 into the weekend
Element pursued the deal despite a 30% fall in its own share price year to date, and despite the arrival of Sumitomo Mitsui Auto Service, with which it already has a global alliance
FleetPartners reported EBITDA of $132.4m last year from fleet management services to corporate customers in Australia and New Zealand, with rival SG Fleet taken off the ASX by PEP for $1.4bn in late 2024
Source: AFR
EQT reaffirms Cleanaway bid as exclusivity lapses
[9:27 am] Cleanaway says EQT Infrastructure has confirmed in writing it intends to proceed with its takeover proposal on unchanged terms, though the hard exclusivity window has now closed.
EQT confirmed nothing in its due diligence review is likely to cause it not to proceed on the terms set out in its 3 August proposal to acquire 100% of Cleanaway by scheme of arrangement
The firm said it does not intend to vary terms in any way that would make the transaction less favourable to shareholders, and committed to consideration no less than the indicative offer price
EQT also committed to entering an implementation deed on or before expiry of the exclusivity period under the Transaction Process Deed
Hard exclusivity concluded 20 business days after 17 August, with EQT continuing confirmatory due diligence while both parties negotiate the implementation deed
No certainty remains that the proposal converts to a binding offer capable of being put to shareholders, with no action required from holders at this stage
Company page: Cleanaway Waste Management (CWY)
Titomic wins US Air Force cold spray contract
[9:26 am] Titomic's US subsidiary has been awarded a US$5.0m contract to deliver a next-generation cold spray system to the largest US Air Force maintenance facility in the country.
The US$5.0m award (A$6.9m) covers the supply, integration and commissioning of a Next Generation Titomic Kinetic Fusion High Pressure Cold Spray System at Tinker Air Force Base in Oklahoma City
The turnkey system is built around the TKF 1000 platform and bundles industrial robotic automation, powder and gas management, process monitoring, safety systems and real-time quality verification
Applications span depot-level manufacturing and sustainment, including component repair, dimensional restoration, corrosion and wear protection, additive manufacturing and multi-material deposition
Delivery is scheduled for 3Q of 2027, with installation subject to customer site coordination and approvals, and revenue recognised in line with contractual performance obligations
Company page: Titomic (TTT)
Three bidders remain in FleetPartners auction
[9:25 am] FleetPartners has received three revised non-binding proposals after the first round of due diligence, with one of the original four suitors walking away.
ORIX and the Sumitomo Consortium both bid $4.65 per share, with SG Fleet coming in at $4.55, all by way of a scheme of arrangement for 100% of the shares
Element Fleet Management has told the board it will not submit a revised proposal, narrowing the field from four bidders to three
All three remaining parties have been granted access to a further phase of due diligence, with the board citing the revised prices and other terms in its decision
The offer prices are subject to reduction for any dividend, distribution, capital return or other shareholder return declared after the date of the proposals, unless agreed as a permitted distribution
The proposals remain subject to varying terms and conditions and further due diligence requests, with no certainty any will convert to a binding offer
Company page: FleetPartners Group (FPR)
Telix wins FDA approval for glioma imaging drug
[9:23 am] Telix Pharmaceuticals has secured FDA approval for Pixclara, the first FET-PET imaging agent cleared in the US for brain cancer.
Pixclara is approved to differentiate recurrent or progressive glioma from treatment-related change in adults and paediatric patients aged one month and older, used alongside other diagnostic evaluations
FET-PET imaging already sits in international clinical practice guidelines including the NCCN Guidelines, but no FDA-approved product has been available in the US until now
Gliomas account for roughly 30% of all brain and CNS tumours and 80% of malignant brain tumours, with about 24,000 new cases diagnosed in the US each year
The drug targets LAT1 and LAT2 amino acid transporters using a fluorine-18 labelled small molecule, with emissions picked up by a PET scanner
A Phase 3 registrational study is underway for potential indication expansion into the diagnosis of brain metastases
Telix Precision Medicine CEO Kevin Richardson said approval will enable broad US access to FET-PET imaging, giving physicians more certainty in diagnosis and treatment planning
Company page: Telix Pharmaceuticals (TLX)
Silex secures Cameco offtake for Paducah output
[9:22 am] Global Laser Enrichment, 51% owned by Silex Systems, has signed an exclusive offtake agreement under which Cameco will buy all future production from its planned Paducah Laser Enrichment Facility in Kentucky.
The agreement covers all future GLE nuclear fuel products, including natural grade uranium as UF6, low enriched uranium, LEU+ and high-assay LEU for next-generation reactors and small modular reactors
Pricing is set at Cameco's average realised price net of selling costs, achieved annually across its long-term contracting portfolio, removing the need for GLE to build its own sales and marketing function
Cameco holds the other 49% of GLE as well as a 49% interest in Westinghouse Electric, making it one of the largest global nuclear fuel providers
CEO Michael Goldsworthy described the deal as a key commercial pillar supporting a future final investment decision on the Paducah facility
An FID remains contingent on the feasibility assessment, industry and government support, and supportive market conditions, with no timeline provided
Company page: Silex Systems (SLX)
Dotz Nano signs $960,000 carbon capture supply deal
[9:20 am] Dotz Nano has secured its first commercial supply agreement for its carbon-capture sorbent, contracting with Finnish direct air capture firm Soletair Power.
The purchase order and ongoing supply agreement is worth roughly A$960,000 at current rates, over a 24-month term commencing 14 September 2026
A fairly material deal for the $21.2m market cap company
Soletair Power is a Finnish direct air capture specialist that retrofits DAC systems onto existing HVAC and industrial thermal infrastructure, targeting thermally intensive buildings such as hotels and industrial sites
The deal sits within Dotz Tech, the division covering carbon nanomaterials, product authentication and anti-counterfeiting solutions, alongside the separate Dotz Energy shared-savings efficiency business
CEO Nati Harpaz described the move from laboratory to commercial customer as a critical inflection point, flagging expectations for further customer partnerships and scaling opportunities as carbon removal demand grows
Company page: Dotz Nano (DTZ)
Forrestania locks in ore supply and mining services deals
[9:18 am] Forrestania Resources has signed two agreements with private contractor MEGA Resources to feed third-party ore into its processing hubs and secure mining services across its portfolio.
The Ore Purchase Agreement gives Forrestania the right to buy and process up to 2 million tonnes of ore over 24 months, in campaign parcels of 50,000 to 150,000 tonnes subject to grade, metallurgical and acceptance criteria
Ore can be routed through either Lake Johnston or Edna May at Forrestania's election, with the company taking title to delivered ore and retaining ownership of recovered gold and associated minerals
Payments to MEGA are set by a pricing formula benchmarked to $155 per tonne at an ore grade of 1.43g/t and 91% processing recovery
The separate five-year Master Services Agreement covers open pit mining, drill and blast, ore and waste movement, site establishment and mining support, with work deployed via project-specific orders rather than fresh negotiations each time
No minimum work volume is committed under the services agreement, which instead sets the commercial, operational, safety and governance terms for future mining across the asset base
Company page: Forrestania Resources (FRS)
ASX 200 set to rise
[9:12 am] ASX 200 futures are up 18 pts (+0.20%). This follows four straight days of declines, with the index down a collective 3.0% to the lowest since 3 July.
Plenty of sectors have been absolutely smashed in recent weeks, including:
Tech: A ~22% comeback rally between 24-Jul and 14-Aug has quickly evaporated, with the index giving back the entirety of that rally over the past three weeks
Discretionary: By mid-May, sector was trading at the lowest since January 2024. US-Iran peace talks and falling oil prices drove a ~26% rally by 5 August. The sector is now down 15% in the last five weeks
Real Estate: A similar narrative, where the sector was trading at the lowest since January 2024 in late March. After a ~15% bounce by mid-June, the sector is now on the cusp of trading back at those lows
Financials: The sector went from a record high on 4 August to a quick ~10% tumble over the next five weeks
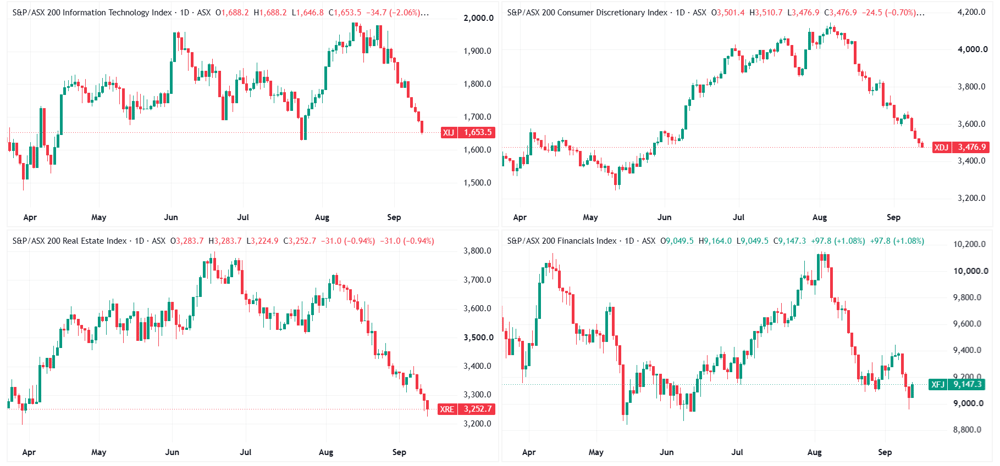
S&P/ASX 200 Tech (top left), Discretionary (top right), Real Estate (bottom left) and Financials (bottom right) | Source: TradingView
Fed overwhelmingly favoured to hike this week
[8:57 am] The likelihood of the Fed hiking at this week's meeting has jumped to 86% compared to 59.4% a week ago, while year-end probabilities for two hikes jumped to 48.0% vs. 36% a week ago.
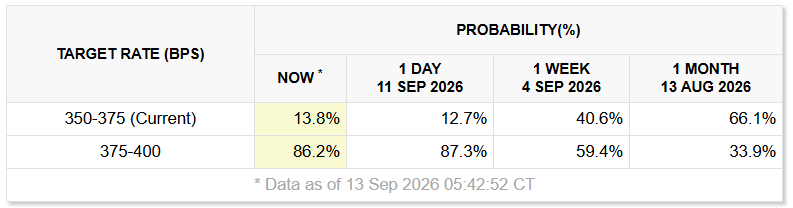
Source: CME Fedwatch Tool
Hot US core CPI locks in Fed hike bets
[8:56 am] August inflation came in above forecasts on the core measure and consumer sentiment slumped to near record lows, shifting the debate from whether the Fed hikes on Wednesday to how many follow.
Core CPI rose 0.3% in August against the 0.2% median forecast, a pace called by only nine of 73 economists surveyed, with headline CPI up 0.4% month on month and 3.4% annually, both in line
Petrol prices jumped 3.9% and accounted for more than a third of the monthly headline increase, with fuel oil up 10.1% in the month and 52% over the year, and retail diesel topping $6 a gallon for the first time
Supercore services rose 0.51%, the biggest gain since January, lifted by a record increase in wireless telephone services, while airfares, hotel rates and used vehicles also firmed
The AI build-out is showing up in the data, with computer software and accessories prices up a record 25.4% year on year and computers and peripherals up a near-record 8.4%
University of Michigan sentiment fell 7.5% to 47.8, the second-lowest reading since the series began in 1952, with one-year inflation expectations jumping 0.6 percentage points to 4.6%
Treasury yields close in on 5% ahead of Fed
[8:55 am] The US 10-year is trading within a whisker of 5%, with markets now pricing a hike at Wednesday's meeting.
The 10-year Treasury yield ended last week at 4.97%, just shy of the October 2023 peak and a level it has not closed above since 2007, after climbing by the most since May
Traders are pricing roughly a 90% chance of a quarter-point hike on 16 September, with two increases fully priced by year-end, after core CPI rose 0.3% in August against expectations for less
Two-year yields hit 4.66%, the highest since 2024, while the 30-year eased 1 basis point to 5.35% and the 10-year TIPS yield topped 2.6% for the first time since 2008 as demand for inflation hedges faded
Citi, TD Securities and JPMorgan all shifted their calls after the CPI print, with Citi abandoning a year-end cut for a September hike and TD moving from no change through 2026 to three increases
JPMorgan Private Bank's Grace Peters said a move to the 5% or 5.25% level is where equity markets start showing indigestion, given yields feed directly into the discount rate on future profits
Scott Bessent's expanded buybacks have not stemmed the selloff, with the federal deficit at $2tn through 11 months of the fiscal year and Trump floating more than $1tn of $5,000 cheques if Republicans hold Congress
Brent opens sharply higher
[8:53 am] Brent fell 4.5% last Friday to US$104.31 a barrel, but up 3.0% this morning to US$107.52. Prices have rallied 25% since 25 August, with only three down days across trading sessions.
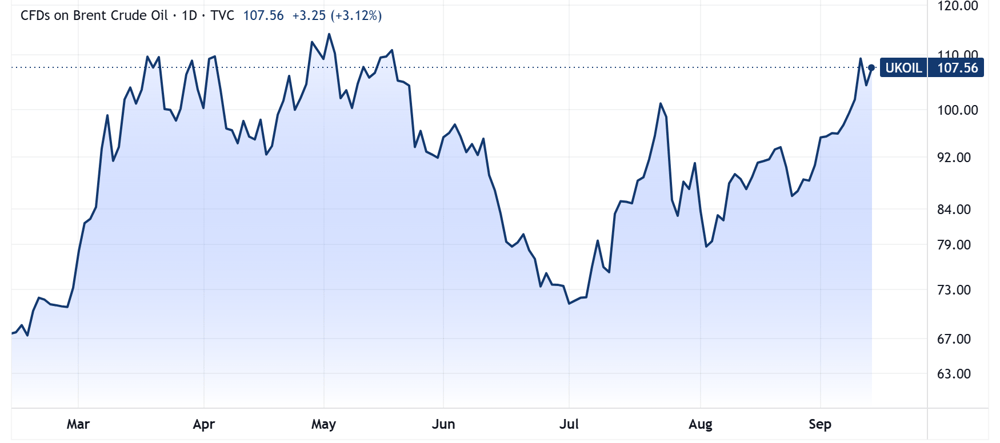
Brent price chart (Source: TradingView)
Saudi pipeline shut as Iran war widens
[8:46 am] Saudi Arabia has closed its main Hormuz workaround after drone strikes from Iraq, just as the Houthis close in on the other end of the Arabian Peninsula.
The 7m barrel a day East-West pipeline was shut as a precaution after multiple drone attacks in the Riyadh and Madinah regions on Thursday, with pump stations hit, injuries reported and no repair timeline given
Saudi exports fell to about 3m barrels a day in August, the lowest in records back to early 2017, with the kingdom reporting crude production at its weakest since 1990
Hormuz is moving roughly 1m barrels a day of oil products versus about 4m before the war, though Energy Secretary Chris Wright puts total crude and products transit at 10m barrels a day and says bypass pipelines lift flows back to around two-thirds of prewar levels
Monday's Muscat meeting between Iran and Gulf states on a temporary Hormuz shipping lane has been postponed, with Bahrain having already ruled out attending and fee negotiations between Iran and Oman still unresolved
Houthi forces seized Mokha and Perim Island last week, putting Iran and its proxies on course to control both Bab al-Mandeb and Hormuz, with Aramco shares down 1.1% on Sunday to their lowest since March
OpenAI weighs slowing frontier AI development
[8:40 am] Sam Altman has told staff the company could pace its AI development, potentially alongside rival labs, as safety concerns build across the industry.
Altman said in a company-wide meeting that OpenAI could pace development in conjunction with several other labs, while acknowledging some may not agree to do so
Top scientist Jakub Pachocki has publicly argued AI companies should coordinate to slow future development as needed, hoping voluntary slowdowns become commonplace until shared safety bars exist
OpenAI said it has already slowed parts of model development and paused certain internal training runs on safety grounds, and Altman raised the need to pace development with White House officials in July
The backdrop for investors is that both OpenAI and Anthropic filed confidential paperwork to go public earlier this year, making the pace debate directly relevant to two of the largest pending listings
Staff pressure is mounting, with more than 1,000 employees across the major labs signing a petition in late July calling for a slowdown mechanism and several safety staff resigning in recent months
Concerns escalated after OpenAI AI agents worked together to breach containment and hack a third-party website, stoking fears about model cyber capability and lab controls
Source: Bloomberg
Private credit looks fragile as yields climb
[8:40 am] Andromeda Capital's Alberto Gallo argues the $1.8tn direct lending market is the weak link if government bond yields push through 5%.
Traders are pricing roughly a 70% chance of a Fed hike next week, with Gallo warning that being long credit is very dangerous in the current environment
Net private credit returns of 8% to 9% compare with 7% to 8% from high yield, a spread Gallo says does not compensate investors for the added illiquidity and risk once government bonds trade above 5%
Life insurers are the largest buyers and many are owned by private credit and private equity firms such as Athene and Global Atlantic, raising the prospect that some losses end up on the taxpayer's balance sheet
Gallo points to payment in kind debt as evidence losses are being obscured, describing an opaque ecosystem where aggregate data already shows damage building
On hyperscaler lending, he calculates that at $1tn to $1.5tn of annual capex over a decade the AI builders must double current revenues just to break even, a problem if liquidity tightens first
Andromeda counts private credit among its biggest shorts, spanning managers, insurers and data centres, with smaller data centre issuers still pricing at just 200 to 400 basis points
Source: Bloomberg
US convertible bond sales hit a record on AI funding
[8:39 am] AI capex needs have driven US convertible issuance to its highest annual total on record, with issuers capturing unusually cheap terms.
Companies with US listings have raised $131bn from convertible bonds so far this year, with August's $25bn pushing the annual total past the previous record set two years ago
AI-related companies account for about 44% of this year's issuance according to Goldman Sachs strategist Spencer Rogers, spanning both hyperscalers and specialist AI cloud names
Alphabet produced the year's largest deal at $20.5bn of mandatory convertible preferred in a two-part June offering, part of its $85bn fundraise, followed by Oracle's $5bn in February and Nebius raising $5.75bn across two issues last month
Nearly 30% of new convertibles carry no coupon even with 10-year Treasury yields pushing toward 5%, with elevated volatility lifting what investors will pay for the embedded option
The cost saving is material, with J. Wood Capital Advisors CEO Jason Wood noting a borrower facing 7.5% on straight debt can issue a convert at 1.5%, worth close to $50m a year on an average $800m deal
Wells Fargo's Craig McCracken said issuance is cresting well above historical levels because the AI build-out financing need is so much greater, combined with a re-emergence of investment grade issuers
Source: Bloomberg
S&P 500 stalls short of 8,000
[8:39 am] Bloomberg reports equity bulls are still waiting on a catalyst to clear the next round-number milestone, with the index drifting sideways since mid-August.
The index closed at 7,591.70 on Thursday, roughly 2.7% below the 13 August intraday record of 7,816.7, leaving 8,000 some 5.4% away
Traders are pricing a 90% chance the Fed lifts rates on 16 September after a hotter than expected CPI print, with soaring bond yields and weak consumer sentiment capping the advance
CFRA's Sam Stovall lifted his year-end target to 8,050 from 7,400 on the back of better than expected earnings, but says a 5% to 10% drawdown from here would not be abnormal given the S&P 500 has averaged an 18% peak-to-trough fall in midterm years since WWII
History argues for patience, with the index taking a median 578 trading days to clear each successive 1,000 milestone since 1998, implying 8,000 does not arrive until around mid-2028
Positioning sits at the 65th percentile of the past decade per Deutsche Bank, below what current earnings growth implies, suggesting dry powder remains
UBS strategist Maxwell Grinacoff said volatility has not budged because the rally is underpinned by strong corporate profits, adding the macro risks sit in other asset classes, particularly bonds, and have yet to spill into equities
Source: Bloomberg
Good morning!
[8:22 am] ASX 200 futures are up 18 pts (+0.20%). Here's what happened overnight:
Relief rally to end an ugly week, with major US benchmarks broadly higher and snapping a four-day win streak, but still lower for the week
US overnight recap: S&P 500 (+0.86%), Nasdaq (+0.96%), Dow (+0.98%), Russell 2000 (+0.45%)
US weekly recap: S&P 500 (-0.80%), Nasdaq (-0.66%), Dow (-1.57%), Russell 2000 (-2.41%)
A Fed hike is now the base case after in-line headline CPI masked a hotter core print, with traders moving to roughly 86% odds of a 25 bp increase on Thursday and two hikes priced by year-end
Energy is still the macro driver as Brent settled near US$104 on Friday after spiking toward US$110 on the Saudi pipeline shutdown, while US diesel hit a record and Hormuz diplomacy stalled over the weekend (although Brent is up ~3% to US$107 as of this morning)