ASX 200 Live Today - Friday, 4th September
The ASX 200 gave back early gains after a sharp reversal for miners. Here are today's top stories.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Friday, September 4. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
ASX 200 lower for the week as miners and tech tank
[2:10 pm] That's a wrap! The ASX 200 is down 19 points (-0.21%) and trading around session lows. A quiet one overall, with only utilities (-1.0%), energy (-1.1%) and materials (-1.2%) in the red. Most of the reversal traces back to BHP, which opened flattish and is now down 2.6%. That leaves the index on track to finish the week 1.0% lower, with materials (-5.0%) and tech (-5.5%) the main drags.
Agriculture names rallied on an upgrade to the Australian wheat crop forecast and a broad lift across wheat, corn and soybeans. Graincorp and Elders caught the bid, as did defensives including Ansell, Endeavour Group and Dalrymple Bay.
Ticker | Company | 1 Week | Price |
|---|---|---|---|
GNC | Graincorp | 12.73% | $6.82 |
ASB | Austal | 7.14% | $4.35 |
PXA | Pexa Group | 6.43% | $7.45 |
TLX | Telix Pharmaceuticals | 6.19% | $16.63 |
RSG | Resolute Mining | 5.96% | $1.46 |
ANN | Ansell | 5.35% | $42.53 |
AMP | Amp | 5.34% | $2.47 |
ELD | Elders | 5.24% | $6.23 |
EDV | Endeavour Group | 5.21% | $3.23 |
DBI | Dalrymple Bay Infrastructure | 5.08% | $5.38 |
Pinnacle tumbled after KPMG delayed signing off on the annual accounts at three Metrics Credit Partners funds. Gold, copper and lithium all finished the week broadly lower.
Ticker | Company | 1 Week | Price |
|---|---|---|---|
PNI | Pinnacle Investment Management Group | -19.39% | $14.12 |
SLX | Silex Systems | -16.04% | $4.95 |
LOV | Lovisa | -13.68% | $23.22 |
NXT | NextDC | -12.30% | $12.73 |
EOS | Electro Optic Systems | -11.69% | $9.56 |
GGP | Greatland Resources | -9.28% | $11.63 |
ELV | Elevra Lithium | -8.86% | $7.67 |
MI6 | Minerals 260 | -8.38% | $0.82 |
CSC | Capstone Copper Corp | -7.83% | $15.07 |
LYC | Lynas Rare Earths | -7.43% | $15.14 |
Arafura Rare Earths shareholder update highlights
[1:28 pm] Management walked through the rare earth market backdrop, the path to financial close and the start of construction at Nolans in the coming weeks.
On NdPr pricing: "NdPr started the year around $62 a kilo, peaked at $129, and currently sits around $107 a kilo"
On the effect of Western price floors: "The U.S. and Japan introduced pricing floors of US$110, and that actually has had a stabilising effect on Chinese domestic pricing, where it has basically stayed range-bound between US$100 and US$120 a kilo, which really shows how effective these price floors have been"
On Chinese pricing transparency: "China's domestic rare earth pricing isn't transparent. The constituent weights and trading volumes simply aren't disclosed. Frankly, it's more of a policy instrument than a reliable market signal"
On China's continued dominance: "There's been a lot of activity building out a rest-of-world rare earth supply chain, but structurally, China is still very much in control, and that's not going to change quickly... It typically takes 18 years to find and bring a new mine into commercial production"
On the construction and production timeline: "We have a 37-month construction schedule from the start of construction in a couple of weeks' time... We expect practical completion towards the end of 2029... So that would see, if you like, production reaching nameplate at the end of 2031, early 2032"
On the share price versus cash backing: "If you look at the amount of cash that we have on the balance sheet, that is not much different to our market cap. Talking to an investor recently and using his words is, 'Investing in Arafura at the moment is like having a free option'"
On robotics demand: "A typical humanoid robotic uses the same amount of rare earths as one EV. You can see how robotics will ultimately be a much bigger consumer of rare earths than EVs"
Company page: Arafura Rare Earths (ARU)
Nomura flags three straight BOJ hikes in extreme case
[1:27 pm] Nomura's head of FX strategy for Japan sees a September move as reasonable, with back-to-back hikes possible if the yen weakens again, Bloomberg reports.
Three consecutive hikes through December are the tail scenario, contingent on yen weakness momentum resuming toward 160 per dollar
The baseline is less aggressive, with Yujiro Goto seeing at least one hike per quarter as likely or necessary and holding a dollar-yen target of 154
Markets are already positioned for more, with overnight index swaps more than fully pricing a 25 basis point hike by September and another fully priced by January
The yen has rallied more than 2% this week to around 156 per dollar on faster tightening expectations and speculation over a change in GPIF asset allocation
Source: Bloomberg
ASX 200 gives back early gains
[12:20 pm] The S&P/ASX 200 was up as much as 50 pts (+0.56%) in early trade, now slightly down for the day. Miners are driving the bulk of this reversal, with the ASX 200 Materials Index down 0.91% vs. session highs of (+0.76%). BHP opened flattish, now down ~2%, gold and copper miners are giving back early gains.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
BHP | BHP Group | -2.3% | $62.32 | -6.4% | 36.9% |
RIO | Rio Tinto | -1.3% | $174.73 | -2.2% | 19.0% |
FMG | Fortescue | 1.6% | $17.22 | -4.1% | -21.8% |
NST | Northern Star Resources | 0.2% | $23.21 | -4.7% | -5.5% |
EVN | Evolution Mining | 1.4% | $15.23 | -3.3% | 21.1% |
S32 | South32 | 0.1% | $5.22 | 1.1% | 46.9% |
PLS | PLS Group | -3.4% | $5.03 | -3.4% | 19.6% |
LYC | Lynas Rare Earths | -0.2% | $15.23 | -6.8% | 22.8% |
BSL | Bluescope Steel | -0.1% | $31.98 | 4.6% | 32.8% |
MIN | Mineral Resources | -2.6% | $61.66 | -3.7% | 13.3% |
JPMorgan warns a move below 155 could force a US$103bn yen short unwind
[11:26 am] The bank says traders are still heavily short the yen and a break of that level could trigger a much bigger rally than the market is positioned for.
Traders still hold ¥16-17 trillion (US$103bn) of short yen positions on JPMorgan estimates, and closing all of them out could take dollar-yen down to 142-146
A break below 155 could turn selling into a stampede, strategists wrote, with this week's price action suggesting a large short is still in place
Dollar-yen touched 160.39 earlier this week, its highest since Japan and the US intervened together in late July, before reversing to as low as 155.30
That puts the pair within a fraction of its post-intervention low of 155.23, with spot at 155.76
The rally has been driven by talk of a GPIF asset allocation shift and rising expectations for faster BOJ rate hikes, with short covering and domestic hedging demand adding fuel
JPMorgan thinks both of those bets have run too far and still sees little chance of dollar-yen breaking well below its assumed 155-165 range
Source: Bloomberg
Gold stocks rally on bond yield and US dollar pullback
[10:23 am] Gold prices rallied 1.8% overnight to US$4,472/oz, now up 3.3% in the last two sessions following a 7.0% selloff over the prior five sessions. Local gold miners have opened sharply higher, rallying for a second session.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
PNR | Pantoro Gold | 7.0% | $3.00 | 7.7% | -38.9% |
OBM | Ora Banda Mining | 6.8% | $1.61 | 0.1% | 5.0% |
MEK | Meeka Metals | 4.2% | $0.13 | 0.0% | -53.7% |
EMR | Emerald Resources | 3.6% | $7.24 | 4.2% | 15.3% |
BGL | Bellevue Gold | 3.3% | $1.70 | 1.2% | 0.6% |
WGX | Westgold Resources | 3.2% | $6.52 | 0.1% | 3.4% |
RMS | Ramelius Resources | 3.1% | $4.04 | 2.5% | -1.2% |
NEM | Newmont | 2.9% | $179.98 | -1.4% | 19.9% |
BC8 | Black Cat Syndicate | 2.8% | $1.12 | -1.8% | -7.8% |
RRL | Regis Resources | 2.6% | $8.65 | 2.4% | 15.0% |
ALK | Alkane Resources | 2.6% | $1.97 | 1.0% | 48.1% |
RSG | Resolute Mining | 2.6% | $1.48 | 7.8% | 21.0% |
CYL | Catalyst Metals | 2.5% | $7.06 | 4.9% | -4.3% |
PRU | Perseus Mining | 2.4% | $6.80 | 1.6% | 23.4% |
AMI | Aurelia Metals | 2.3% | $0.45 | 2.3% | 83.7% |
VAU | Vault Minerals | 2.2% | $6.93 | 1.6% | 27.4% |
SBM | St. Barbara | 2.0% | $0.76 | 6.3% | 32.2% |
NST | Northern Star Resources | 2.0% | $23.63 | -2.9% | -3.8% |
GMD | Genesis Minerals | 2.0% | $8.53 | 1.7% | 19.1% |
CMM | Capricorn Metals | 2.0% | $16.66 | -0.5% | 19.0% |
EVN | Evolution Mining | 1.9% | $15.29 | -2.9% | 21.6% |
Tech stocks broadly higher
[10:20 am] The S&P/ASX 200 Tech Index is up 1.05% in early trade after a four-day skid where it tumbled 6.1%. This follows a strong US lead, where the Nasdaq rose 1.40% and the iShares Expanded Tech-Software ETF rallied 3.4% on strong earnings from Snowflake.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
AD8 | Audinate Group | 4.2% | $2.46 | -6.5% | -39.4% |
NXL | Nuix | 3.9% | $1.98 | -4.6% | 9.1% |
MP1 | Megaport | 3.7% | $16.93 | -2.1% | 49.2% |
CAT | Catapult Sports | 3.5% | $3.21 | -4.5% | -22.8% |
360 | Life360 | 3.1% | $20.55 | -0.4% | -36.2% |
ZIP | Zip Co | 2.9% | $2.45 | -5.0% | -25.1% |
DTL | Data#3 | 2.7% | $11.10 | 0.7% | 23.7% |
DGT | Digico Infrastructure REIT | 2.2% | $2.80 | 8.1% | 0.4% |
OCL | Objective Corporation | 2.0% | $6.50 | 5.0% | -60.7% |
WTC | Wisetech Global | 2.0% | $37.51 | -7.4% | -45.2% |
MAQ | Macquarie Technology Group | 1.7% | $55.30 | -10.8% | -17.5% |
HSN | Hansen Technologies | 1.6% | $3.41 | -1.9% | -35.5% |
PPS | Praemium | 1.6% | $0.62 | -13.3% | -22.0% |
IFT | Infratil | 1.3% | $12.06 | 0.9% | 25.9% |
WBT | Weebit Nano | 1.3% | $3.49 | -12.9% | -30.3% |
DDR | Dicker Data | 1.2% | $14.66 | 4.6% | 42.5% |
BVS | Bravura Solutions | 1.1% | $3.16 | 3.4% | 22.8% |
SDR | Siteminder | 1.1% | $2.86 | -8.6% | -53.3% |
PME | Pro Medicus | 1.0% | $174.42 | -3.3% | -21.0% |
TNE | Technology One | 0.9% | $31.13 | -3.4% | 13.0% |
IRE | Iress | 0.7% | $5.56 | -4.1% | -33.7% |
NXT | NextDC | 0.3% | $12.58 | -13.3% | 2.2% |
XRO | Xero | 0.0% | $80.71 | -3.4% | -29.1% |
CDA | Codan | -0.3% | $46.57 | -4.8% | 63.9% |
ASX 200 up for a second day
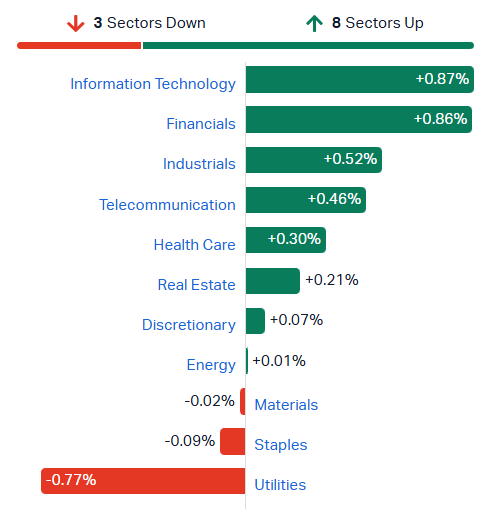
[10:08 am] The bounce back continues, with Tech, Banks and small caps leading the charge. The S&P/ASX 200 is up 26 pts (+0.28%) in early trade, though already off session highs of 0.56%.
S&P/ASX 200 sectors (Source: Market Index)
Australian bond yields hit 15-year high as funds see value
[10:03 am] Australian government bonds have underperformed global peers through the fixed-income selloff, prompting several offshore managers to add exposure.
The 10-year yield rose about 30 bps over the month through Wednesday
to a 15-year high of 5.25%, more than any global peer
US correlation is the main culprit, with the rolling 60-day correlation between Australian and US 10-year yields above 80%, leaving the market exposed to deficit fears and hawkish rhetoric from Fed Chairman Kevin Warsh
Relative fundamentals are the bull case, with Australia holding AAA ratings from all three major agencies, debt to GDP well below the US and UK, and the RBA having already raised rates three times this year
Domestic data is mixed, with July inflation running hotter than expected and growth unexpectedly accelerating last quarter, against a higher jobless rate in July and falling home prices
Performance has still held up, with a Bloomberg gauge of Australian sovereign debt hedged for currency up 0.3% in 2026 versus a 0.7% fall for US Treasuries and 0.6% for global government debt
Managers are positioning to buy, with Aviva adding to 10-year holdings into the selloff, Rathbones calling valuations attractive, and Marlborough's James Athey waiting out the post-Warsh move before leaning against it
Source: Bloomberg
New Zealand home prices fall to three-year low
[10:01 am] August marked another decline in the Home Value Index, extending a slump that began in early 2022 and weighing on the domestic demand recovery.
Home Value Index down 0.4% in August from July's revised 0.5% fall, leaving prices 18% below their January 2022 peak
The RBNZ raised the Official Cash Rate to 2.75% on Wednesday, a second straight increase, and signalled a further hike is likely while it assesses the response to tightening already delivered
Cotality's Kelvin Davidson sees no near-term catalyst, citing economic uncertainty, rising mortgage rates and high listings volumes, with the market in a holding pattern set to last into next year
The 7 November general election is sidelining investors who are unclear on future tax policy, with the ruling National Party trailing in polls
The downturn is running longer than post-GFC, when values fell 10% and recovered within five years, with Davidson tying consistent price growth to labour market improvement that may not arrive until well into 2027
Source: Bloomberg
Core Lithium sells final Finniss fines stockpile to Glencore
[9:29 am] Core Lithium has agreed to sell the last of its lithium DSO fines stockpile, completing monetisation of all existing stockpiles at Finniss.
Binding marketing agreement with Glencore covering the final ~25kt of lithium DSO fines, the third such sale after transactions in April and June
Base price of ~US$285/t (~$400/t) CIF based on indicative Li2O content, subject to final grade adjustments and transport costs but otherwise unconditional
Shipment scheduled for this quarter through Darwin port, with proceeds expected to be received in the December quarter
Total 2026 lithium sales revenue of ~$38.5m from the stockpile monetisation strategy, which management framed as generating cash and financial flexibility while ramping up Finniss
First spodumene concentrate shipment targeted for the December quarter, with Brown noting the Finniss logistics chain has been successfully reactivated
Company page: Core Lithium (CXO)
ACCC clears Peter Warren's Wakeling acquisition with eight divestments
[9:28 am] The competition regulator has approved Peter Warren Automotive's purchase of Wakeling Automotive subject to the divestment of eight dealership sites in Sydney's Macarthur region.
Eight sites must be divested in Campbelltown and Smeaton Grange, covering Kia, GMSV, RAM, Isuzu UTE, GAC, Volkswagen and Suzuki brands
The ACCC's concern was regional concentration, with Commissioner Philip Williams noting Peter Warren would otherwise have operated 25 of 34 new car dealerships in the Macarthur region
Approval is subject to a mandatory 14-day review period under the new merger control regime, with completion expected in the coming weeks
The deal was first announced on 19 December 2025, covering 16 brands across 30 dealerships with annual turnover of $500m and around 370 employees
Consideration of approximately $28m including $21.7m of goodwill plus net assets at completion, funded from existing debt facilities and flagged as immediately EPS accretive after funding costs
Company page: Peter Warren Automotive (PWR)
Stanmore to acquire Moranbah South from Exxaro for US$105m
[9:23 am] Stanmore Resources has agreed to buy 100% of the Moranbah South tenements, adding premium hard coking coal resources adjacent to its existing Bowen Basin assets.
Consideration of US$105m funded from existing cash and liquidity, with no shareholder approval required
Tenements contain 724Mt of Measured and Indicated Coal Resources in the Goonyella Middle Seam, expected to be of premium hard coking coal quality
The deal extinguishes up to US$60m of deferred and contingent consideration under the 2024 Designated Area Agreement, improving the economics of the Isaac Downs Extension
Synergy case rests on Eagle Downs, with Moranbah South potentially accessed through the same drifts and infrastructure should that project be developed
Completion expected before the end of Q4 2026, conditional on Exxaro first acquiring Anglo American's 50% interest via pre-emptive rights, plus FIRB, ACCC and ministerial approvals
Company page: Stanmore Resources (SMR)
CATL's Jianxiawo mine shutdown revives lithium supply squeeze
[9:15 am] China's largest lithium mine by capacity has been placed into care and maintenance again, the AFR reports.
Benchmark Mineral Intelligence reported the mine's environmental impact assessment had been revoked
Benchmark cut its 2026 production forecast for Jianxiawo by almost half to 32,000 tonnes of lithium carbonate equivalent from 62,500 tonnes, with a restart hinging on a review that could stretch into the fourth quarter or 2027
Morgan Stanley flagged its 2027 balance could flip, warning that if the mine does not restart and Zimbabwe does not release additional export quotas, its forecast small surplus would likely become a small deficit
Energy storage demand remains the standout, with shipments up 94% this year after almost doubling in 2025 on the back of the AI build-out
EV demand is more mixed, with China sales softening on reduced incentives while sales doubled in Australia, Brazil, India, Korea and Vietnam in the second quarter, likely helped by higher oil prices
Source: AFR
S&P 500 back near all-time highs
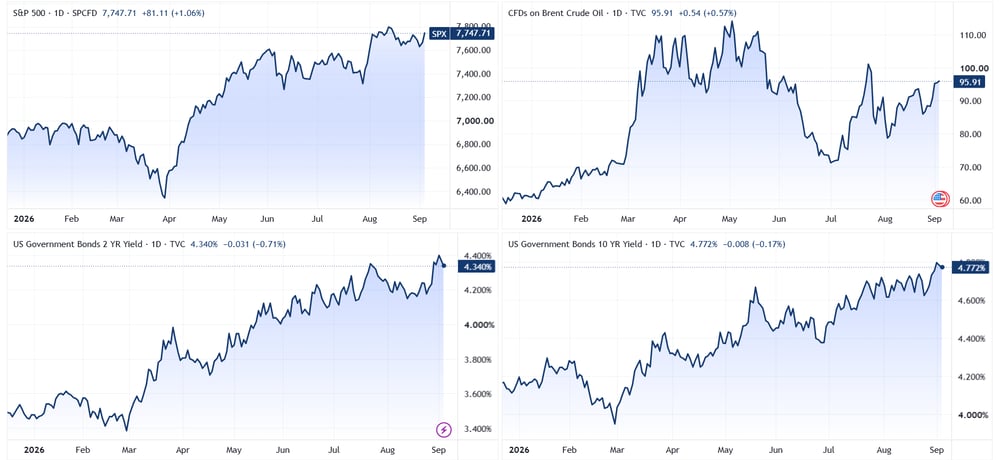
[9:15 am] The S&P 500 is now up 1.5% in the last two sessions, recouping the entirety of the prior three-day selloff. It's now within 0.7% of its 13 August record high, despite bond yields trading slightly below record multi-year highs, elevated Fed rate hike expectations, gas/diesel prices on the rise and inflation still tracking well-above target. Imagine if there was no Iran War ... the index would be at 9,000 by now?
S&P 500 (top left), Brent (top right), US 2-year (bottom left) and US 10-year (bottom right) | Source: TradingView
BOJ leaning toward quarter-point hike on 18 September
[9:00 am] The Bank of Japan is set to lift its policy rate this month with markets fully priced and Washington openly pushing for action.
Officials favour a 25 basis point move from the current 1%, with people familiar playing down a half-point hike as lacking any change in circumstances to justify it
Overnight index swaps have the September hike fully priced, meaning a decision to hold could itself jolt global markets
Ueda pointed to upside price risks, saying the bank needs to pay greater attention than before to them as underlying inflation approaches 2%, and did not push back on market pricing
The pace beyond September is left open, with the BOJ willing to adjust flexibly and hawkish board member Takata floating 50 or 75 basis point moves and back-to-back hikes
Brent back above US$95 as US-Iran conflict stalls
[8:58 am] Six months into the war, tit-for-tat strikes have pushed energy prices higher again and left both sides no closer to talks.
Brent up more than 8% this week to US$95.91 a barrel
US retail diesel prices at a four-year high, with regular petrol averaging US$4.14 a gallon
Hormuz transits ran at 102 last week and 126 the week before on Lloyd's List data, vs. 130 or more per day pre-war, with the US escorting 40 vessels carrying 18m barrels on Tuesday as a wartime high
Shipping economics remain punishing, with tanker charters through the strait estimated at more than $500,000 a day, war-risk insurance still elevated and LNG carriers even more cautious than crude
The blockade has stopped Iranian oil exports since July and pushed domestic inflation to around 80%, though China, Pakistan and Turkey are shrugging off US pressure to cut remaining ties
Fed rate hike bets ease
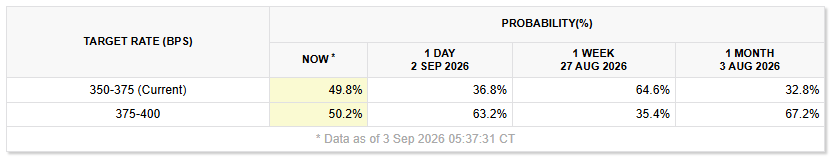
[8:50 am] Dovish comments from Fed governor Waller eased rate hike expectations, while Vice President JD Vance called for cuts to make housing more affordable.
The likelihood of a hike vs. hold is now a coinflip for the September meeting.
Source: CME Fedwatch Tool
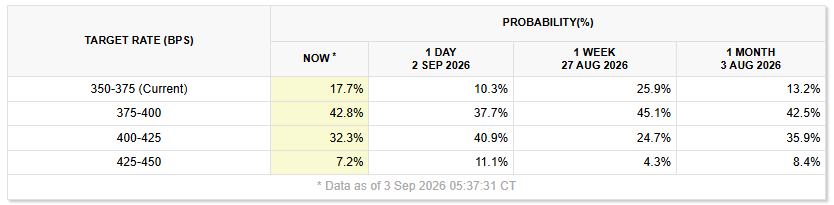
Year-end probabilities now favour one 25 bp hike, though two hikes still remain on the table.
Source: CME Fedwatch Tool
Waller says August CPI will decide his vote
[8:48 am] Fed Governor Christopher Waller signalled he could back holding rates if inflation keeps improving, softening market expectations for a September hike.
Waller tied his vote to the 11 September CPI print, saying he is willing to support holding the policy rate if there is continued progress toward 2%, but would consider a hike if inflation comes in hot
He described policy as only slightly restraining the economy, adding that it may not take much acceleration in inflation to nudge him into supporting tighter policy
Waller expecting reasonable consumer and producer price readings over the next month because higher energy costs have not spilled broadly into other prices
Fed funds futures moved during his remarks, with the probability of a hike at the 15 to 16 September meeting dialled back to about 50%
The committee remains split, with Michael Barr open to hiking this month if inflation fails to subside, John Williams seeing inflation continuing to ease as tariff effects fade, and three members having dissented for a quarter-point hike in July
Trillion-dollar dislocation sits beneath calm credit markets
[8:45 am] Bloomberg analysis finds a large pocket of high-grade bonds trading well wide of where their ratings suggest, even as headline spreads sit near multi-decade lows.
About $1trn of non-financial high-grade bonds are trading at spreads unusually wide relative to their credit rating, split between roughly $580bn in the US and almost $400bn in Europe
Headline spreads show none of it, with the US high-grade index averaging 0.78 percentage points and Europe 0.79 percentage points, both close to their lows, and 60-day volatility in global high-grade spreads around a five-year low
Hyperscalers now make up about 5% of the US high-grade index, double their share of two years ago, forcing managers to rebalance to avoid concentration and distorting pricing in names well beyond the AI leaders
Dislocations run across sectors, with carmakers marked down on Chinese competition, software names on AI disruption risk, and insurers on private credit exposure
Ratings bands are breaking down, with bonds of 25 single-A rated US borrowers across five sectors indicated wider than the triple-B spread curve in late August, and more high-grade debt trading wider than junk equivalents this summer
Source: Bloomberg
US high-grade bond supply on track for record September
[8:47 am] Wall Street dealers are positioning for a potential record month of US investment-grade issuance as surging yields push companies to lock in funding early.
September issuance forecasts sit at about $215bn on an informal Bloomberg dealer poll, against the $207.5bn record set for the month last year, with some predictions running to $250bn
Average US high-grade yields are above 5.5%, the highest in more than two years, giving treasurers reason to pull 2027 funding needs forward into 2026
Spreads remain tight at below 0.8 percentage points for much of the week, and the risk of waiting is that heavier supply later in the year weakens corporate debt relative to Treasuries
Supply has set records in four of 2026's eight months including the past three, with volume tracking 7.6% above 2020's pandemic-fuelled annual record
Bank of America is more cautious, forecasting about $190bn as big tech potentially sits out September after recent jumbo deals, which would still be the second-largest September on record
Source: Bloomberg
Good morning!
[8:35 am] ASX 200 futures are up 25 pts (+0.27%). Here's what happened overnight:
Fed Governor Waller said he could back a September hold if August inflation cools, driving Treasury yields and hike odds sharply lower and lifting major US benchmarks
S&P 500 (+1.06%), Equal-weight S&P 500 (+0.66%), Nasdaq (+1.40%), Dow (+1.18%) and Russell 2000 (+0.51%)
Nvidia bought Hugging Face for $12.93bn in its second-largest deal ever, while Snowflake's beat-and-raise quarter powered a broad software rally
Energy remains the inflation problem as Iran struck US bases in Kuwait and the UAE, Brent held in the mid-$90s and US retail diesel reached a four-year high just below its all-time record