ASX 200 Live Today - Friday, 18th September
The ASX 200 is trading flat as broad weakness spanning telcos, staples, banks and energy offset a solid bounce for miners.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Friday, September 18. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
ASX 200 gives back early gains
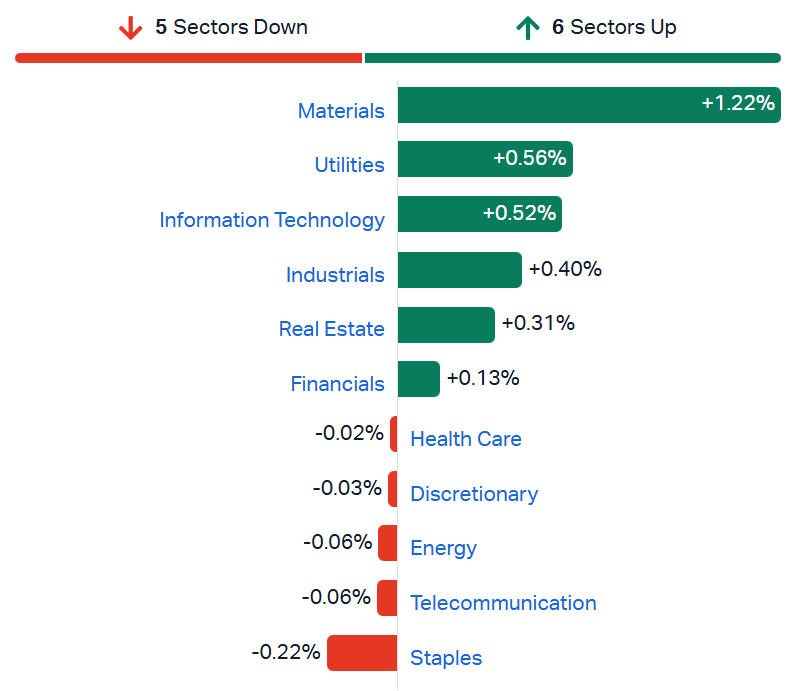
[2:00 pm] That's a wrap! The S&P/ASX 200 is trading smack bang on breakeven and down 0.1% for the week. A sizeable bounce in the miners has been more than offset by relatively broad weakness spanning staples, telcos, energy, banks and real estate.
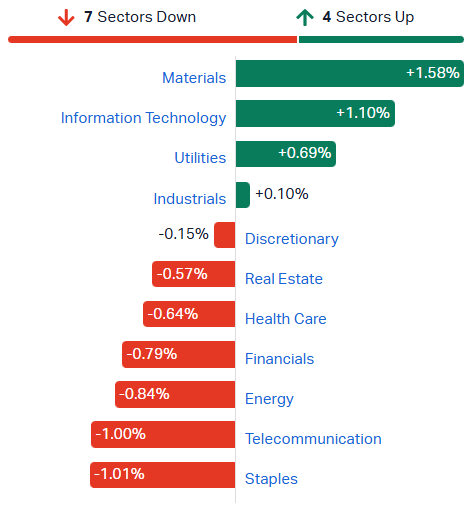
S&P/ASX 200 sectors (Source: Market Index)
Overall, not a whole lot to see here. Yields have taken a breather in recent days, with the Aussie 3-year down 11 bps over the past three sessions to 4.93% and the 10-year down 10 bps to 5.27%, while Brent has trickled back to US$104 from almost US$110 a week ago. Nothing much has changed, so perhaps this bounce is a hedge unwind relief rally.
Weekly ASX 200 gainers
[1:48 pm] Speculative growth names, defence and gold topped the leaderboard this week.
Ticker | Company | 1 Week | Price | YTD |
|---|---|---|---|---|
4DX | 4DMedical | 24.0% | $4.23 | 5.8% |
MI6 | Minerals 260 | 12.8% | $0.97 | 131.0% |
EOS | Electro Optic Systems | 10.2% | $10.20 | 8.1% |
INA | Ingenia Communities Group | 10.1% | $4.25 | -18.3% |
TLX | Telix Pharmaceuticals | 8.6% | $17.87 | 58.8% |
ALK | Alkane Resources | 8.5% | $1.99 | 49.2% |
CDA | Codan | 8.0% | $49.31 | 73.5% |
RWC | Reliance Worldwide Corp | 7.8% | $4.57 | 17.2% |
AUB | AUB Group | 7.5% | $28.89 | -5.4% |
ASB | Austal | 7.4% | $4.63 | -31.1% |
Weekly ASX 200 losers
[1:48 pm] A challenging week for lithium, uranium and coal names, while GQG continues to spiral lower.
Ticker | Company | 1 Week | Price | YTD |
|---|---|---|---|---|
ELV | Elevra Lithium | -15.2% | $6.32 | -21.4% |
GQG | GQG Partners | -12.8% | $1.06 | -39.7% |
DYL | Deep Yellow | -12.7% | $1.33 | -27.9% |
PLS | PLS Group | -12.5% | $4.16 | -1.1% |
MIN | Mineral Resources | -10.7% | $53.59 | -1.5% |
LTR | Liontown | -10.0% | $1.02 | -35.2% |
IGO | IGO | -9.7% | $6.95 | -15.1% |
WHC | Whitehaven Coal | -9.6% | $7.90 | 1.6% |
PDN | Paladin Energy | -9.5% | $9.91 | 2.9% |
VUL | Vulcan Energy Resources | -7.9% | $2.22 | -49.7% |
Yen falls as two dissents cloud BOJ outlook
[1:39 pm] The BOJ raised its benchmark rate to 1.25% as expected, but a 7-2 vote sent the yen lower.
The yen fell as much as 0.6% to 156.94 per dollar after the decision, with board members Toichiro Asada and Ayano Sato dissenting against the quarter-point hike
Wells Fargo's Chidu Narayanan said the outcome was not hawkish enough for markets and should push dollar-yen higher and front-end JPY yields lower, with the dissents undercutting expectations of rapid successive hikes
SMBC's Hirofumi Suzuki said the two votes against fuelled speculation further tightening may be harder than thought, though he did not read the statement itself as dovish
Lombard Odier's Homin Lee expects dollar-yen to stay anchored in a 155-160 range, arguing a significant yen rally would require a far more aggressive BOJ than he believes is intended
Intervention risk is back in focus after Japan spent a record ¥15.4 trillion ($98.3 billion) in the month through 26 August, with another push toward 160 potentially testing official tolerance
Source: Bloomberg
Anyone check in on tech stocks lately
[12:42 pm] Local tech names are looking like a momentum graveyard. WiseTech has traded lower in 15 of the past 18 sessions for a 21% decline, and Xero is much the same, down in 18 of the past 21 sessions for a 26% fall. NextDC has rolled over to its lowest since April, while Objective Corp has never traded the same since its 34% one-day selloff on 1 July 2026.
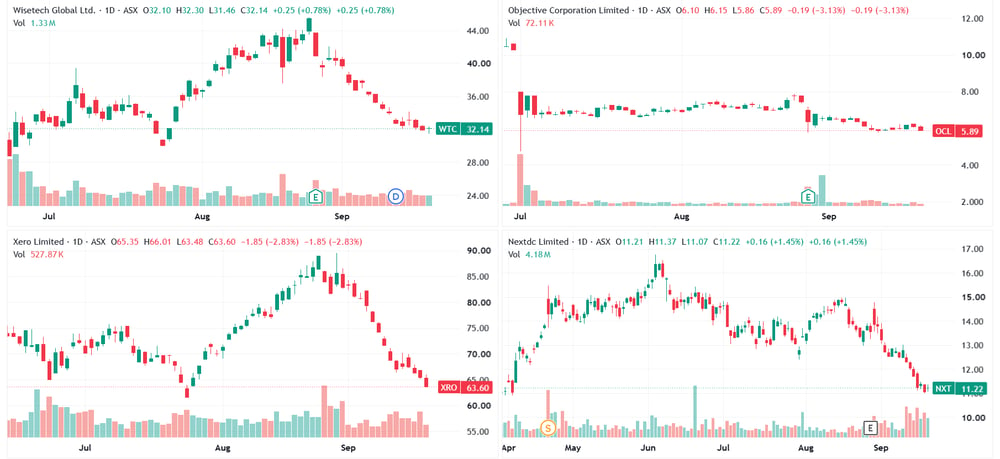
Wisetech, Objective Corp, Xero and NextDC daily charts (Source: TradingView)
Macmahon rallies on Aspect acquisition
[12:23 pm] Macmahon shares are up 6.0% to $1.05, within 4% of all-time highs and up 58% year-to-date. The company agreed to acquire 100% of Aspect Engineering Solutions, adding engineering and minerals processing to its mining services platform.
Headline enterprise value of $75m on a debt-free, cash-free basis, equating to about 5.0x FY26 EBIT against Macmahon's referenced trading multiple of 11.4x as at 30 June 2026
Aspect generated FY26 revenue of about $75m and EBIT of $15.2m, an implied margin near 20% versus Macmahon's group underlying EBITA margin of roughly 7%
Funded from existing cash as $30m upfront, $6m a year in retention payments for five years and earn-outs of $15m to $30m over three to five years, with Macmahon able to elect share consideration for the deferred amounts
Expected to be underlying EPS accretive from inception at around 6.2% pre-synergies, with a base case IRR of 40.4% and completion expected in the current calendar year
You see a lot of these value accretive deals from these engineering and infrastructure-related plays. Macmahon had a market cap of around $2.1 billion, spending ~$75 million to boost EPS by 6.2% (pre-synergies)? Sounds pretty good at first glance.
Company page: Macmahon Holdings (MAH)
Bullock flags shift in business inflation expectations
[12:20 pm] Michele Bullock told a parliamentary panel that Australian businesses are starting to question whether inflation returns below 3%.
Bullock said the fact businesses are starting to ask "is inflation coming back down?" is a concern, adding that while they are not explicitly forecasting a three-point-whatever outcome, "there is this sort of feeling" among them and "that is worrying"
The longer inflation stays above target, the more concerning it is that inflation expectations begin to adjust, she said, against the RBA's dual mandate and 2.5% midpoint target
Risks remain skewed to the upside, driven by inflation expectations, supply shocks from the Middle East and weather-related events, and demand-side issues
She said the trade-off between unemployment and inflation has worsened, noting it is much harder to look through persistent shocks given the risk they flow into expectations
"It's more important than ever that we bring inflation down to target," Bullock said
Source: Bloomberg
Yuan hits strongest level since 2022
[12:19 pm] The Chinese currency extended its rally after the PBOC strengthened its daily fixing for an eighth consecutive session.
The offshore yuan gained as much as 0.1% to 6.6967 per dollar on Friday, the strongest level since July 2022
Eight straight firmer fixings mark the longest streak since 2023, though the PBOC has kept reference rates weaker than prevailing market levels, signalling a preference for gradual appreciation
ANZ's Khoon Goh said the fixings show intent to narrow the gap between the fix and spot, with further gains likely if the recent trend continues
The yuan is heading for a seventh straight quarterly gain, one of Asia's best performing currencies this year on surging exports and robust conversion flows
The rally has held up even as rising Fed hike bets lift Treasury yields and the dollar, widening the China-US yield gap to a record
Firmer fixings come ahead of Donald Trump's meeting with Xi Jinping in the US, suggesting authorities are comfortable with a stronger currency
Source: Bloomberg
Memory shortage drives consumer tech hyperinflation
[11:20 am] A broker note on Australian Discretionary argues the AI capex boom has flowed through to consumer electronics pricing and availability.
Consumer tech hardware prices have run through a period of hyperinflation over the past year, with increases of up to around 40% on flagship items as manufacturers protect margins, a step-change from repricing only at new product iterations
Data centres competing with traditional electronics manufacturers for memory has created a supply/demand imbalance, driving both input cost increases and shortages, with some retailers out of stock of the Switch 2 as recently as early August
Relative stock positioning is beginning to normalise across the retailers, with a number of significant product releases still to come this year, particularly GTA VI in gaming, seen as supportive of category hype
The biggest uncertainty is global inventory flow, with Australia expected to rank lower priority given freight complexity and FX-driven pricing volatility
JBH is the preferred play on an Electronics recovery, with its elevated stock turn having caused shortages faster than peers but expected to normalise as competitors sell through inventory
HVN is least preferred on soft Furniture and Homewares demand, while WES remains favoured for relative defensiveness through Bunnings and Kmart despite housing cycle exposure
Company page: JB Hi-Fi (JBH), Wesfarmers (WES), Harvey Norman (HVN)
Bullock questions whether rates are high enough
[11:16 am] Michele Bullock told a parliamentary panel the RBA must decide this month whether policy is restrictive enough to return inflation to target.
Traders lifted the odds of a September hike to roughly 90% from about 84% before the testimony, with three-year yields trimming an earlier decline and the Australian dollar edging higher
Bullock said the key question is whether tightening to date will be sufficient to bring inflation back to target in a reasonable time, with the board meeting in just over a week
Some of the upside risks flagged in the RBA's August forecasts appear to be materialising, she said, even as growth in the Australian economy slows
The bank's liaison program shows many firms passing on higher input costs, with Bullock warning inflation could prove more persistent and require a stronger policy response if that becomes embedded in price and wage setting
She flagged little early prospect of a resolution to the Middle East conflict, with Brent back above $100 a barrel this month adding to energy-linked inflation pressure
The cash rate has been held at 4.35% for two straight meetings, with the Fed this week hiking for the first time since 2023 and projecting further increases
Source: Bloomberg
India heads for driest monsoon since 2009
[11:16 am] A strengthening El Niño has cut India's monsoon rainfall well below normal, raising crop and food-price risks.
Cumulative June to September rainfall is 15% below the long-term average, per the India Meteorological Department, against a forecast 10% shortfall issued back in May
Global Weather Climate Analytics' Christian Werner expects the seasonal deficit to hold between 13% and 16%, with a possible Bay of Bengal cyclone in late September unlikely to shift the national picture
Lancaster University's CRUCIAL prediction platform assigns a 68% chance the season ends with a deficit of 10% to 20%, with less than two weeks of monsoon remaining
QuantEco's Yuvika Singhal estimates every 1 percentage point shortfall in rainfall typically lifts food inflation by about 25 basis points
Food costs rose for a seventh straight month to 5.95% in August, the highest this year, with rice, sugar cane and corn plantings running behind last season
The government has allowed duty-free sugar imports and is selling subsidised onions in some states to cool prices, with India among the world's biggest producers of rice, sugar and cotton
Source: Bloomberg
Top ASX 200 gainers
[10:27 am] Gold stocks opened broadly higher, with the ASX All Ords Index up 3.1% in early trade.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
PDI | Pdi Gold | 12.4% | $4.91 | 4.5% | 34.5% |
IPX | Iperionx | 7.4% | $2.92 | 6.2% | -47.0% |
MP1 | Megaport | 6.1% | $18.28 | 1.6% | 61.1% |
KCN | Kingsgate | 6.0% | $5.49 | 4.6% | -2.0% |
MI6 | Minerals 260 | 5.8% | $0.95 | 10.7% | 126.7% |
EMR | Emerald Resources | 5.1% | $7.16 | 2.3% | 14.0% |
PNR | Pantoro Gold | 4.6% | $2.73 | 5.4% | -44.3% |
CYL | Catalyst Metals | 4.6% | $6.83 | 6.9% | -7.5% |
OBM | Ora Banda Mining | 4.6% | $1.49 | -2.3% | -2.6% |
GGP | Greatland Resources | 4.2% | $10.91 | 1.5% | 4.0% |
Top ASX 200 losers
[10:27 am] Energy and consumer-facing stocks are lagging in early trade, with Staples (-0.5%), Telcos (-0.2%) and Energy (-0.1%) the worst performing sectors.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
JHX | James Hardie | -2.9% | $36.39 | -6.9% | 17.4% |
TUA | Tuas | -2.7% | $2.18 | 6.3% | -69.1% |
KAR | Karoon Energy | -1.8% | $1.81 | -4.1% | 17.7% |
DMP | Domino's Pizza | -1.6% | $19.14 | 0.8% | -9.0% |
JDO | Judo Capital | -1.5% | $0.98 | 0.0% | -44.9% |
HVN | Harvey Norman | -1.3% | $4.12 | -2.0% | -41.0% |
NEC | Nine Entertainment Co | -1.3% | $0.79 | -6.5% | -29.3% |
ALL | Aristocrat Leisure | -1.2% | $60.81 | 2.4% | 5.3% |
REH | Reece | -1.1% | $16.36 | -0.8% | 22.6% |
EVT | EVT | -1.1% | $13.14 | -1.5% | 2.7% |
Miners bounce, ASX 200 on a three-day win streak
[10:21 am] The ASX 200 is up 36 pts (+0.41%), extending a 1.1% gain over the past three sessions. Miners are broadly higher after copper, gold, aluminium and most other commodities rose overnight. The Materials sector has added around 2% across those three sessions, though it remains 9.2% below its 25 August record high.
S&P/ASX 200 sectors (Source: Market Index)
UBS on Dyno Nobel's investor day
[10:13 am] Dyno Nobel revised FY26 guidance and unveiled a new FY31 EBIT ambition at its investor day, with UBS retaining Neutral and a $3.75 target.
Explosives EBIT guidance narrowed to $480m-$490m from $460m-$500m, with the midpoint 2% below consensus and the upper end 1% below
NPAT guidance of $312m-$327m (ex $13m Phosphate Hill NPAT in 1H) implies 5% upgrades to consensus at the midpoint despite the softer EBIT guide
New FY31 EBIT ambition of $800m sits about 30% above consensus of $607m and assumes high single digit revenue growth from FY26-31, against consensus of roughly 3%
The incremental $200m of EBIT above the reiterated $600m FY28 target is split across commercial (35-45%), operational (15-25%) and growth (35-45%) initiatives, including $30m-$40m from North American energetics via the Nitradyn JV
Energetics flagged as a priority growth market, with the addressable market seen roughly doubling to $10.5bn-$13.5bn by 2035, first TNT production expected in 2028 and IMX in 2030
Dyno Nobel shares opened the Thursday session flattish but trended aggressively higher, closing the day up 7.7%.
Company page: Dyno Nobel (DNL)
UBS initiates on Emerald Resources at Buy, $8.75 target
[10:12 am] UBS has started coverage of Emerald Resources, pointing to a self-funded path from one mine to three. The stock is up 4.70% to $7.13 in early trade.
Emerald operates the Okvau gold mine in Cambodia, a roughly 100kozpa platform, with construction of Dingo Range in Australia and Memot in Cambodia both slated to start in SepQ26 to lift group output above 300kozpa
UBS notes no publicly available studies exist on the three development projects, leaving few anchors for modelling, with capex requirements and the aggressive build timeframes in consensus estimates its chief concerns
Grade streaming at Okvau has brought forward ounces and built roughly two years of low-grade stockpiles, though grade should trend back to or below reserve grades without material discoveries
Underground works at Okvau have run since SepQ25 but detail beyond the 5.5g/t resource grade is scant, with UBS cautioning against dragging on grade streaming for too long
Company page: Emerald Resources (EMR)
Arafura extends offtake with wind turbine OEM
[9:34 am] Arafura has executed an extension of its existing binding offtake agreement with a global wind turbine manufacturer for Nolans material.
Annual contract volume of 500tpa of NdPr oxide equivalent, with optionality providing flexibility to both parties while retaining volumes sufficient to satisfy ECA required offtake
Five-year term with potential extension out to eight years, and deliveries aligned to the Nolans project schedule
Pricing in USD and linked to a global seaborne index such as the recently established Benchmark Mineral Intelligence indices or S&P's Global Platts North America pricing index
The counterparty operates in renewable energy, spanning design, manufacturing, installation and maintenance of wind turbines, with the agreement subject to customary conditions precedent
Arafura said it will no longer disclose offtake counterparty identities unless material, citing ongoing discussions with a number of parties and the need to protect its negotiating position
Company page: Arafura Rare Earths (ARU)
Finbar starts construction at Romeo
[9:12 am] Finbar has begun construction on the third and final stage of its Applecross Precinct in Perth.
103 sales achieved since the March launch, representing 66% of the 155-lot project and $121.1m in presales, including all three ground-floor commercial lots
18 lots sold for $26.3m since 1 August, with investors accounting for around 50% of purchasers, which CEO Ronald Chan flagged as encouraging given the headwinds that followed the negative gearing and CGT reforms announced in the May 2026 Federal Budget
Group pre-sales value now $536m, or about 67% of available product sold across current projects, with 37 sales worth $44.3m across off-the-plan and completed stock in the seven weeks from 1 August
Chan said the recent activity points to underlying buyer demand and continued appeal of Finbar's product notwithstanding broader market uncertainty
Romeo carries an estimated end value of about $192m, comprising 152 apartments plus three commercial lots, with completion targeted in H1 FY29
Five-year pipeline of $1.95bn across more than 1,900 units, which the company says supports earnings visibility and growth
Company page: Finbar Group (FRI)
Macmahon to acquire Aspect Engineering Solutions
[9:04 am] Macmahon has agreed to buy 100% of Aspect Engineering Solutions, adding engineering and minerals processing to its mining services platform.
Headline enterprise value of $75m on a debt-free, cash-free basis, equating to roughly 5.0x FY26 EBIT against Macmahon's referenced trading multiple of 11.4x as at 30 June 2026
Aspect generated FY26 revenue of about $75m and EBIT of $15.2m, with more than 295 direct employees and over 50 active clients across resources, infrastructure and energy
Contracted backlog of about $66.6m as at 31 May 2026, with an unweighted pipeline of roughly $225.8m
Consideration funded from existing cash, structured as $30m upfront, $30m of retention payments over five years and earn-outs of $15m to $30m over three to five years
Expected to be underlying EPS accretive from inception at around 6.2% pre-synergies, with a base case IRR of 40.4%
Aspect will be run as a standalone business retaining its brand and leadership, with completion subject to regulatory clearances and expected in the current calendar year
A ~$2.1bn company making a ~$75m acquisition that's 6.2% EPS accretive? Sounds pretty good no?
Company page: Macmahon Holdings (MAH)
Forrestania's Zenith bid proceeds after Panel orders
[9:03 am] The Takeovers Panel has issued orders in the Zenith Minerals matters, but they do not block the offer from continuing.
Forrestania has acceptances from Zenith shareholders holding around 49.23% of shares, giving it a relevant interest in approximately 58.33%
The Panel issued orders on 17 September following a declaration of unacceptable circumstances, requiring Forrestania to undertake certain steps, which it says it will comply with
A further supplementary bidder's statement will be sent to Zenith shareholders covering the information required by the Panel and bid instruction matters
Executive Chairman David Geraghty said the Forrestania offer is the only one available to Zenith shareholders, and that the company looks to free the offer of all remaining conditions at the earliest opportunity
Forrestania has completed its acquisition of the Edna May Gold Project and expects to commence gold production moving into the start of 2027
Company page: Forrestania Resources (FRS)
A broad-based bounce for commodities
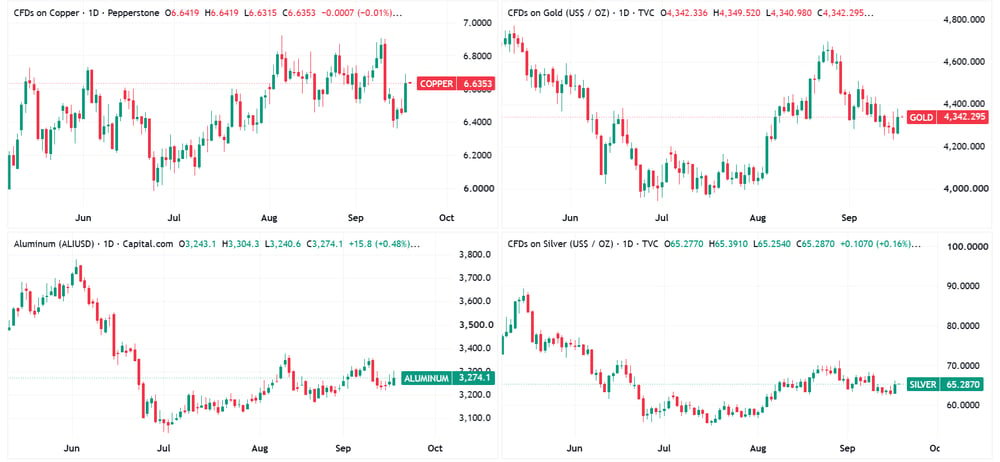
[9:00 am] Commodities traded broadly higher, though most of the move was a bounce off the sharp pullback of recent days.
Copper up 2.74% to US$6.63/lb, recovering half its recent losses after US refined copper tariffs stalled and broader markets weakened
Gold up 1.81% to US$4,341/oz, reversing three days of declines though still trending lower since the 25 August high
Aluminium up 0.48% to US$3,274/t, with prices choppy over the past two months
NYSE-listed BHP rose 2.8% to US$86.56, Rio Tinto up 2.3% to US$98.04, Newmont up 2.1% to US$124.39, Alcoa up 1.5% to US$46.97
TSX-listed Capstone Copper up 5.3% to C$14.22, FireFly Metals up 4.1% to C$1.76, PMET Resources up 3.1% to C$4.27
Copper, gold, aluminium and silver price charts (Source: TradingView)
A 5-handle on the 10-year has been the worst zone for equities
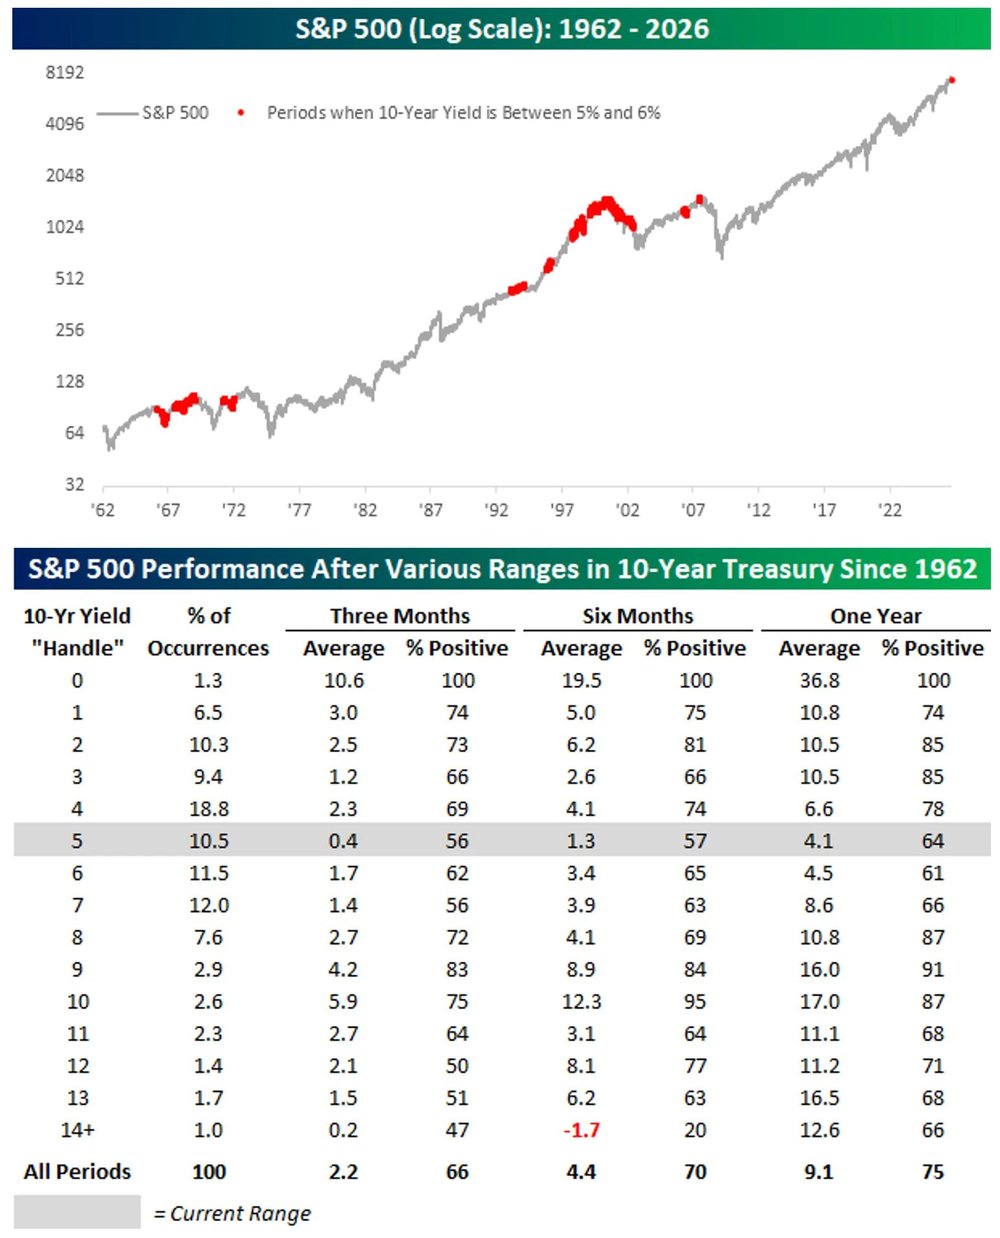
[8:47 am] Since 1962, S&P 500 forward returns weaken when the US 10-year yield is trading between 5-6%, according to Bespoke Investment Group.
With the 10-year in the 5% handle, the S&P 500 has averaged just 0.4% over the following three months, the weakest of any yield range apart from the 14%-plus bucket
Six-month returns average 1.3% and one-year returns 4.1%, against all-period averages of 4.4% and 9.1% respectively
Hit rates fall too, with only 56% of three-month periods positive, 57% of six-month and 64% of one-year, versus 66%, 70% and 75% across all periods
The 5% handle covers 10.5% of observations since 1962, clustered in the late 1960s, the late 1990s through 2002 and briefly in 2007
Source: Bespoke Investment Group
JPMorgan drops its oil baseline view
[8:43 am] JPMorgan's commodities team says it no longer has a base case for crude for the first time since the Iran conflict began.
JPMorgan wrote it has no baseline view on oil, saying "we simply don't know how to model the endgame," and that the assumption Middle East disruptions are temporary is "becoming increasingly difficult to sustain"
The bank had assumed economic red lines the Trump administration would not cross, but six months on says "many of those lines have been crossed, yet the exit strategy is less clear, not more"
On inventories, the team concluded fears of stocks being exhausted as a balancing mechanism are premature, with ample cushion for a prolonged disruption before operational stress levels are reached
That inventory buffer limits the need for crude prices to move materially higher in JPMorgan's view, despite the bank having modelled a dramatic collapse in global oil inventories back in April
Trump flags possible end to Iran war as crude retreats
[8:39 am] Oil pulled back for a second session as Saudi Arabia rerouted exports through Hormuz, though Brent remains above $100.
Trump said the US is "hopefully" toward the end of the nearly seven-month war and has spoken with Tehran directly, with a meeting of Gulf Cooperation Council leaders planned on the sidelines of the UN General Assembly next Tuesday
Saudi Arabia is seeking to restore about half the damaged East-West pipeline's capacity within days and full operations in roughly six weeks, with Rapidan expecting Saudi exports to fall 400,000 barrels per day this month
Kpler's Matt Smith noted ship-to-ship transfers in the Gulf of Oman have risen to 2.7 million barrels per day from 1.5 million in August, with cargoes loaded outside Hormuz to avoid Iranian attack risk
European gasoil and US ultra-low sulfur diesel futures both settled at record highs, with US retail diesel hitting a record just shy of $6.40 a gallon, and Goldman Sachs noting refiners are prioritising diesel over gasoline
DBS Bank's base case for the fourth quarter assumes US-Iran tensions ease and Brent stabilises at $85 to $95, while Geopolitical Strategy's Michael Feller warns the war could run to late 2028 without a post-midterms deal
BOJ set for fastest hiking pace since 1990
[8:38 am] The Bank of Japan is expected to lift its policy rate to 1.25% from 1% on Friday, the second increase in three months.
All BOJ watchers surveyed by Bloomberg expect a 25 basis point hike to 1.25%, the shortest gap between increases since March 1990 and Governor Kazuo Ueda's sixth
With the move almost fully priced by overnight index swaps, focus shifts to whether Ueda signals a faster track, with over 90% of surveyed analysts expecting a follow-up hike by January
The yen weakened as much as 1% overnight to 156.42 per dollar after the Fed's hawkish hike, with SMBC Nikko seeing 158 as the next upside target for dollar-yen if the meeting reads dovish
Citigroup strategists including Osamu Takashima see dollar-yen as high as 159 near term, but argue repeated intervention and attractive JGB valuations point to a major top reached this summer
Japan spent a record ¥15.4 trillion ($98.6 billion) on intervention in the month through 26 August, and another push toward 160 could test official tolerance
Overnight yen volatility hit its highest since early August, while leveraged traders halved bearish yen wagers in the week through 8 September
Source: Bloomberg
Triple witching collides with Fed and BOJ
[8:36 am] Tonight's US quarterly derivatives expiry lands two days after a Fed hike and on the final day of the BOJ's September meeting.
Citadel Securities estimated $6.2 trillion of US options exposure was set to expire on 18 September based on data through 27 August, about 23% of total US options exposure in its dataset
September tracking to surpass June's $7.7 trillion expiration, though the figure measures gross notional rather than cash traded, with many contracts expiring worthless or replaced with later expiries
Futures rolling began early, with CME listing 14 September as the customary roll date, meaning heavy expiry-week volume can reflect September exposure shifting into December contracts
Settlement is spread across the session, with standard SPX options and index futures settling on the open via a Special Opening Quotation and PM-settled SPXW contracts landing later
Hedging flows around crowded strikes can amplify the initial macro move, so post-expiry sessions are the cleaner read on whether a move reflects repricing or positioning
Good morning!
[8:21 am] ASX 200 futures are up 44 pts (+0.50%). Here's what happened overnight:
Wall Street clawed back most of the week's losses, though only the second advance in nine sessions
S&P 500 (+1.14%), down just 0.25% for the week
Equal-weight S&P 500 (+0.49%) underperformed the cap-weighted index by 65 bps as sectors like Financials (-0.10%) and Staples (-0.01%) lagged
Nasdaq (+1.69%), Dow (+0.61%) and Russell 2000 (+0.55%)
A second straight fall in oil, with Brent down 1.6% to US$103.92 a barrel, pulling the 10-year Treasury yield back below 5.0% and snapping its eight-day rising streak
Friday brings a collision of the quarter's triple witching options expiry and a Bank of Japan decision, with a 25 basis point hike to 1.25% widely expected